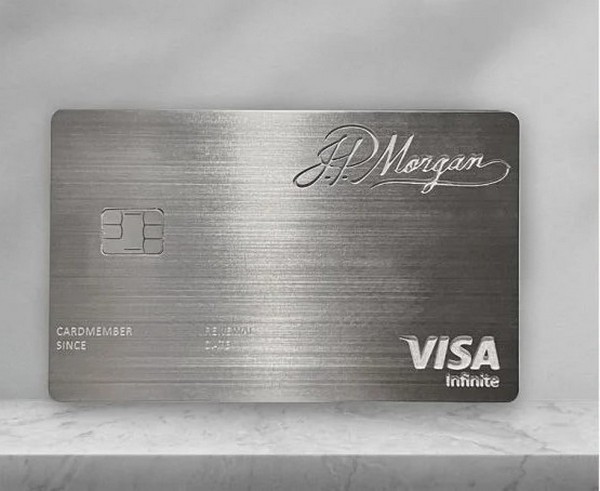
The JPMorgan Palladium Card: A Practical Look
I don't usually write about credit cards, but this one comes up enough in conversations I've had that I figured I should just lay out what it actually is and whether it's worth your consideration. The JPMorgan Palladium Card is a premium rewards credit card offered through JPMorgan's private banking and high-net-worth client channels. It's not something you just apply for on a random Sunday evening through a consumer portal. You generally need to be working with a JPMorgan relationship manager, which means your bankable assets are typically in the six figures or higher. That's the first thing to understand before anyone starts telling you about the perks. The card itself sits somewhere between a traditional premium card like the Amex Platinum and a private banking product. It carries a significant annual fee — I'm looking at something in the $450 to $600 range depending on your relationship tier and any bundled benefits. The rewards structure is points-based, and the earning rates vary by category. Travel and dining tend to sit around 2x to 3x points per dollar, while everything else runs closer to 1x. Not extraordinary compared to what some competitor cards offer, but the real value proposition isn't in the base earning rate. It's in the redemption floor. When you redeem points through JPMorgan's travel portal, you can sometimes hit values of around 1.5 cents per point or higher during promotional periods. More importantly, you can transfer points to airline and hotel partners, which is where people who actually understand rewards programs find the money. Transferring to partners like Marriott Bonvoy or various airline programs can push the effective value per point well above 2 cents, sometimes significantly more depending on the award chart and availability.
I ran into a specific issue last year that illustrates how this card actually works in practice. I was trying to book a Business Class award flight through one of the transfer partners using Palladium points. The transfer posted immediately, but when I went to book, the availability that showed up in the partner's search engine wasn't actually bookable with points at the displayed rate. The website showed a seat, but the booking engine rejected it. This happens more often than you'd think with award travel — the inventory shows as available but the actual booking fails because of a sync delay between the airline's revenue seats and their award seats. My workaround was straightforward but not obvious if you haven't dealt with it before. I called the airline's award travel desk directly instead of booking online. The representative could see the real-time availability and confirmed the seat was actually open for booking with points. The online system had stale data. This alone saved me from either paying full price for the ticket or losing the points to a botched transfer. It's a small thing, but it's exactly the kind of friction that separates people who use rewards cards effectively from people who just swipe and forget. Here's something most reviews won't tell you about this card: the purchase protections and concierge service are actually where the annual fee starts to make sense if you're the type of person who uses them. The concierge isn't some marketing gimmick. I've had it arrange last-minute hotel bookings during fully sold-out conventions, track down hard-to-find prescription medications for family members traveling internationally, and coordinate ground transportation when my flights got delayed overnight. It's not magic — it's just staffed people who have relationships with vendors and hotels. But having access to that through your bank instead of figuring it out yourself on the spot has real utility if you travel frequently or manage a busy schedule.
The travel insurance coverage is another area that gets overlooked. This card includes primary rental car insurance, which means you don't have to claim through your personal auto policy first. I had a minor fender bender in a rental car in another state and the entire claim process through the card's insurance provider took about three business days from notification to resolution. My personal deductible was never touched. For comparison, filing that same claim through my auto insurer would have involved a deductible, a claims adjustor call, and probably weeks of back-and-forth. Primary coverage matters more than people realize. Now let me talk about the things that don't work the way you'd expect. The lounge access with this card is limited. You don't get automatic Priority Pass membership the way some competing cards do. You get access to select JPMorgan lounges and occasionally partner lounges depending on your tier, but if you're a frequent traveler who relies on airport lounges as a baseline expectation, this card will disappoint you. The Amex Platinum and the Chase Sapphire Reserve both offer far broader lounge networks. If lounges are a dealbreaker for you, look elsewhere. Another counter-intuitive point: the foreign transaction fee structure. Some premium cards advertise no foreign transaction fees as a major selling point. The Palladium Card does charge foreign transaction fees on purchases made outside the United States, typically around 2.7% of the transaction amount. This is actually higher than what many mid-tier cards charge. If you travel internationally or shop from international merchants regularly, this fee adds up fast. A single $5,000 hotel booking abroad costs you an extra $135 in fees. That's not a typo. It significantly erodes the value of any travel rewards you earn on those purchases.
Get the Full Details

The application process itself is another friction point I want to flag. You can't apply online with just your personal information and a Social Security number. JPMorgan requires a relationship manager referral or an existing banking relationship before they'll even review your application. This means if you're not already a JPMorgan client, you're looking at opening a deposit account, potentially transferring significant assets, and building a relationship before you even get to the credit decision. For someone who already banks with them, this is a non-issue. For everyone else, it's a substantial barrier that eliminates this card from consideration until you've already committed to the relationship. I should also mention the credit limit dynamics. Premium cards like this one typically come with higher credit limits than standard consumer cards, which is good for your credit utilization ratio if you manage it properly. But I've seen situations where the credit limit gets lowered unexpectedly after a period of heavy travel spending. The algorithm that monitors your usage doesn't always distinguish between responsible high spending and spending that looks like financial stress. One of my contacts had his limit cut by roughly 30% after a two-week trip across Europe where he put $8,000 on the card. He called JPMorgan, explained the situation, and got it restored within a week, but the temporary hit to his credit utilization spiked his score by about 25 points in the interim. It's worth keeping in mind if you have other credit goals in motion. Is it worth the hype? The hype around this card is real but mostly concentrated in rewards forums where people calculate optimal point redemptions and transfer bonuses. In that world, the Palladium Card can absolutely deliver strong returns — I've personally seen redemptions that net out to over 3 cents per point when you combine transfer bonuses with sweet-spot award charts. But that requires research, timing, and a willingness to spend the time managing the program. If you're going to set it and forget it, you're getting mediocre value for a card with this fee structure.
For the average person who just wants a nice card with some travel perks and doesn't want to think about points optimization, I'd suggest looking at the Chase Sapphire Reserve or even the Capital One Venture X. Both have stronger lounge access, no foreign transaction fees, and a simpler rewards structure that still delivers solid value without requiring you to study award charts. The Palladium Card is better suited for someone who already banks with JPMorgan, travels internationally but doesn't mind the foreign transaction fee hit, and is willing to invest time in understanding the transfer partner ecosystem. One more thing nobody talks about: the card's impact on your overall banking relationship. Having a JPMorgan credit card can actually help when you're negotiating terms on other products — mortgage rates, line of credit adjustments, wealth management fees. Relationship managers have more flexibility when they see you're a multi-product customer. It's an indirect benefit that doesn't show up in any comparison chart but can be worth thousands of dollars over time if you're actively managing your financial relationships with the bank.