How UPI Actually Works Under the Hood
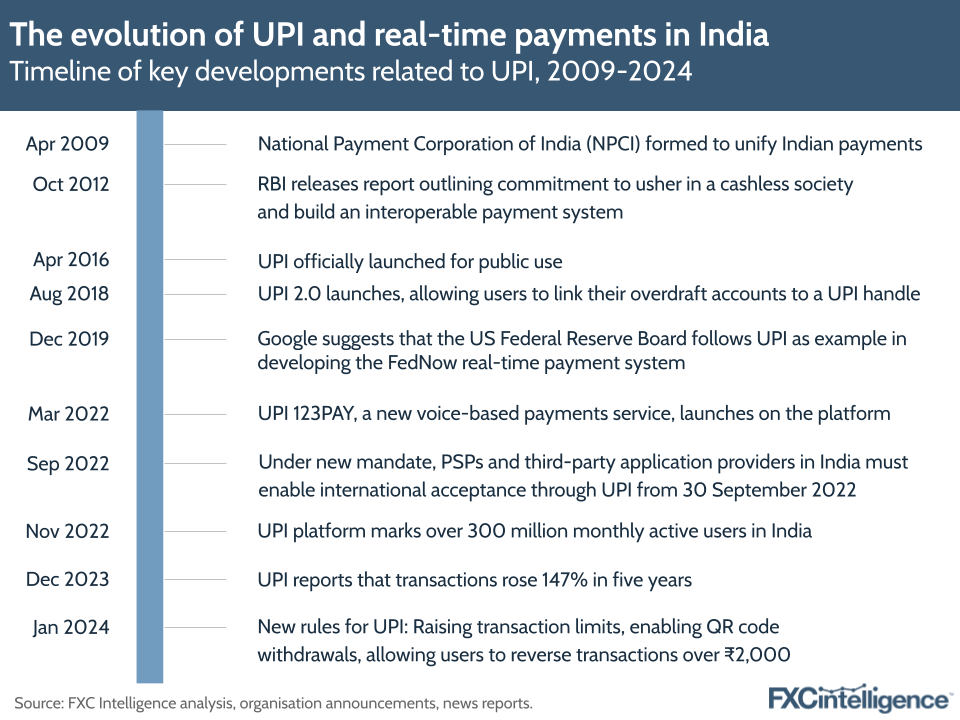
UPI runs on a simple idea that took years to build out. Every user gets a virtual payment address, usually called a UPI ID, that masks your actual bank account number. When you initiate a transfer, the message routes through the NPCI switch, hits your bank's server, gets approved, then travels to the recipient's bank server. Settlement happens in real time through the Reserve Bank's infrastructure. That's the whole loop. It sounds easy until you've spent two hours on hold with a support desk trying to trace a stuck transaction. The Unified Payments Interface was formally launched on April 11, 2016 by then Reserve Bank Governor Raghuram Rajan. But the idea started taking shape earlier, around 2009, when the RBI formed a committee to study electronic payment systems. By 2011, the concept of a unified interface was on paper. The National Payments Corporation of India, which NPCI operates under the RBI, was tasked with building it. The first production deployment connected three banks: Canara Bank, State Bank of India, and yes, the rest is well-documented. What most people don't realize is that UPI was designed from the start to be interoperable. Before UPI, each bank had its own app, its own wallet, its own QR codes. You couldn't send money from a HDFC account to a SBI user unless both parties used compatible apps. UPI changed that by creating a centralized switching mechanism. Any app that connects to NPCI can reach any bank that connects to NPCI. That interoperability is what made UPI scalable.
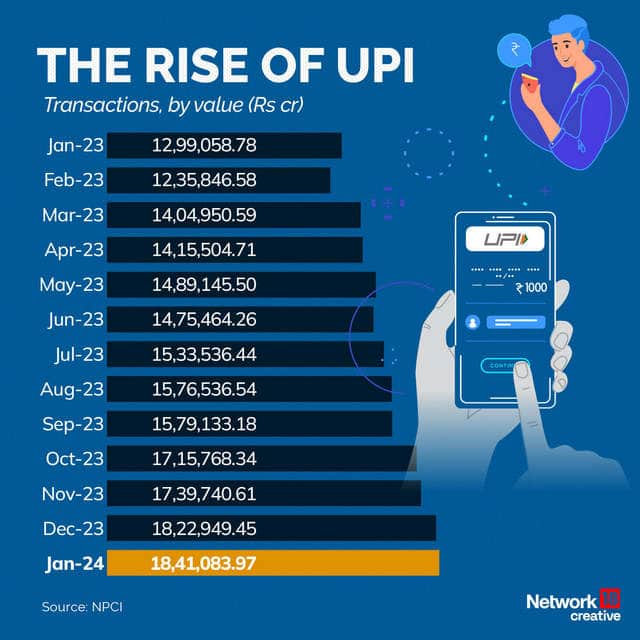
By 2024, UPI was processing over 12 billion transactions monthly, worth roughly 20 lakh crore rupees. India now handles more UPI transactions than most of the world's countries combine. Several countries including the UAE, Singapore, France, and Nepal have piloted or launched UPI-linked systems. France even integrated it into their payment infrastructure through a partnership with NPCI. I want to address something that comes up constantly. People assume UPI is some government invention. It isn't. It was built by NPCI, which is an autonomous organization headquartered in Pune. The RBI provided the regulatory framework and the settlement infrastructure, but NPCI did the actual architecture work. They built the authentication layer, the routing engine, and the standard protocols that all participating banks and apps follow.
The Practical Reality Of Using UPI Daily
Using UPI is straightforward if nothing goes wrong. Open your app, enter a UPI ID or scan a QR code, confirm with your PIN, and the money moves. Most transactions settle within seconds. The bottleneck is usually the receiving bank's server, not UPI itself. During peak hours, especially around festival seasons or salary credit dates, you'll see delays. I've personally watched transactions take anywhere from three seconds to three minutes depending on the time of day and which banks are involved. Here's a specific problem that nobody warns you about. If you've changed your phone number recently and updated it with your bank, your existing UPI PIN might stop working on some apps. The reason is that the VPA is tied to your mobile number at the bank level, and some UPI apps cache the authentication state differently. I encountered this when I switched carriers and my old number was deactivated before the bank update completed. The workaround was to unregister and re-register my UPI PIN on each app individually. It took about twenty minutes across three apps, and it's a process that isn't documented clearly anywhere. Another edge case involves split payments. If you're splitting a bill among friends using a single UPI transaction, the app sends requests to multiple recipients. If one person's bank is temporarily down, the entire split can fail, not just that individual portion. I learned this the hard way during a group dinner where four people tried to split a 2,400 rupee bill and it failed because one person's bank was undergoing maintenance. The workaround is to ask each person to pay their share separately rather than using the split feature.
Get the Full Details
Technical Details Most Beginners Miss
UPI uses the ISO 20022 messaging standard for transaction data. This is the same standard used by SWIFT for international payments, which is why UPI translations between domestic and cross-border systems are relatively smooth. The authentication is based on something called Device Binding, where your phone's IMEI is linked to your UPI PIN. This prevents someone from simply taking your UPI ID and PIN and using them on another device. There's a misconception that UPI transactions are always instant. They are, technically, but settlement between banks happens in batch cycles through the RTGS and NEFT systems. What you experience as instant is actually a promise from the sending bank that the funds are available, while the actual interbank settlement occurs later. This matters because if a bank's liquidity is low at settlement time, your transaction can still reverse even though it appeared successful. It's rare but it happens, and the money usually comes back within 24 to 72 hours. The UPI PIN is not encrypted on your phone. It's stored as a token that gets decrypted at the bank's server for verification. This is by design, not a security flaw. The alternative would be storing plaintext PINs, which would be worse. The token-based approach means even if someone intercepts data between your app and the bank, they won't get your actual PIN. What they might get is a transaction request that's useless without the authentication response from your bank.
Limitations are worth discussing openly. UPI has a per-transaction limit that varies by bank and by app. Most personal accounts cap out at 1 lakh rupees per transaction, though some banks allow higher limits with additional authentication. There's no way to send, say, 5 lakh rupees through UPI in a single shot from a standard retail account. For larger amounts, you still need NEFT or RTGS. This isn't a flaw, it's a risk control measure, but it's worth knowing if you're planning to use UPI for business payments. Cross-border UPI is another area with caveats. Yes, you can send money to Nepal, Singapore, and the UAE through UPI. But the exchange rates are often worse than what you'd get from a proper forex service, and the transaction limits are lower. I've seen people send money through UPI to Nepal and end up paying significantly more in hidden conversion costs compared to using a dedicated remittance channel. It's convenient, but convenience has a price.
Building Your Own UPI Integration
If you're looking to integrate UPI into an application, NPCI provides documentation through their partner portal. You need to register your organization, sign agreements with NPCI and the relevant banks, and pass a security audit. The process typically takes 4 to 8 weeks from application to go-live. The technical integration itself involves implementing the UPI protocol stack, setting up merchant IDs, and connecting to the NPCI switch through secure channels. The cost structure is straightforward. There's no per-transaction fee charged by NPCI for incoming transfers. Merchants pay a small percentage on outgoing or settlement transactions, and payment app providers charge their own fees on top. The exact rates depend on your volume and negotiation with your acquiring bank. For small businesses doing under 50,000 transactions monthly, the effective cost is usually between 0.2 and 0.5 percent per transaction. The QR code system in UPI is standardized under the IndiaQR framework. Every QR code contains the payee's UPI ID, their name, and sometimes their merchant category code. Scanning a QR code doesn't require an internet connection on the merchant side, which is why street vendors and small shops can accept payments reliably. The customer's phone does the internet work, not the merchant's device. This design choice was deliberate and it's one of the reasons UPI achieved such rapid adoption in tier 2 and tier 3 cities.
I should mention one more thing that most tutorials skip. UPI autopay mandates, sometimes called UPI e-mandates, are different from regular UPI transactions. An e-mandate allows a merchant to pull money from your account without you initiating each payment. They're used for subscriptions, loan repayments, and insurance premiums. The key difference is that e-mandates require explicit consent through a separate authorization flow, and you can cancel them at any time through your bank or the UPI app. I've seen people confused about whether a recurring charge was legitimate because they didn't realize they'd previously authorized an e-mandate. Check your UPI app's mandate section regularly. It shows all active auto-debit agreements and lets you revoke them in a few taps.