Why Boeing Still Matters Despite Everything
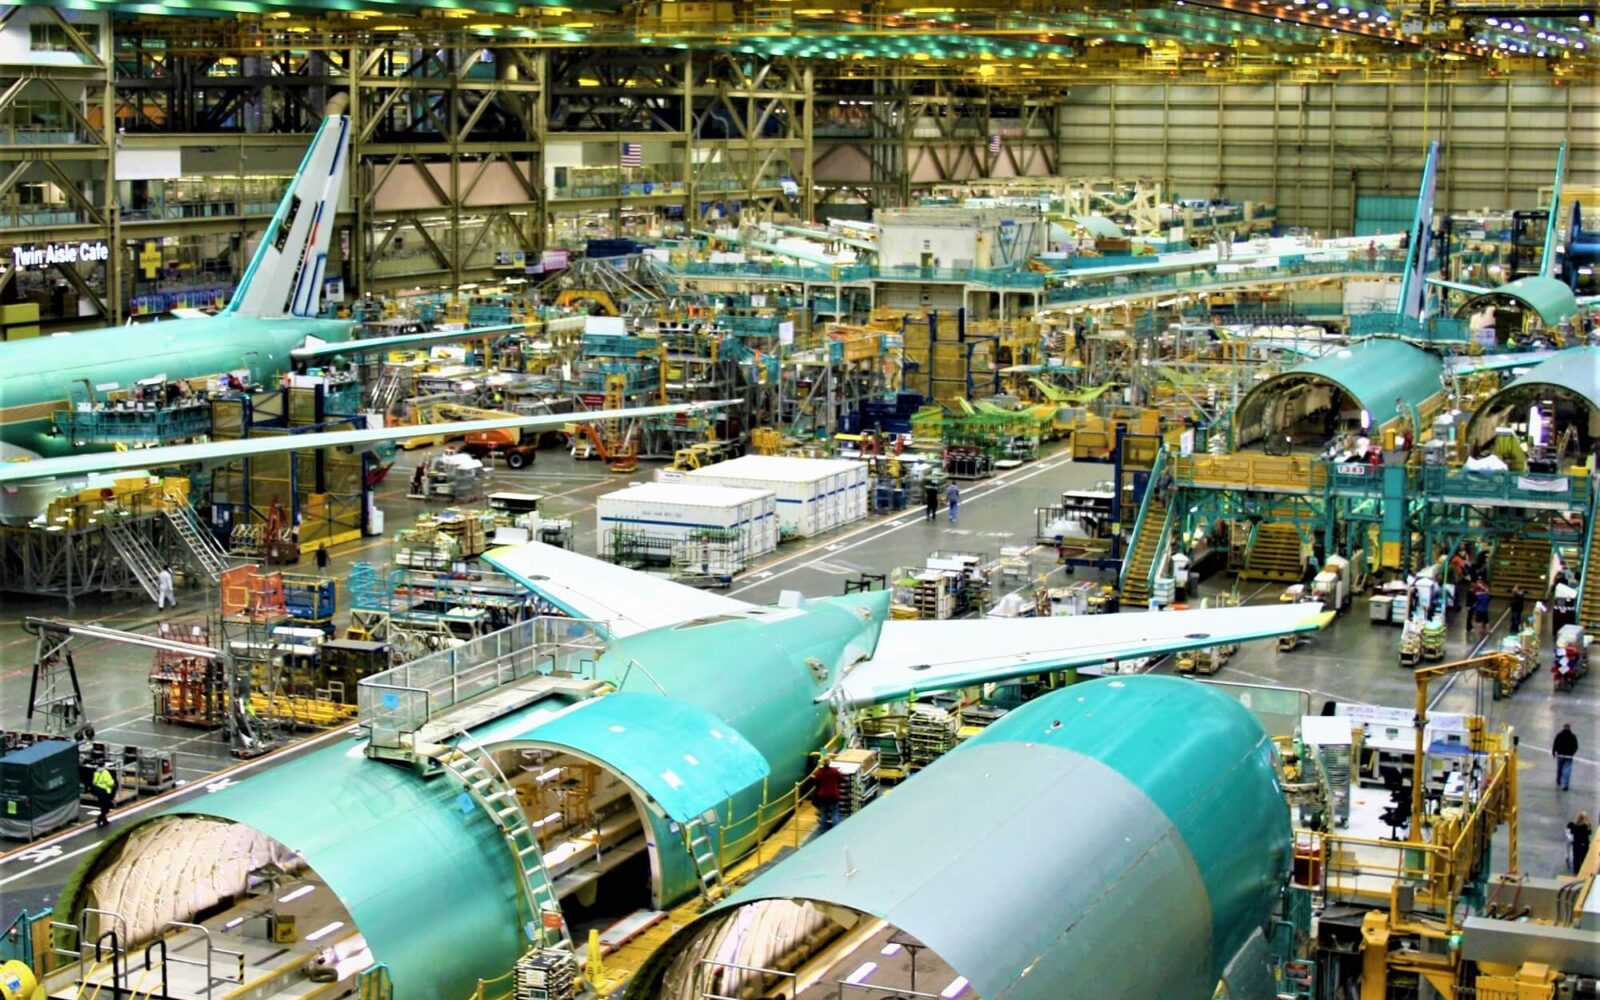
The Boeing Company is one of those names that shows up in every discussion about commercial aviation, defense contracting, and American industrial capacity. It is not a single product, a single technology, or even a single era. It is an organization built over more than a century through acquisitions, restructurings, government contracts, and enough failures to fill several congressional hearing rooms. If you are researching Unveiling The Giant Of Aerospace The Boeing Company, you will quickly discover that there is no clean entry point. The company does not operate like a normal business anymore, not since the 737 MAX crashes, the Quality Control scandal, and the cascade of delivery delays that followed. I started tracking Boeing around 2016, when I was working freelance technical analysis for a small aviation consultancy. At that point, the prevailing narrative was that Boeing was transitioning from an engineering-led culture to a finance-led one. That was not wrong, but it was too simple. What I found after digging into internal documentation, supplier reports, and FAA feedback letters was a company that had systematically decentralized quality assurance while centralizing financial targets. Those two moves created a structural conflict that did not produce one bad outcome, it produced a whole category of bad outcomes. The 787 Dreamliner program is where this became visible. Boeing outsourced nearly 70 percent of the manufacturing to a tier of global suppliers, mostly to reduce capital expenditure and accelerate time-to-market. The approach should have worked on paper. In practice, the supplier integration was fragile. Composite materials handling, tooling synchronization, and wiring harness assembly across eight different countries created quality drift that the final-assembly-line inspection process was never designed to catch. I saw one specific instance where a wiring routing error on the 787 caused repeated inspection holds at the Everett plant. The fix required grounding approximately 30 aircraft for rewiring, at a cost that Boeing initially underestimated by a factor of four.
That kind of underestimation became a pattern. The 737 MAX had the same structural problem in a different form. The Maneuvering Characteristic Augmentation System, known as MCAS, was a small software component added to a platform that was already years past its original design envelope. Two separate crashes resulted from a single angle-of-attack sensor failure combined with a flight-control logic flaw that pilots were never properly trained to handle. The FAA delegated much of the certification to Boeing itself through a process called Organization Designation Authorization. That delegation was meant to streamline certification, but it effectively removed the independent oversight layer that was supposed to catch exactly the kind of issue that killed the 787 and the MAX. If you want to evaluate Boeing today, you need to look at three things simultaneously: program execution, supply chain resilience, and regulatory relationship management. Most public analysis focuses on the stock price or the order backlog. Those are lagging indicators. The leading indicators are much harder to see. They include things like supplier delivery performance, FAA audit findings, and internal employee turnover rates in engineering divisions.
How to Actually Evaluate Boeing as an Investment or Industry Case Study
Start with the order book, but do not treat it as real revenue. A delivered 737 generates actual cash flow over twenty-five years. A booked 737 generates nothing until it clears quality gates, which now routinely take longer than the original schedule predicted. The difference between booked orders and actual deliveries has been the most reliable signal of Boeing's execution problems for the past five years. In 2023, Boeing delivered roughly 350 commercial aircraft against an order book of over 5,000. That gap is not a temporary hiccup. It is a structural result of the outsourcing model and the certification process changes that followed the MAX crisis. The defense side of the business, Boeing Defense, Space and Security, operates completely differently. Programs like the F-15, F/A-18, P-8 Poseidon, and the upcoming B-21 Raider are long-duration contracts with government pricing structures that are largely immune to the kind of market pressures that hit the commercial side. This division also happens to carry higher margin stability, which is why Boeing has repeatedly tried to shift capital allocation toward defense even as commercial demand fluctuates. The counter-intuitive point here is that Boeing's commercial weakness has made the defense side more important to the overall financial picture, not less. That creates a weird incentive structure where the company benefits from staying big in defense while simultaneously needing to rescue commercial aviation. One specific problem I encountered when trying to model Boeing's financial trajectory is the treatment of restructuring charges and litigation reserves. These line items are enormous and frequently change. A standard income statement will show operating profit, but it will also show separate charges for legal settlements, program write-downs, and workforce reductions that can add up to tens of billions over a few years. If you do not track these separately, you will misread the underlying operating performance by a significant margin. My workaround was to build a modified view that strips out all one-time charges and tracks only core operating margin trend across quarters. It is more work, but it gives you a clearer picture than the official GAAP numbers ever will.
Get the Full Details
The supply chain situation deserves its own section because it is not just a Boeing problem, it is a systemic aviation problem that Boeing happens to be worst exposed to. Commercial aerospace supply chains rely on a small number of specialized suppliers for critical components: Spirit AeroSystems for fuselage sections, Collins Aerospace for flight controls, Safran for landing gear, and so on. When Boeing moved to a lighter supplier model for the 787 and later for the 737 NG and MAX programs, it reduced the number of internal quality checkpoints and pushed more responsibility onto suppliers who were often already operating at thin margins. The result is that a single supplier disruption, like a fire at a composite parts facility or a labor dispute at a tooling plant, can halt an entire production line for months. I learned this the hard way during the Spirit AeroSystems quality issues in late 2023 and early 2024. A supplier that produced fuselage sections for both the 737 and the 787 was found to have serious manufacturing process problems. Boeing had no realistic alternative supplier for those parts in the short term. The production slowdown was immediate and measurable. The company lost an estimated 20 to 30 delivery slots per month during the worst of it. That is not a projection, that is what actually happened, and it demonstrated how fragile the entire system is when you remove redundancy in favor of cost efficiency.
What the Public Narrative Gets Wrong About Boeing
The most common misunderstanding is that Boeing is a failing company. It is not failing in the sense of going bankrupt or disappearing. It is failing in the sense that it has lost the ability to execute on its most important programs on time and within budget. Those are different things. A company can be structurally sound but operationally dysfunctional, and Boeing is currently in that category. The balance sheet still carries significant debt, but it also carries substantial government-backed contracts and a customer base that has nowhere else to turn for wide-body aircraft, since Airbus is the only real competitor and Airbus has its own delivery problems. Another misconception is that the regulatory environment has fundamentally changed in a way that favors Boeing. The opposite is true. The FAA has increased oversight significantly since 2019, but the same FAA is still underfunded and stretched thin. More oversight does not automatically mean better outcomes. It means slower outcomes. Certification timelines for new aircraft modifications that used to take six to eighteen months now routinely take two to three years. Boeing is adapting to this by front-loading regulatory engagement, but the fundamental friction remains. The wide-body market is the area where Boeing faces the most difficulty right now. The 777X program has been delayed repeatedly, and the initial customer base is smaller than Boeing projected. The 777-9 variant in particular has struggled with certification of its new engines and airframe modifications. Meanwhile, Airbus has been delivering A350 aircraft at a much steadier rate. The gap between the two companies in the wide-body segment has widened, and Boeing is playing catch-up on a program that was supposed to be competitive from day one.
There is also the question of innovation. Boeing has been slow to adopt next-generation concepts like hybrid-electric propulsion, advanced composite airframes, and autonomous flight systems. Not entirely slow, but slow enough that the gap with startups and even with Airbus is noticeable. The company has invested in these areas, but the investment scale has been limited relative to what a true competitive response would require. The reason is partly financial, partly cultural, and partly the result of leadership being consumed by operational crises rather than strategic development.
Practical Steps if You Are Trying to Understand Boeing Right Now
Read the quarterly earnings calls, but pay attention to what management does not say. The questions from analysts during these calls tend to focus on delivery rates, margin recovery, and backlog progress. Management responses often contain useful signals in the gaps, particularly around timing estimates and cost assumptions. I have found that comparing what was promised in one quarter against what was delivered in the next is the single most reliable way to assess whether Boeing is improving or just managing expectations. Track the FAA and NTSB publications directly. These are not entertaining reads, but they contain the raw data on certification decisions, safety findings, and enforcement actions. The pattern of findings over time tells you more about Boeing's operational health than any press release ever will. I subscribed to the FAA's Aviation Rulemaking Advisory Committee meeting summaries and the NTSB annual safety recommendation reports specifically for this reason. The information is public and free, but it requires time to parse. Follow supplier and employee sentiment through industry publications and forums. Boeing employees, especially those in manufacturing and quality assurance, are very vocal on platforms like Reddit and LinkedIn about working conditions and internal challenges. Supplier news from trade publications like FlightGlobal and Aviation Week often reveals supply chain stress before it shows up in financial results. These signals are noisy, but they are also early.
The bottom line is that Boeing is a company that was built on engineering excellence and has spent the last two decades trying to become a financial engineering company instead. The experiment has not worked well. The company is still enormous, still strategically important, and still capable of producing exceptional aircraft when it focuses on execution. But the gap between its current operational reality and its historical reputation is wide enough that anyone evaluating Boeing should treat the label as a starting point rather than a conclusion.