How I Actually Get Through Chicago Municipal Financial Reports
Most people open a city comprehensive annual financial report and immediately regret it. I spend a lot of time in them anyway. The trick is knowing which pages actually matter and which ones are filler. I started looking at Chicago fiscal documents around 2018 when I was helping a client understand why water bills were climbing. That led me down a rabbit hole I didn't really leave. The city's finances are complex, not because they're intentionally opaque, but because so many obligations overlap across different funds and time periods.
Unveiling The Finances Of The City Of Chicago A Deep Dive Into The Windy Citys Fiscal Integrity
Here is how I actually approach this stuff without losing my mind. First, skip straight to the Management's Discussion and Analysis section. It is in every CAFR. Chicago's tends to be longer than most cities, which is either generous or concerning depending on the day. Read it once for the surface narrative, then go back and highlight anything that contradicts what the audited financial statements say later. They rarely contradict each other outright, but the emphasis shifts. The real meat is in the fund-level statements. Chicago operates something like forty-five distinct funds. Most residents only ever interact with one or two. But the inter-fund transfers alone tell a story that the mayor's press releases never will. In one recent fiscal year, the city moved roughly 1.2 billion dollars between funds through various transfer mechanisms. That is not inherently bad. Governments use transfers as a normal operating tool. But you need to see them to understand where money is actually going and where it is being hidden.
Pensions are the elephant in every room. Chicago's four major pension systems hold combined assets that have grown past 100 billion dollars, with a funded ratio that has hovered somewhere between 50 and 65 percent depending on which year's actuarial assumptions you trust. I stopped trying to resolve that debate years ago. What matters more for understanding fiscal integrity is how the city budgets for pension contributions year over year. The difference between what the actuary says the city owes and what the city actually appropriates is where the structural deficit lives. I ran into a specific problem last year when trying to track pension payments across multiple fiscal periods. The city reports contributions at the fund level, but the pension systems report receipts differently. Numbers would not reconcile between the CAFR and the Independent Pension Funds annual reports. I ended up using a manual cross-reference worksheet pulling data from three separate sources: the city's budget documents, the CAFR notes on pension liabilities, and the individual pension system's audited financials. It took about four hours of work but gave me a clearer picture than any single document provided. If you are doing this for a project or analysis, build that spreadsheet early. Your future self will thank you.
Get the Full Details

The Documents You Actually Need
The city publishes a lot of information. The question is sorting signal from noise. The Comprehensive Annual Financial Report is the starting point. You can download it from the city's finance department website. It usually comes out six to nine months after the fiscal year ends. The current report covers fiscal year 2024, which ended in 2023. Chicago uses a calendar-based fiscal year, so the timing is straightforward compared to states that use odd cycles. Beyond that, the annually adopted budget document is essential. The city's budget does not always match reality. Revenue estimates get revised mid-year. Expenditure delays happen constantly. But the adopted budget shows what the city thinks it is doing, which is different from what it is actually doing but still useful as a baseline.
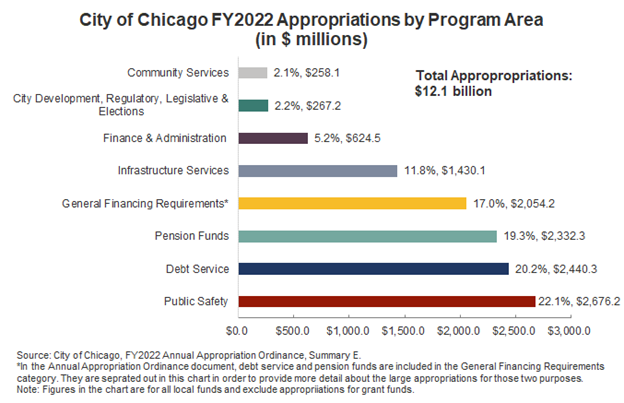
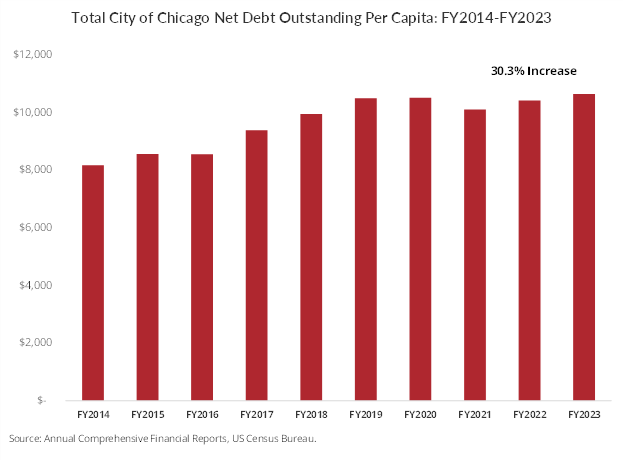
The debt issuance documents from the treasury department reveal the borrowing side. Chicago has been issuing general obligation bonds and revenue bonds at a pretty consistent clip. The interest costs alone consume a meaningful share of the operating budget. Looking at the debt service schedule alongside the pension obligations gives you a rough sense of the city's fixed financial commitments. Things that cannot easily be cut when revenues fall short.
What Most People Miss About Chicago's Money
The most counter-intuitive thing I have learned is that Chicago's structural deficit is not really a revenue problem. It is a commitment problem. The city can raise more money. It has done so through tax increases, fee hikes, and various revenue-generating mechanisms over the decades. The issue is that a large portion of the budget is locked into obligations that grow faster than the economy or the tax base. Pensions. Municipal bond debt. Health benefits for retirees. Overtime in police and fire. Each of these has contractual or legal dimensions that make them difficult to reduce quickly. When revenue dips, these categories do not dip with it. They continue growing. That gap is the structural deficit, and it has persisted across multiple administrations and political parties. Another thing beginners overlook is the role of state law. Illinois constrains Chicago's fiscal options significantly more than most people realize. The home rule provisions give the city some flexibility, but the state controls pension parameters, labor relations frameworks, and certain revenue sources. Chicago cannot simply decide to restructure its pensions without state approval. That constraint matters a lot when you are trying to assess the feasibility of various fiscal reform scenarios.

Where This Approach Falls Apart
I want to be straightforward about limitations. Reading CAFRs and budget documents will not give you a complete picture of Chicago's fiscal health. These are historical records. They tell you what happened, not what will happen. Forward-looking projections require understanding economic trends, policy decisions yet to be made, and variables that simply cannot be predicted from past documents. The numbers also depend heavily on actuarial assumptions. Pension funded ratios shift dramatically based on whether you assume a 7 percent or a 6.5 percent investment return. Small changes in discount rates create large changes in reported liabilities. Different reviewers will reach different conclusions about fiscal integrity depending on which assumptions they accept. There is no neutral baseline here. If you need current, granular financial data for decision-making purposes, the CAFR alone is insufficient. You would want to supplement it with quarterly financial reports from the finance department, the bond market's own analysis through rating agency reports, and independent municipal finance research from organizations like the Terner Center or the Abraham Lincoln Institute. Those sources provide context that raw financial statements cannot.
One more practical note. The city's financial data is publicly available but not always easy to navigate. The website organizes documents by fiscal year and by type, but finding a specific line item across multiple years requires patience. I keep a running spreadsheet of key figures and link directly to the source PDFs. It saves considerable time compared to searching from scratch each period.