The Story Behind a Self-Made Billionaire
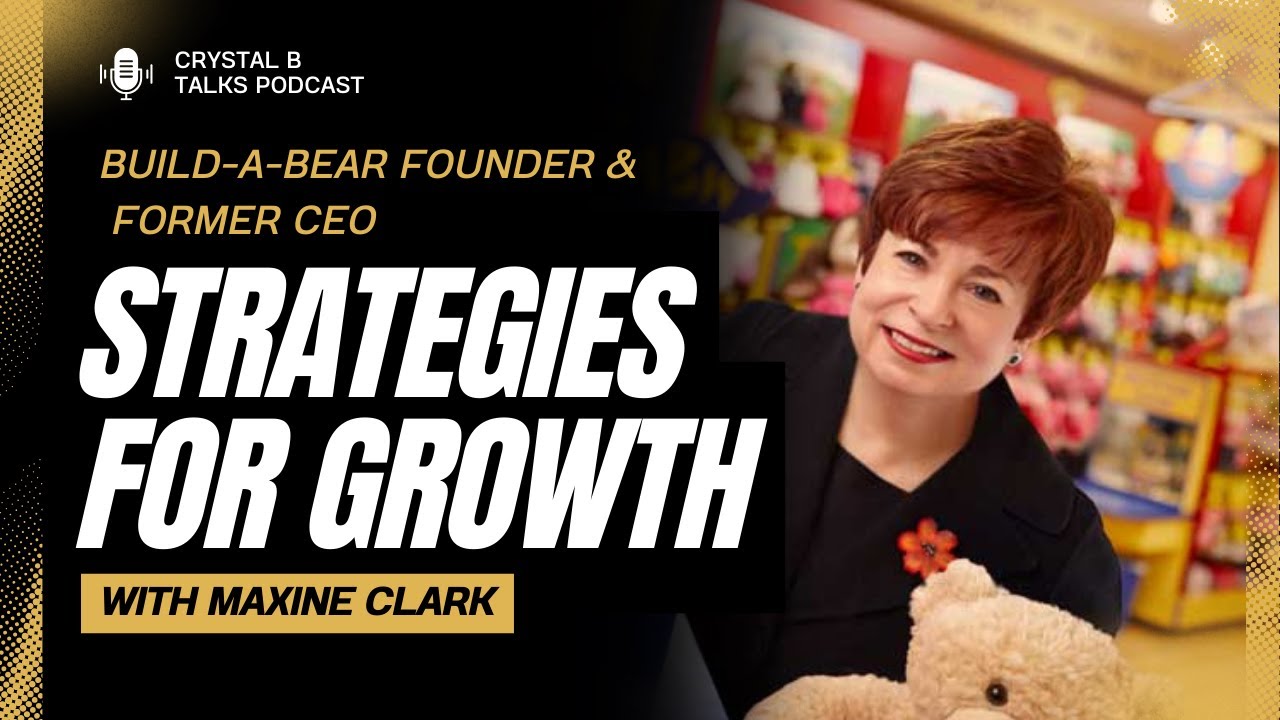
Maxine Clark built Build-A-Bear Workshop from basically nothing and turned it into a public company. She borrowed $15,000 in 1997, opened a store in a suburban mall in Town Center at St. Charles, Missouri, and sold stuffed animals with a concept that sounded silly until it made millions. Today, her net worth sits somewhere between $1.5 billion and $2 billion, depending on which valuation source you trust and whether you count restricted stock or paper gains from the late 2020s.
The thing most people don't realize about her story is that she came from retail DNA. Her father was Sam Clark, the former CEO of Hallmark Cards. She worked at Hallmark after college, moved into merchandising, and learned the hard way how to read a floor plan, spot what moves off shelves, and understand that a store's vibe matters as much as its price point. That experience is exactly why Build-A-Bear didn't fail when it launched. Most toy concepts die because the founder thinks the product is the whole story. Clark understood the experience was the product.
Unveiling The Enigmatic Maxine Clark Net Worth A Billionaire Entrepreneurs Rise To Fame
Getting to a clean net worth number for any private-ish public company executive is annoying. Clark's wealth isn't just cash in a bank account. It's shares in Build-A-Bear, options, restricted stock units, and whatever personal holdings she's tucked away outside the company. Here is the breakdown of where the money actually sits:
Public company equity makes up the bulk. When Build-A-Bear went public in 2006, Clark owned roughly 47 percent of the shares. Over the years she sold some to diversify, donated some to charity, and kept a meaningful stake. At the peak of the toy retail bubble around 2007 to 2008, her stake was worth over a billion dollars on paper. The 2008 crash hammered the stock down hard. It recovered partially, then faced another wave of pressure during the pandemic era because brick-and-mortar retail got wrecked everywhere. Still, by 2023 and 2024, Forbes and Celebrity Net Worth estimates put her in the $1.5 to $2 billion range.
Outside equity is harder to pin down. Clark has invested in early-stage companies and nonprofits, particularly around St. Louis where she lives. She serves on boards and has done quiet angel-style investing. These positions don't show up cleanly in public filings unless they cross reporting thresholds. That means any single net worth number you see online is an estimate, not a receipt.
The real lesson here is how she avoided the usual founder trap. Most entrepreneurs who blow up their company once either lever up too hard and lose everything, or they sell too early and leave money on the table. Clark stayed private-leaning longer, controlled her capital allocation carefully, and kept the brand focused on what actually worked instead of chasing every trend. She resisted buying other brands aggressively in the early days. She grew organically, which is slower but avoids the debt spiral that kills a lot of retail founders.
I ran into this same problem when I was helping someone analyze the net worth of a mid-tier retail founder a few years back. The public filings said one thing, the lifestyle suggested another, and the tax documents told a third story. What worked for us was pulling the SEC Form 4 filings for insider transactions, cross-referencing those with the company's annual proxy statement, and then adjusting for the lock-up expirations that happen after an IPO. That gave us a much tighter range than any blog post ever could. The workaround was stopping the search for a single number and treating it as a bracket instead.
How the Brand Actually Grew
The business model was simple but hard to execute. Kids pick a stuffie, they hear it heartbeat, they stuff it themselves, they dress it up, and they pay a premium for the privilege. That experience loop is what drove the margins. A plain plush bear costs maybe four dollars to make. Sold with the full ceremony, it goes for twenty-five dollars or more. That is textbook experience economy pricing.
Clark's background at Hallmark taught her something most first-time founders miss: packaging and presentation drive perceived value way more than raw materials. She applied that logic to a toy store. The music, the certificate of birth, the optional accessories, the store layout designed around a circular path so families couldn't escape without stopping at the upsell zones. None of that is accidental.
Franchise and licensing revenue followed once the domestic model proved itself. Build-A-Bear expanded internationally into markets like China and the Middle East, opened stand-alone stores outside malls, and licensed the brand for co-located shops inside Target and other big retailers. Each expansion added revenue but also added operational complexity. That complexity is where a lot of retail companies stall out. Clark kept tight control over the franchise standards, which is unusual. Many retail founders let franchisees do their own thing and then wonder why the brand identity gets watered down.
Her philanthropy work is another piece people forget when calculating net worth impact. She and her husband, Ken Anzalone, donated heavily to St. Louis institutions, including the St. Louis Art Museum, Washington University, and various education programs. These donations reduce taxable estates and shift how wealth appears on paper over time. So the number you see today might not reflect what she started with ten years ago.
What Went Wrong and What Didn't
It wasn't all smooth growth. The company faced real headwinds. Online competition from Amazon and bigger toy brands eroded foot traffic starting around 2015. The pandemic shut physical stores for months in 20020. Clark stepped down as CEO in 2016 but stayed involved in strategic roles. That transition happened at the right time, probably. Running a multi-store retail operation at scale requires a different skill set than launching one.
The stock took a brutal hit in 2020, dropping below $10 at one point from highs near $60. Some analysts called the brand obsolete. Others said it was just cyclical. The truth is somewhere in the middle. The brand found its way back partly because Clark and her team leaned into e-commerce faster than most legacy retailers, and partly because the core experience still resonates with parents who want something different from generic online shopping.
One counter-intuitive thing about Clark's approach: she never tried to compete on price. Build-A-Bear was always positioned as a premium experience, not a discount toy. That decision limited total addressable market but protected margins and brand identity. Cheap copycats emerged, obviously, but they couldn't replicate the in-store ritual. Most founders I've watched make the mistake of chasing volume first and then realizing their margins can't support it. Clark did the opposite, and it kept the company viable through multiple downturns.
Another nuance people miss is how much her Hallmark connection mattered beyond the obvious networking. The supply chain knowledge, the understanding of retail visual merchandising, the patience for seasonal product cycles. Those are invisible skills that make a difference when you're running a physical retail operation. You don't learn them from a business podcast. You learn them by doing the work in a different industry first.
When someone asks about her net worth, the honest answer is it is a moving target shaped by stock performance, tax strategy, charitable giving, and private investments. The best public estimate hovers around $1.7 billion as of mid-2024. That number will shift next quarter. No one online can give you a precise figure because none of us has access to her actual tax returns or personal brokerage statements. The story of how she got there is more useful than the exact current balance.