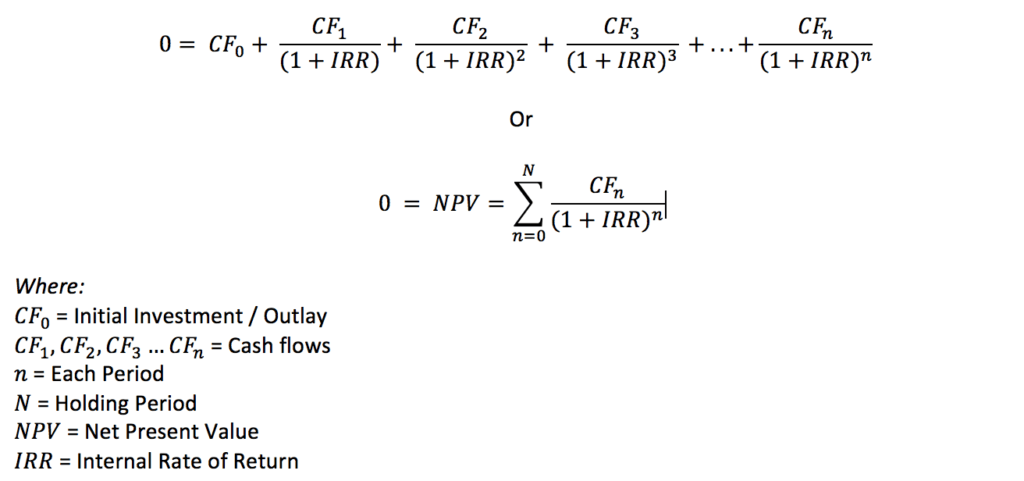
Working with Internal Rate of Return in loan calculations
IRR shows up everywhere once you start looking at loan structures beyond simple fixed-rate mortgages. Most people encounter it when they need to compare two loans with different fee structures, prepayment penalties, or irregular payment schedules. The math itself isn't difficult, but applying it correctly in real scenarios takes some care. I spent three years working loan modeling at a regional credit union before moving to product development. One thing that always trips people up is understanding what IRR actually represents when fees are bundled into the principal. A borrower might see a quoted rate of 6.5% and assume that's their cost of borrowing. When you factor in origination points, processing fees, and document charges, the effective rate can shift by a full percentage point or more depending on how long the loan is held.
Unveiling Irr In Loan Formulas A Comprehensive Guide
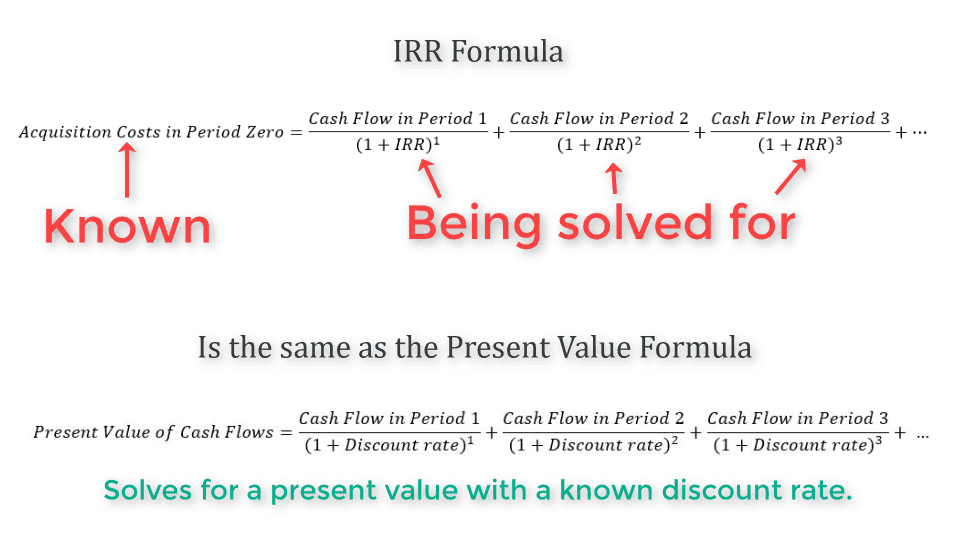
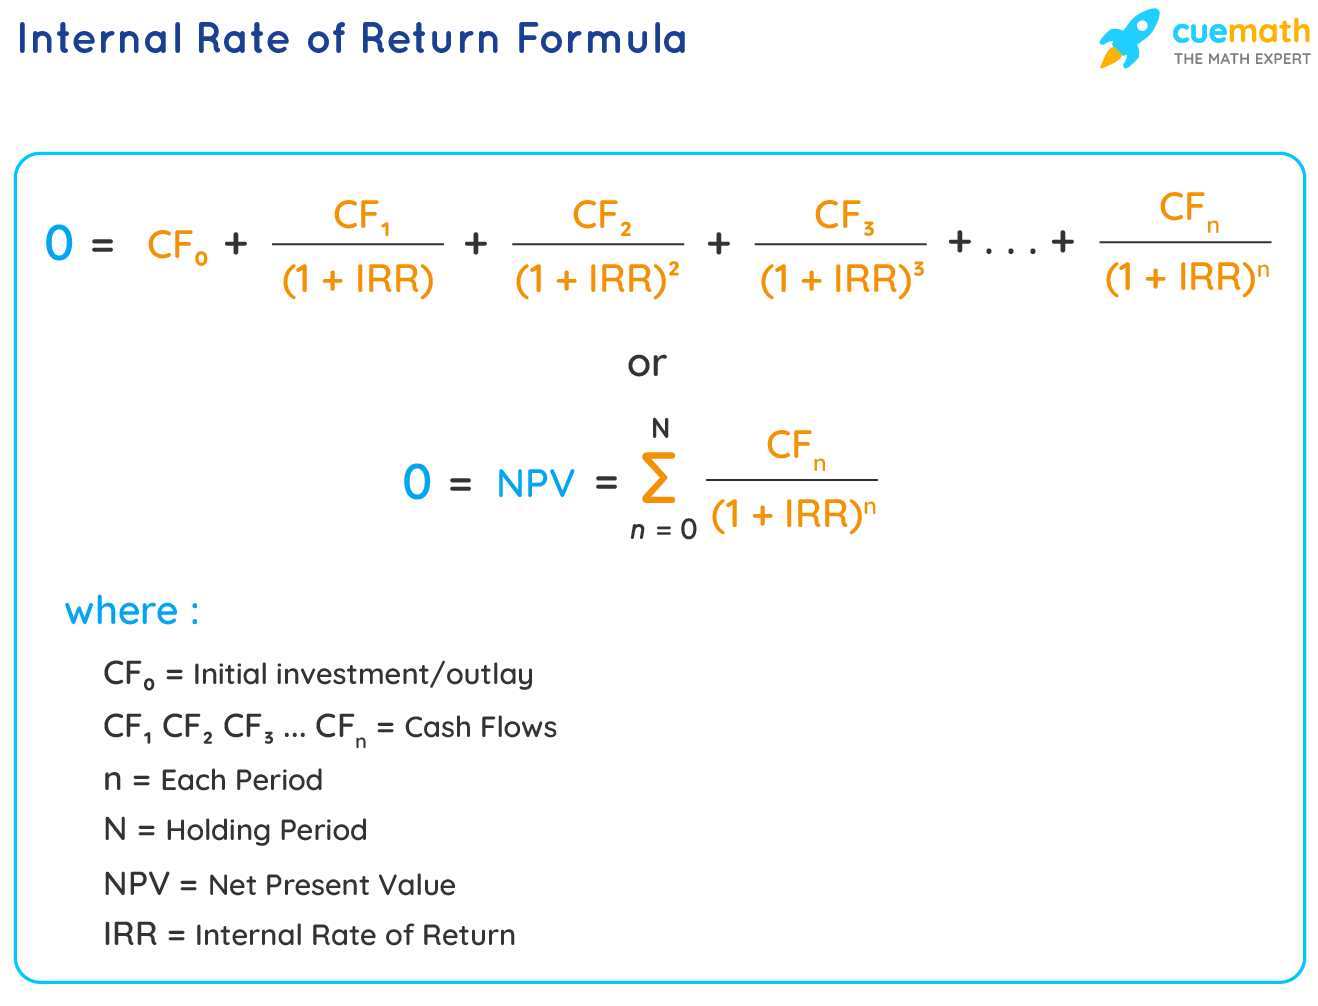
The core formula uses cash flows. Money received by the borrower is positive, money paid back is negative. Solve for the discount rate that makes the net present value equal zero. No closed-form solution exists beyond very simple cases, which is why numerical methods matter. In practice, I use the Newton-Raphson method or the secant method implemented in Python or even a well-configured spreadsheet. The iterative approach converges quickly when your initial guess is reasonable. Start with the stated interest rate as your first guess and let the algorithm refine from there. Most implementations converge within five to ten iterations for standard loan structures. Here's a concrete example I deal with regularly. A small business loan has a stated rate of 8% with two points upfront on a $150,000 balance over 60 months. The borrower receives $147,000 net after fees. Monthly payments calculate to approximately $3,055 using the standard annuity formula based on the 8% rate. But the IRR is closer to 9.67% because the actual cash received is less than the stated principal. That gap matters enormously when you're underwriting or doing portfolio analysis.
Edge cases that break straightforward calculation
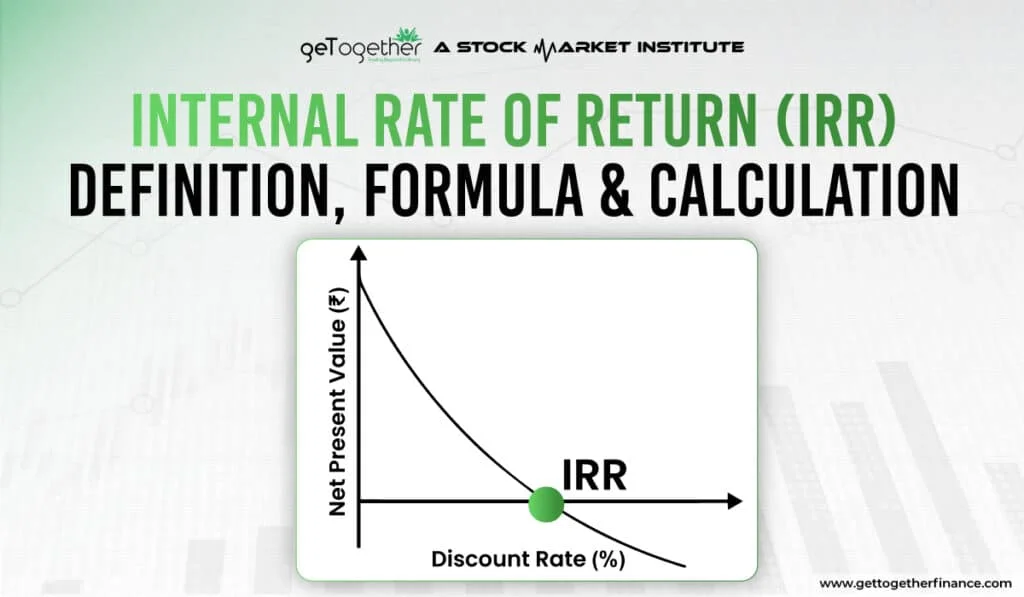
One specific scenario where I had to find a workaround involved a loan with deferred payment periods. A USDA rural development loan I was modeling had 12 months of payment deferral before regular amortization began. Standard IRR functions in Excel returned inaccurate results because the cash flow pattern had a large gap. The solution was to explicitly model each month as a separate cash flow entry rather than trying to compress the structure. It took longer to set up but produced correct numbers every time. Another issue shows up with negative IRR values. When a loan has severe prepayment penalties or balloon structures that reverse cash flow direction mid-term, the solver can produce multiple valid rates. This is called the multiple roots problem, and it's not rare in commercial lending. I always plot the NPV function across a range of discount rates before declaring a solution. If the curve crosses zero more than once, you have to figure out which root actually makes economic sense for the scenario.
Get the Full Details
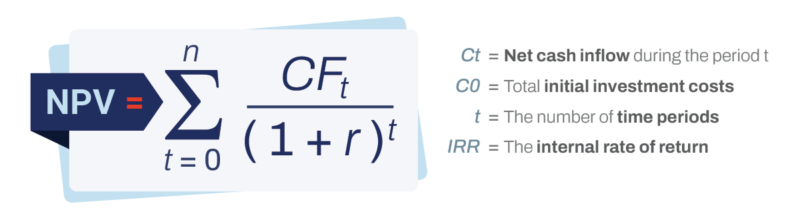
Tools and implementation details
For quick calculations, Excel's XIRR function handles irregular cash flows reasonably well. The trick is getting the dates right. XIRR requires exact settlement and payment dates, not just periods. A common mistake is entering the loan origination date as the first payment date instead of the disbursement date. That shifts everything by one period and changes your result noticeably. For production work where you're processing hundreds of loans, I recommend building a small Python script using the numpy_financial library. It's fast, transparent, and you can batch process without worrying about spreadsheet precision limits. The scipy.optimize.root method gives you more control over convergence criteria when dealing with problematic cash flow patterns. If you need something downloadable or reusable, I've shared a basic template through various lending forums and GitHub repositories in the past. Search for "loan irr calculator python" and you'll find working implementations. The key is adapting them to your specific fee structure rather than using them blindly.
What the numbers don't tell you
IRR assumes all intermediate cash flows are reinvested at the same rate. That's almost never true in practice. A borrower who receives a $50,000 loan at 7% IRR isn't earning 7% on any reinvested funds. This limitation matters most when you're comparing loans across different terms or structures. An IRR comparison between a 30-year mortgage and a 7-year business loan is technically misleading because the reinvestment assumption doesn't hold for either party equally. The modified internal rate of return addresses some of this but introduces its own complications, particularly around choosing the correct reinvestment rate. For most lending decisions, I stick with plain IRR and note the limitation in documentation rather than switching methods and creating new confusion. Pretty much any loan product can be analyzed with IRR if you map the cash flows accurately. The hard part isn't the formula. It's making sure you've captured every fee, every date, and every payment modification before you start calculating.