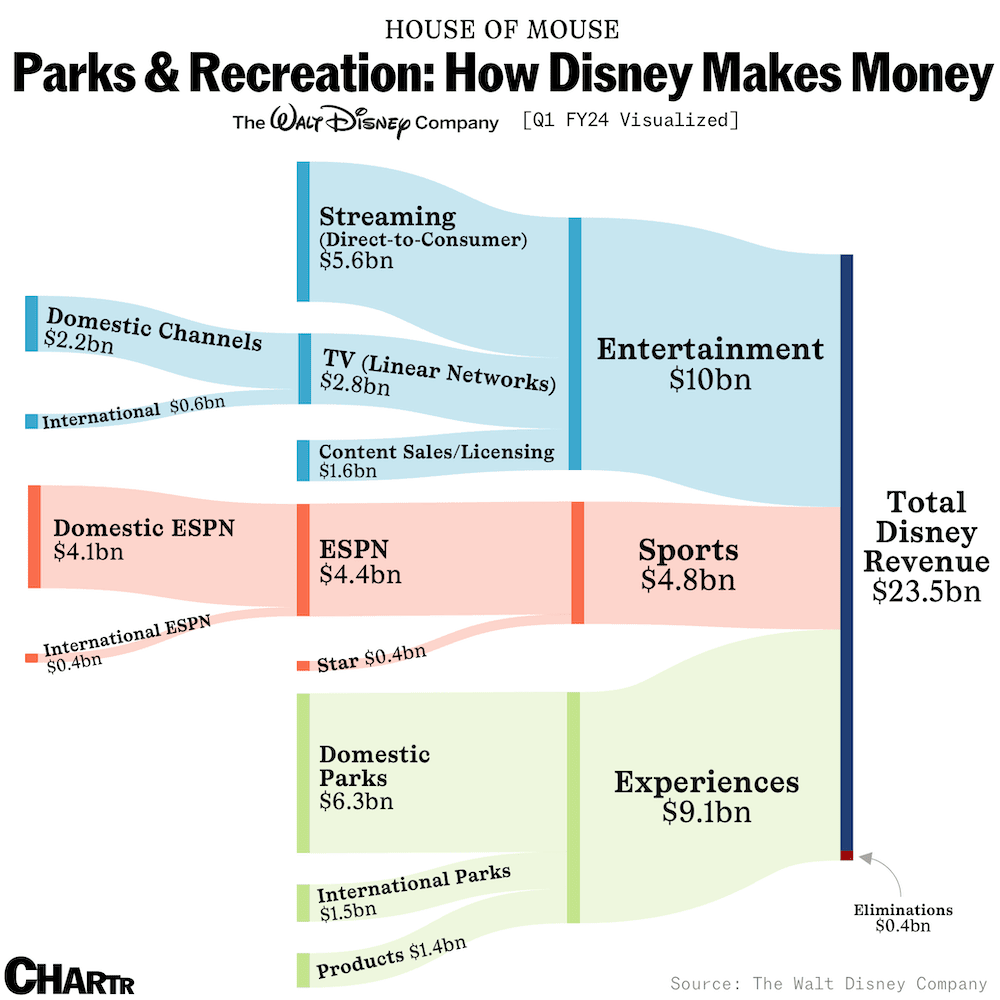
Figuring Out Disney's Daily Revenue Isn't as Simple as Dividing Annual Reports
Most people grab Disney's yearly earnings, punch it into a calculator, and call it a day. That gives you a number, sure, but it's wildly misleading. The actual daily cash flow varies depending on where you're counting from and what you're counting. Let's get the straightforward math out of the way first. Disney reports annual revenue around $88-89 billion in recent years. Divide that by 365 and you get roughly $240-245 million per day in gross revenue. Not net income. Revenue. There's a massive difference, and people who confuse the two end up with very wrong impressions of what Disney actually keeps. Net income is a different story. After operating costs, taxes, interest on their debt, and depreciation, Disney typically keeps somewhere between $10-15 billion annually. That puts daily net at closer to $27-42 million. Still depends on the year. 2020 doesn't count toward that average if you're doing the math right.
The problem with daily figures is that revenue isn't distributed evenly. Parks generate heavily during summer, holidays, and weekends. Streaming revenue is steadier but the margins are thin. Parks and experiences alone can pull in over $1 billion per month during peak seasons. A single summer Saturday at Magic Kingdom moves more money than most weekdays across the rest of the year combined. I spent time working with financial modeling for entertainment companies back when streaming was eating into traditional revenue, and one thing became clear quickly. Any analysis that treats Disney's revenue as a flat daily number is basically useless for decision-making. You need seasonal breakdowns, segment data, and you need to account for capital expenditure cycles. Disney spends billions on park expansions and content creation, and those outlays don't match the revenue rhythm at all. They build a new land, revenue jumps for a year or two, then settles. The spending happens in lumps. The cash flow pattern looks nothing like a clean chart. If you want actual daily numbers you should look at quarterly earnings calls and work backward through their reported segment results. The Disneyland Resort and Walt Disney World operations are reported separately from the parks internationally. International parks, particularly Shanghai and Tokyo even though Tokyo is a licensee, have different seasonality patterns. Shanghai peaks around Chinese New Year and national holidays. Florida peaks in summer and around Christmas. These overlapping cycles mean the "daily" average smooths over real volatility that matters if you're trying to understand the business.
There's also the matter of what counts as Disney revenue. Box office receipts are tricky because Disney only counts their share, which varies by distribution deal. Theme park tickets sold through third parties aren't all recognized immediately. Licensing deals span years. The actual cash hitting accounts on any given day looks nothing like the revenue recognized on an accrual accounting basis. I ran into this exact problem when building a model for a client who wanted to compare Disney's daily cash position against other media companies. We pulled straight from revenue figures and got numbers that made no sense compared to their actual cash reserves. The workaround was switching to free cash flow calculations using their operating cash flow minus capital expenditures, pulled directly from their cash flow statements rather than their income statements. That approach took longer to set up but actually reflected what was moving through the company day to day. It cut the research time from about three days down to roughly six hours once we had the templates built. One thing beginners consistently miss is that Disney's debt load affects their daily financial reality more than most people realize. They carry tens of billions in debt, and debt service payments happen on schedules that don't align with revenue seasons. A park might be generating peak cash in July while they're simultaneously making large principal payments. Net cash position on any single day is a snapshot that depends heavily on when those payments hit.
Get the Full Details
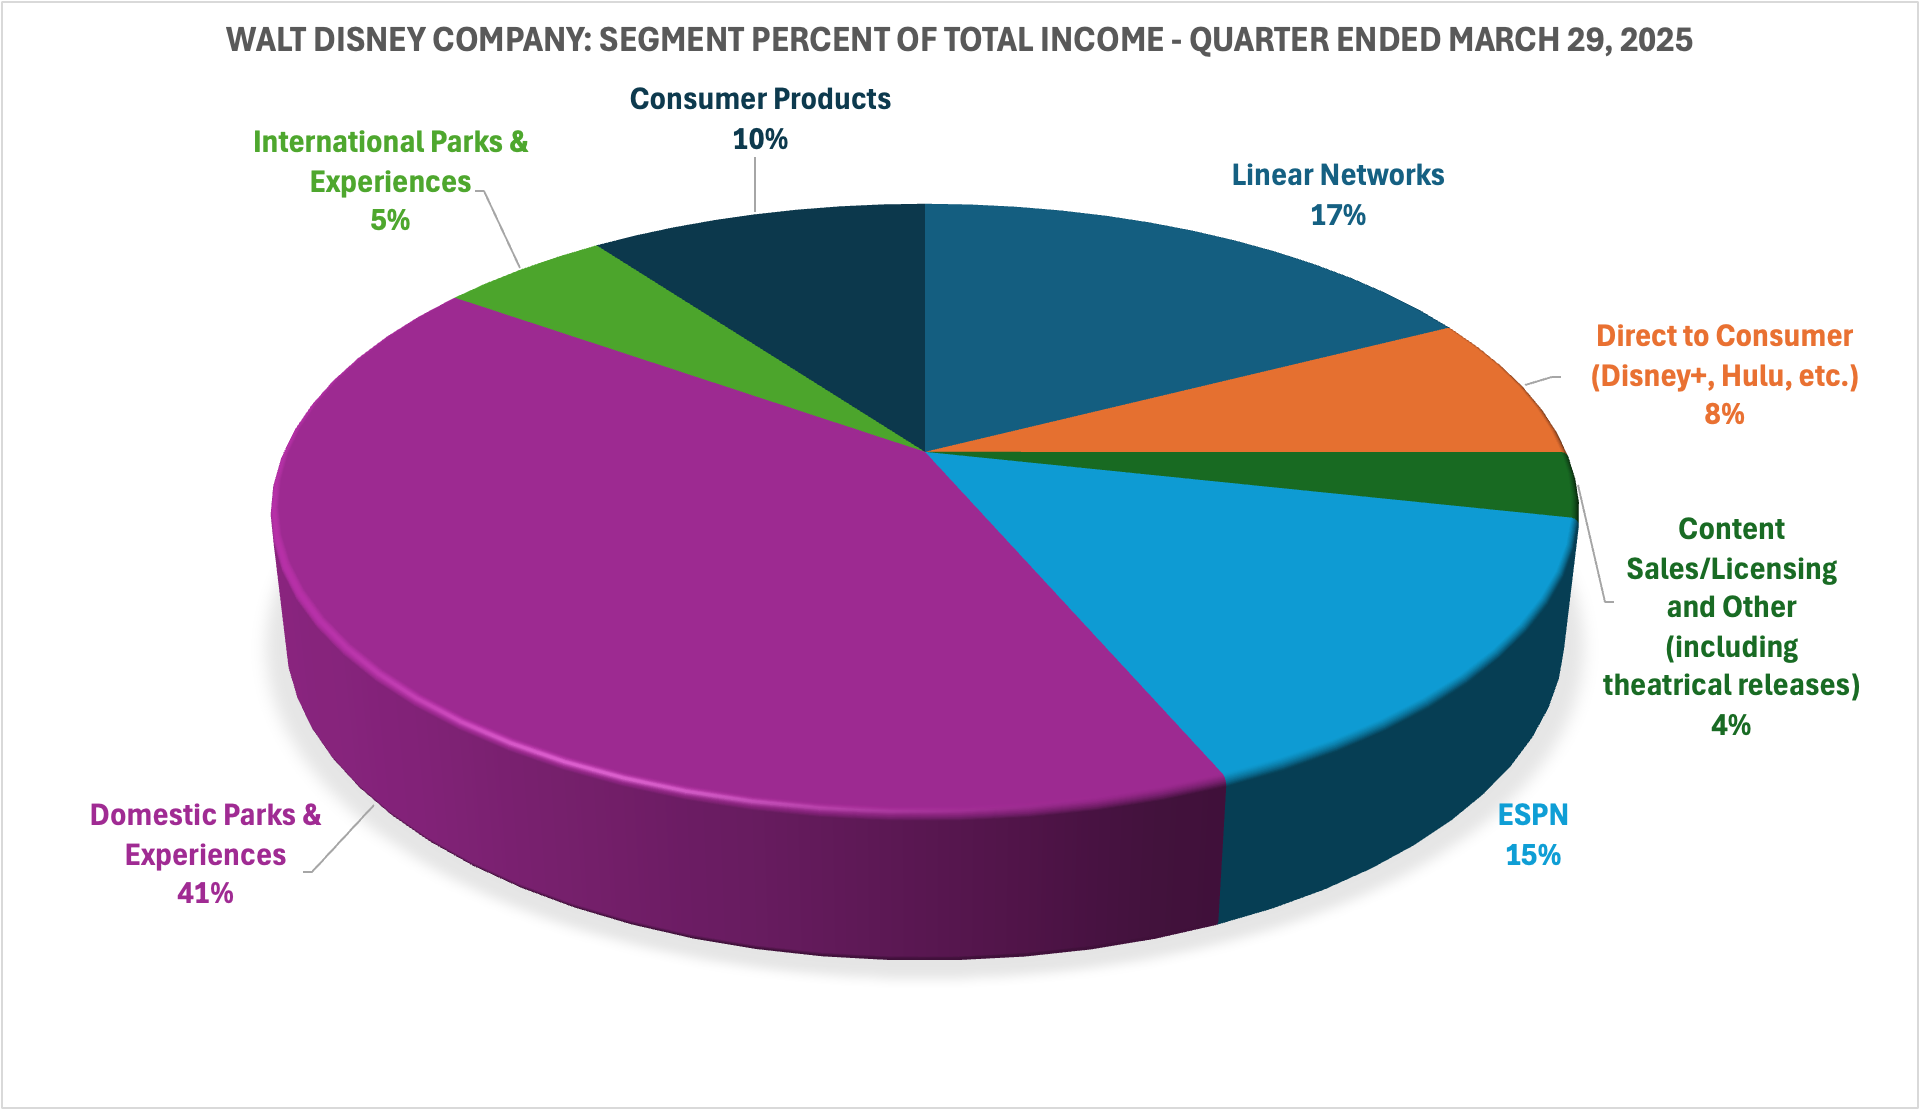
The streaming segment deserves its own attention here. Disney+ brought in roughly $22 billion annually at recent subscriber levels, but the cost of content and customer acquisition eats most of that. Daily revenue from streaming looks solid on the surface, but the profit contribution per subscriber is somewhere in the range of a few dollars per month at best. It's volume business, not margin business, and that distinction matters when you're thinking about daily generation. For anyone actually trying to track this, the most reliable source is Disney's investor relations page. Quarterly reports break down performance by segment. You'll see exactly how much parks contributed, how much streaming brought in, and what ESPN and broadcast networks are worth. The annual report gives you the full picture but it's backward-looking. Quarterly updates are more current. There's no public tool that gives you real-time daily figures, and any site claiming to show that is either estimating or pulling from incomplete data. The reality is that Disney generates somewhere between $240-250 million in daily revenue at the gross level and probably $27-42 million in daily net income based on recent annual results. But those averages hide the structural quirks of the business. Revenue concentration, debt timing, seasonal park patterns, and the streaming margin problem all mean any single daily number is an abstraction at best. If you need precision, you drill into the segments and look at the cash flow statements, not just the top-line revenue figures.