Understanding Loan Apps in Brazil
Most people I talk to about lending apps in Brazil have one question: how do you know which ones are actually safe? The market has exploded over the last few years, and with that growth comes a mix of licensed institutions, gray-area operators, and outright scams. I've spent enough time looking at this space to tell you that the difference between a legitimate app and a predatory one usually shows up in three places: the fine print, the upfront fees, and whether the lender is registered with a real regulatory body. Let's start with what actually separates a functional, regulated lending app from the noise. In Brazil, the Central Bank (Banco Central do Brasil) is the authority that licenses financial institutions. Any legitimate loan app must be tied to a bank or credit institution that holds a CB license. You can verify this by checking the platform against the list of authorized entities on the Central Bank's website. If an app can't produce a CNPJ that traces back to a licensed institution, walk away. I ran into a concrete case last year where someone sent me a screenshot of an app called "CréditoRápido Brasil" that promised approval in ten minutes. The interest rate was displayed as 8% per month, which looked reasonable until I checked the ANPM (the consumer protection registry). The company behind it had zero registration there, and their CNPJ was linked to a shell entity in a state with lax oversight. The borrower had already paid a "processing fee" of R$150 before realizing something was off. The money was gone. This is not an unusual pattern.
One detail that trips most people up: some apps use affiliate structures where they partner with licensed lenders but don't disclose it upfront. The app itself may not be licensed, but the money comes from a licensed bank. This isn't automatically fraudulent, but you need to know who is actually lending to you. Ask for the contract name and the lender's CNPJ before you click anything. If the app refuses or gives you a vague answer, that's your warning sign.
How to Evaluate a Loan App Before Downloading
Start with the regulatory check. Use the Central Bank's database to search for the institution's name or CNPJ. The lookup takes about thirty seconds and tells you whether the entity is authorized to offer credit. After that, look at the APR. Brazil has strict usury laws, but the rules around what counts as APR in app-based lending are still being refined. Most legitimate apps will show you the CET (Custo Efetivo Total), which includes all fees, taxes, and interest. If an app only displays the nominal interest rate and buries the CET in a PDF three screens deep, that's a red flag. The CET is what matters because it's the real cost of borrowing. Check the app store reviews, but read past the five-star praise. Look for patterns in the one-star reviews. Are people complaining about hidden fees? Harassment from collection agents? Apps disappearing after you sign up? These are the signals. I once spent an afternoon going through 200 reviews on a credit app and found that every single negative review mentioned the same issue: the app would approve you, disburse a small amount, and then hit you with administrative fees that made the effective APR exceed 400% per year. The app kept getting rebranded under different names, which is a common tactic in this space.
Get the Full Details
Common Pitfalls and What Beginners Miss
Most people focus on the interest rate and ignore the penalties. In Brazil, late payment fees on loan apps can stack quickly. Some apps charge a fixed late fee plus a daily penalty that compounds. I worked with a client who took a R$500 loan at what looked like a reasonable rate. She was two days late on a payment, and the total owed had jumped to R$720 because of penalty stacking. The app's terms allowed this, and because she'd scrolled past the fine print, she didn't catch it. The lesson: read the penalty section before you accept the offer, not after you miss a payment. Another thing people miss is the automatic renewal clause. Some loan apps include terms that automatically renew your loan at higher rates unless you actively cancel within a narrow window. I've seen this in multiple apps targeting first-time borrowers. The cancellation window might be three days, and if you miss it, you're locked into a new loan with worse terms. This is legal in many cases because it's buried in the contract, but it's exactly the kind of trap that turns a manageable loan into a debt spiral. There's also the issue of data access. Many Brazilian loan apps require access to your contacts, photos, and location as a condition for approval. This is partly for identity verification and partly for collection purposes, but it crosses into invasive territory. If an app asks for more permissions than necessary, push back. A legitimate lender needs your CPF and income verification, not your entire contact list. I encountered an app that synced to WhatsApp and started messaging your contacts when you fell behind. The borrower felt humiliated and panicked into paying something he couldn't afford. That's not lending; that's coercion wrapped in an app interface.
What Legitimate Apps Actually Look Like
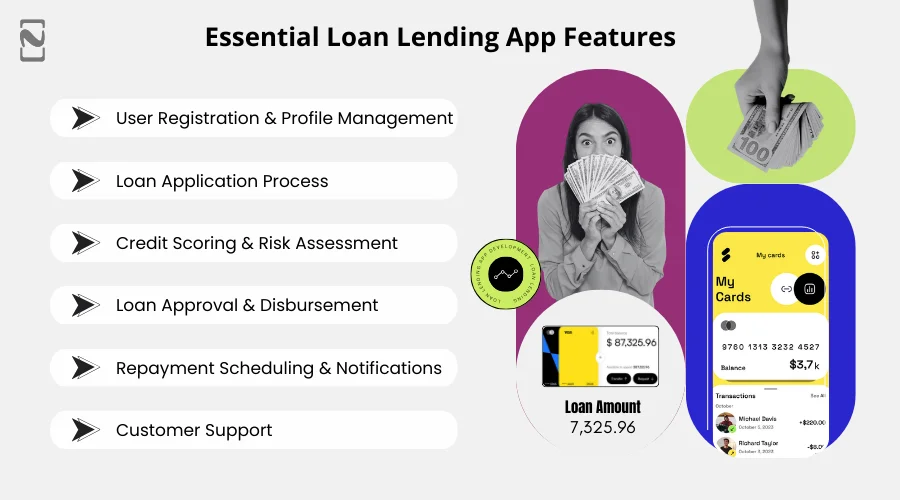
A well-regulated loan app in Brazil will display the CET clearly, show you the full repayment schedule upfront, and allow you to download the contract before you commit. It will not pressure you to decide within minutes. It will not require unusual permissions. It will not threaten contact with your social circle over missed payments. Most importantly, it will give you a cooling-off period where you can cancel without penalty within a reasonable timeframe. I've found that apps backed by major banks or established fintechs tend to follow these patterns consistently. They're not perfect, and their rates aren't always the lowest, but they operate within the regulatory framework and will answer your questions about fees and penalties. When I call customer support at one of these apps and ask for clarification on the CET, I get a straight answer. When I call the support line at a questionable app, I get transferred, ignored, or told to check the FAQ.
Alternatives to Consider
If loan apps feel too risky, traditional credit unions (cooperativas de crédito) in Brazil often offer better rates and far more transparent terms. Institutions like Sicredi, Sicoob, and Bancoob are member-owned and operate under strict cooperative regulations. The application process is slower, and you typically need to visit a branch or complete more documentation, but you avoid the pitfalls that come with unregulated apps. For smaller, short-term needs, some people turn to personal loans from their existing bank relationship. If you have a checking account with a bank that offers overdraft or personal credit lines, those products are usually cheaper and more transparent than standalone loan apps. There's also the option of peer-to-peer lending platforms, which are regulated differently but still require Central Bank authorization. These platforms connect borrowers directly with individual lenders, which can result in better rates for qualified borrowers. The trade-off is that approval criteria can be stricter, and the funding timeline depends on whether an investor is willing to take your loan.
Final Practical Notes
The easiest way to protect yourself is to slow down. Loan apps are designed to make you feel like you need to act immediately. That pressure is intentional. Take the time to verify the lender, read the contract, and compare the CET across at least two platforms before committing. If an app makes you feel rushed, that's your signal to step back and reassess. The right lender will wait.