Reading Price Multiples Without Losing Your Mind
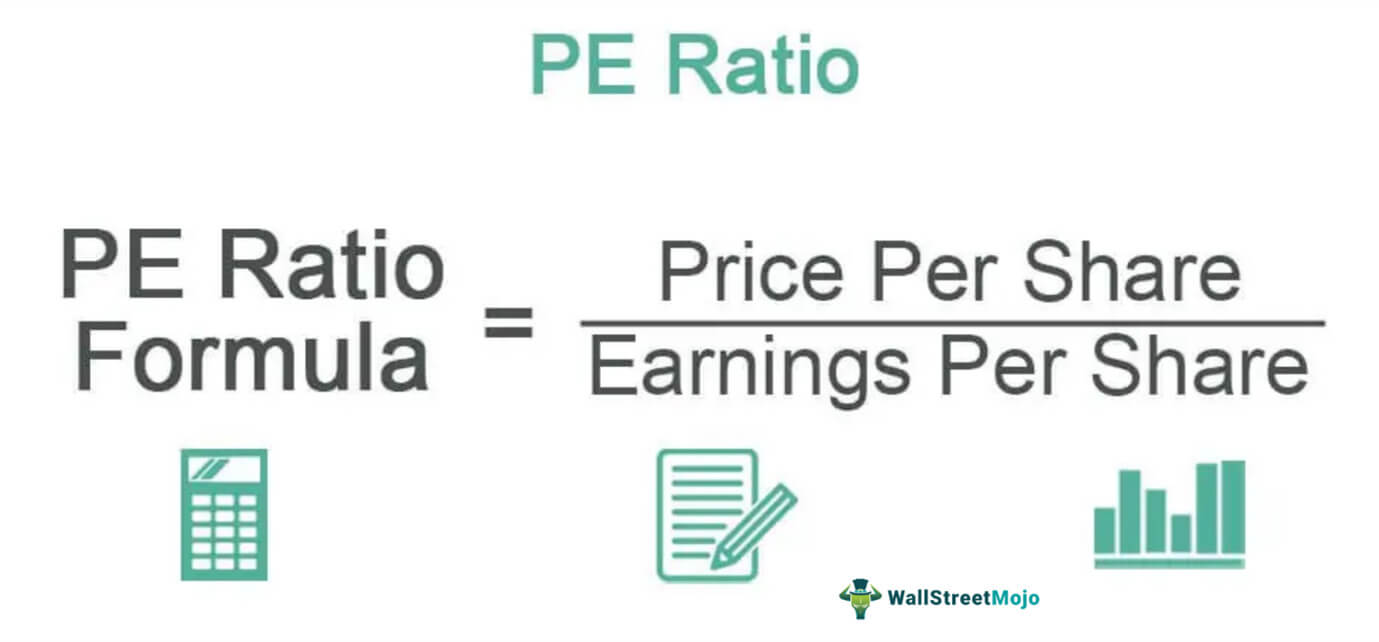
I spent years staring at spreadsheets full of PE and CE numbers before I stopped treating them like magic wands and started treating them like what they actually are: rough directional signals with real blind spots. The ratios themselves are trivial to calculate. The hard part is knowing when they lie to you and why they lie. Price-to-earnings ratio divides current share price by earnings per share over a defined period, usually the trailing twelve months. Price-to-cash flow divides share price by free cash flow per share, though some platforms use operating cash flow instead. Both give you a sense of how much the market is pricing in relative to profitability, but they measure fundamentally different things and behave differently across sectors. I once screened a mid-cap logistics company during a routine quarterly pass. The PE came in at 7.8, which on the surface looked like a deep value signal. I then pulled free cash flow per share and found it was barely positive after capex, hovering around $0.40 while the stock sat at $18. The CE was pushing 45, which contradicted the cheap PE narrative entirely. That company was eating working capital and delaying supplier payments to keep reported earnings looking decent. The PE was clean. The cash flow told the story. I walked away.
This mismatch between earnings and cash flow is not rare. It is one of the most common failure modes I see retail investors hit. Earnings can be manipulated through accounting adjustments, revenue recognition timing, and non-cash charges. Cash flow is harder to fake, but it is still imperfect depending on how your data source defines it.
How To Actually Use These Ratios
Start by pulling both numbers for any company you are considering. Do not rely on a single platform because their cash flow definitions vary enough to shift your conclusion. Yahoo Finance uses free cash flow as operating cash flow minus capital expenditures. Google Finance sometimes reports cash flow from operations without subtracting capex, which inflates the attractiveness of capital-intensive businesses. Always verify which definition your screen is using before making a decision. When PE is low and CE is also low relative to peers, that is your baseline value signal. When PE is low but CE is high, dig into whether earnings are being propped up by one-time gains, tax benefits, or aggressive depreciation schedules. When PE is high but CE is reasonable, the business may be reinvesting heavily, which is fine in growth contexts but dangerous if growth has stalled. I apply a simple cross-check that usually cuts screening time from several hours down to about twenty minutes. First, pull PE and CE for a broad sector ETF to get the median. Second, compare individual stocks against that median rather than against an arbitrary threshold like PE under fifteen. A PE of twelve might be expensive in capital-intensive manufacturing and cheap in software. Sector context matters more than any absolute number.
Get the Full Details

Third, I look at the gap between PE and CE as a health indicator. If PE is 14 and CE is 28, the company's earnings are roughly half its cash flow, which typically points to high non-cash charges like depreciation or stock-based compensation. In some industries, that is normal. In others, it is a red flag for declining reinvestment or accounting smoothing.
Common Pitfalls That Waste Time
The biggest mistake I see people make is comparing PE across unrelated industries. Tech stocks routinely trade at higher multiples than utilities because earnings growth expectations differ dramatically. A utility with a PE of 16 and a CE of 12 is not expensive. A biotech firm with the same numbers is deeply overvalued by most historical standards. Sector-relative comparison should be your default, not sector-agnostic thresholds. Another frequent error is using trailing twelve-month earnings without adjusting for cycle. Auto and commodity companies swing wildly through economic cycles, so a low PE at the peak of a commodity cycle often precedes a sharp earnings decline. I adjust my screens by checking whether the trailing earnings represent a trough, trough, or mid-cycle point. A quick chart of earnings over the past five quarters tells you this in seconds. Cash flow per share also has a quirk that catches people out. Share count changes distort the ratio. If a company buys back shares aggressively, CE drops even if total free cash flow stays flat. The ratio improves mathematically, but the underlying business did not get cheaper. I always check share count trends alongside the ratio to separate genuine valuation improvement from denominator distortion.
Where These Ratios Fail Completely
PE is useless for companies with negative earnings. Some screens flag these as infinitely negative or simply exclude them, but that exclusion hides opportunity. A company posting a -$2 EPS loss with a stock price of $10 looks terrible on PE but may be trading at a reasonable CE of 8 if its cash flow is positive. Conversely, it may be a value trap where the business is bleeding and the cash flow will vanish next quarter. You have to look further. The ratio alone cannot tell you which case applies. CE fails for asset-heavy businesses with massive recurring capital expenditures. Mining, airlines, and telecommunications all report strong operating cash flow but commit it almost entirely to maintaining operations. Their free cash flow is artificially depressed, making CE look expensive even when the business is stable. I switch to price-to-book or enterprise value-to-EBITDA for those sectors instead of relying on CE alone. Both ratios ignore debt. A company with a PE of 10 and a CE of 15 might carry enough debt to make the equity purchase risky. I cross-reference the balance sheet before acting on any multiple. A quick debt-to-equity check takes thirty seconds and prevents half the bad decisions I have seen made by people who only looked at earnings multiples.
Practical Workflow
Here is the routine I actually follow when building a watchlist, and it takes roughly fifteen minutes per batch: Pull PE, CE, and free cash flow per share from a platform that lets you export the data. Verify the cash flow definition matches free cash flow, not operating cash flow. Calculate the PE-to-CE ratio for each name and flag anything above 2.0 as needing deeper review. Cross-reference with debt-to-equity and five-quarter earnings trend. Drop any name where earnings volatility exceeds fifty percent year over year unless you have a clear catalyst thesis. Keep the remaining names in a spreadsheet with the raw numbers visible. Revisit quarterly. This is not a strategy that generates consistent alpha on its own. It filters out garbage and surfaces companies worth deeper research. The actual work happens after the screen, in reading filings and understanding the business. The ratios just help you decide where to point the flashlight.
I have stuck with this approach for over a decade because it is repeatable, transparent, and easy to audit. When I get it wrong, I can see exactly which number misled me. That visibility matters more than any sophisticated model that operates as a black box.