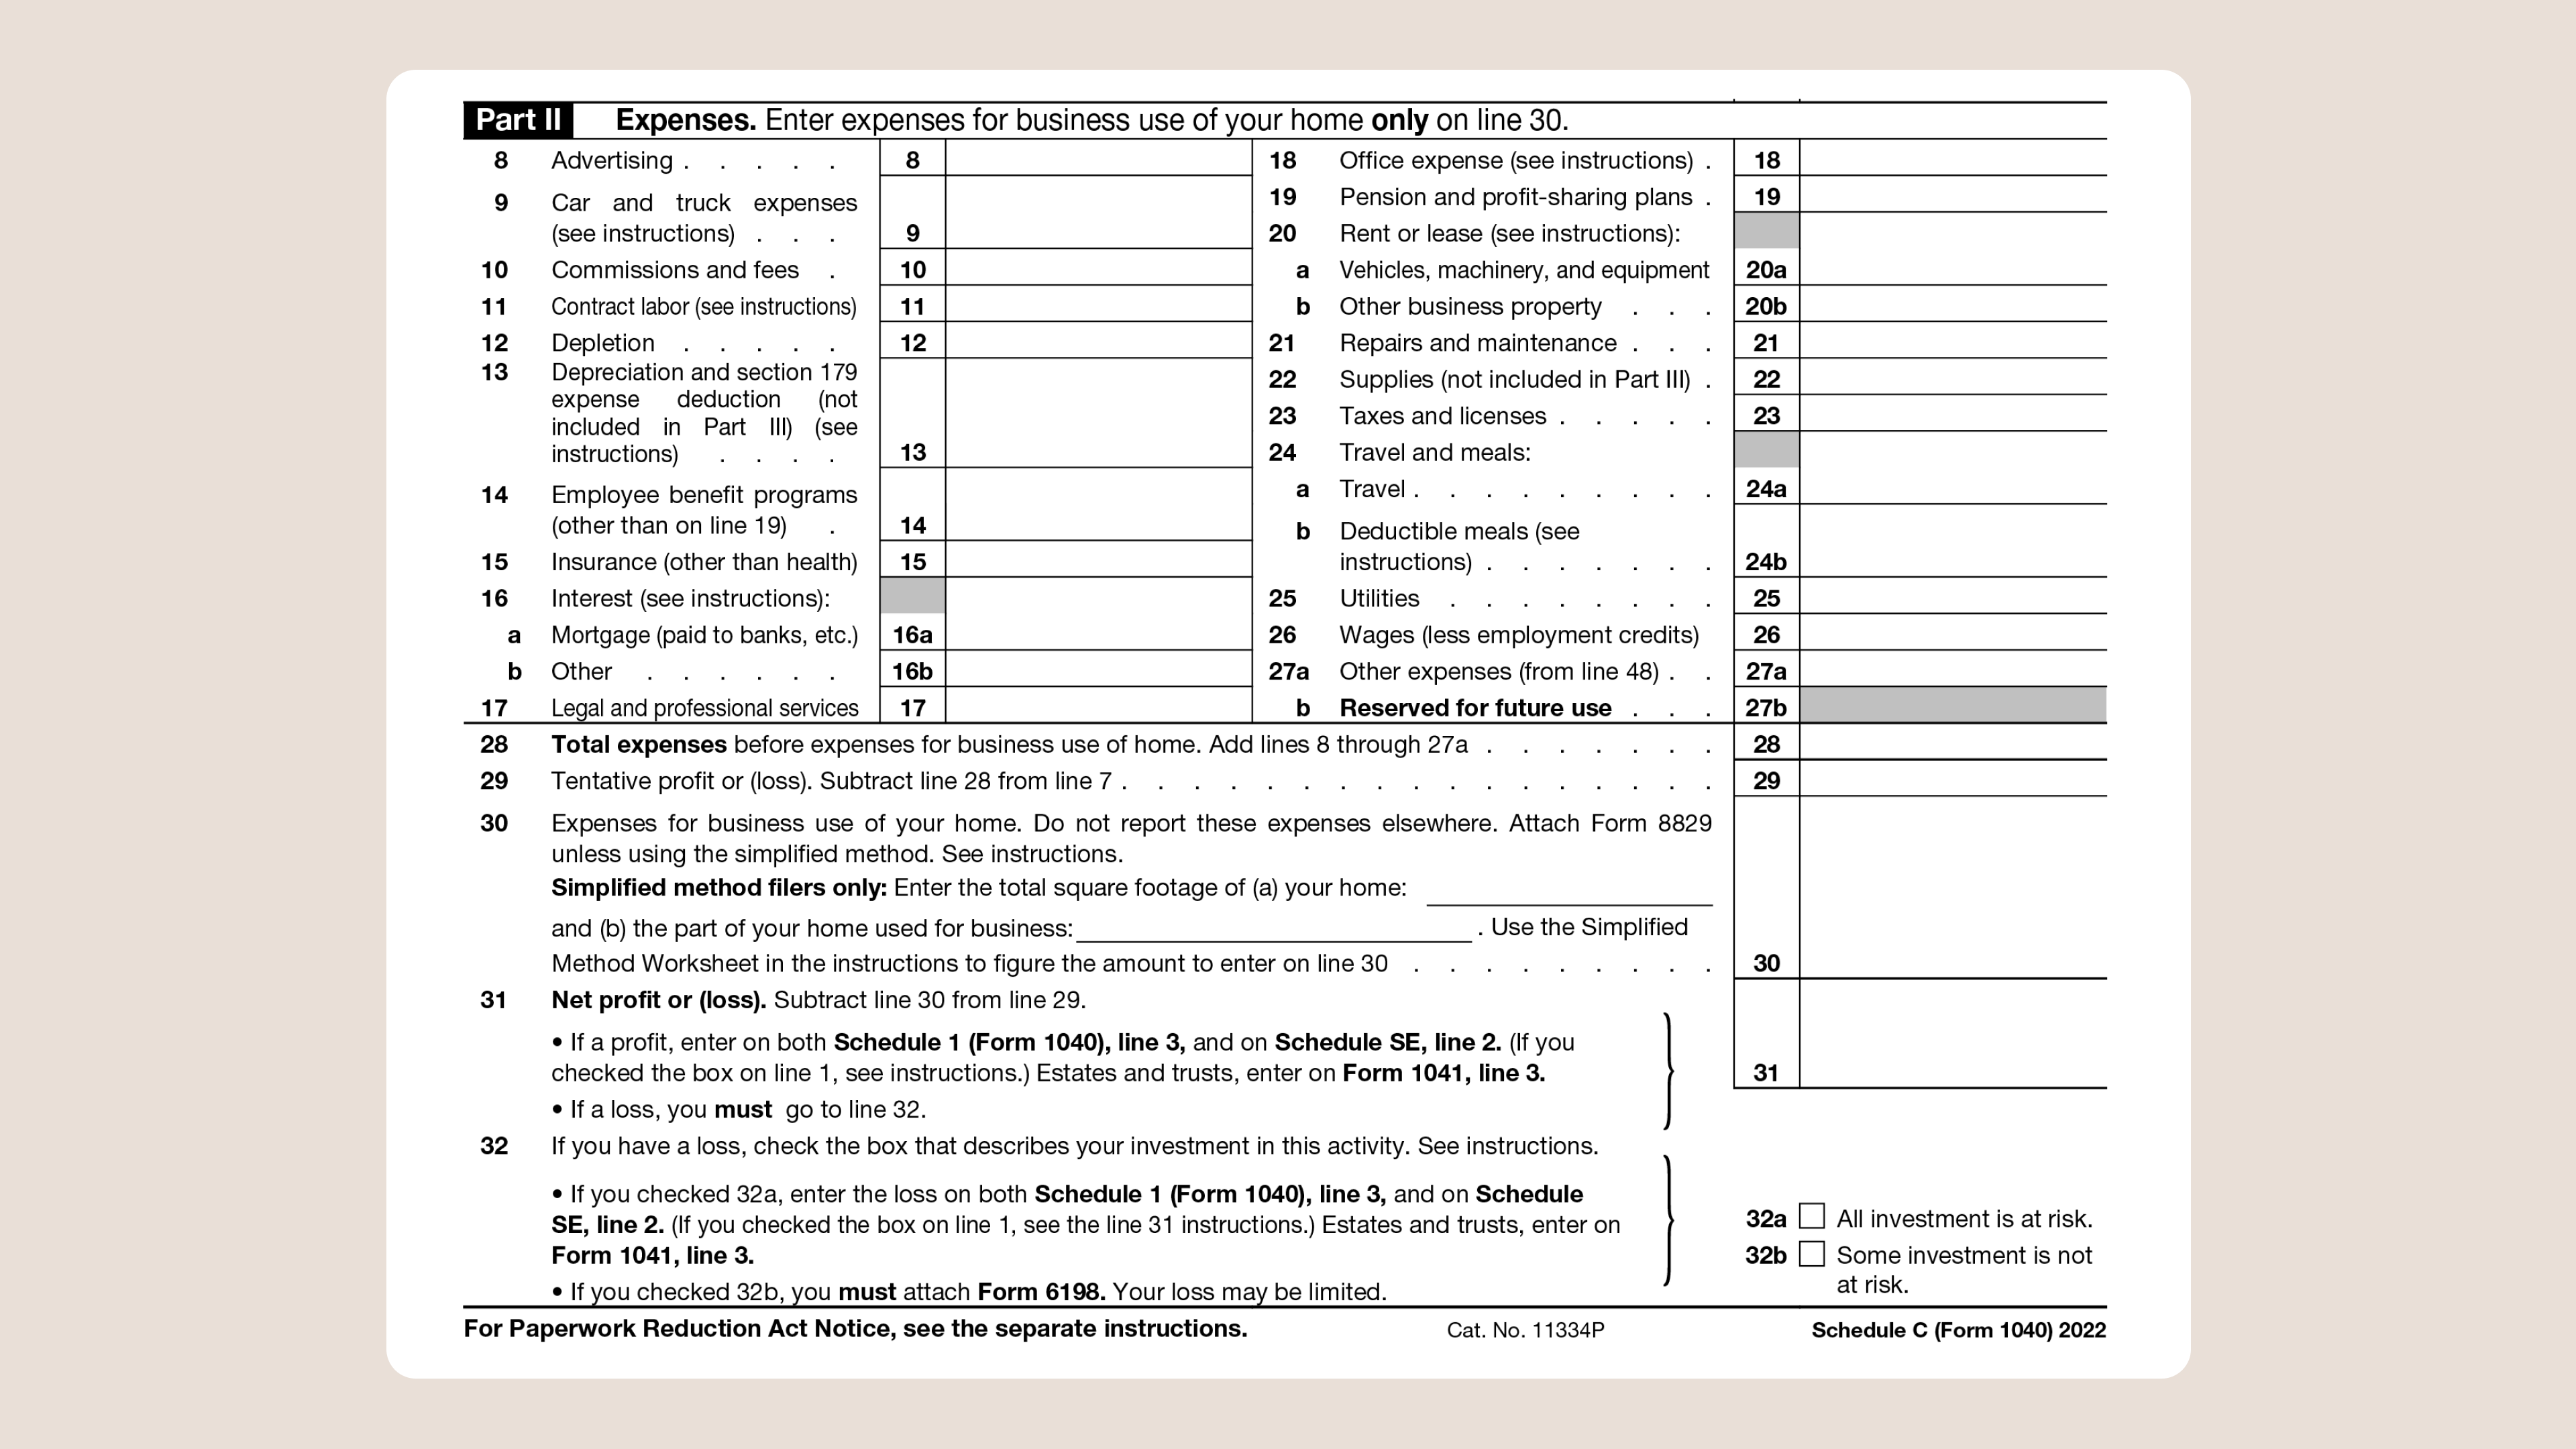
What Is Misc Exp Other on Schedule C?
Schedule C line 27 is labeled "Other expenses." The instructions tell you to list the total amount of all business expenses not already captured on lines 8 through 26. You then have to itemize each individual expense on a separate statement attached to your return, showing the name and dollar amount of each one. Most people who see this line are sole proprietors, single-member LLCs taxed as disregarded entities, or freelancers filing a one-person business return. The form itself does not give you a free pass to dump a lump sum into line 27 without documentation. The IRS expects a supporting schedule, and if you are audited, they will ask for it. The actual work begins before you ever reach line 27. You have to determine whether an expense belongs on one of the numbered lines first. Line 9 covers car and truck expenses, line 10 is office expense, line 11 is postage, line 12 is meals, and so on. If an expense fits a numbered line, it goes there, not on the "other" line. That means software subscriptions belong on line 16 (computer and software expense), advertising belongs on line 8, and contract labor belongs on line 11 or 12 depending on classification. The misc other line is truly the catchall, and the IRS treats catchalls with more scrutiny than properly categorized items. I learned that the hard way in 2018 when I put a $340 expense for a Zoom Pro subscription into line 27 instead of line 16. The exam letter asked me to move it and explain why it was miscategorized, which added three weeks and a bunch of unnecessary back-and-forth. Moving it resolved the issue, but it was still an avoidable delay. Here is the practical workflow I use. At the end of each month, I pull my bank and credit card statements, export them to a CSV, and sort by merchant. I tag each transaction with the correct Schedule C line number at the time of entry. By the time April arrives, I already know which expenses are sitting on line 27 and which are already placed elsewhere. If a category appears multiple times throughout the year, I group them and verify the total against my bookkeeping software before finalizing the attachment.
The attachment itself is where most people mess up. You need a clear, readable list. Each expense gets its own line. The format should include the vendor name, the date of purchase, the purpose of the expense, and the amount. The total on the attachment must equal the number entered on line 27 exactly. Any mismatch triggers a notice. I used to hand-write attachments, and I kept making arithmetic errors. Now I generate the attachment from my accounting software and do a manual spot-check by totaling three random transactions. That habit has saved me from at least two audit red flags in the last five years. One thing beginners consistently miss is the distinction between supplies and equipment. If you buy a $600 router for your home office, that might qualify for the de minimis safe harbor election under Treasury Regulation 1.263(a)-1(f), which lets you deduct it immediately instead of capitalizing and depreciating it. You still report it on the correct line, but the paperwork backing that decision matters. If you do not have a written election on file and the IRS questions the deduction, you will be on the defensive. I have seen people lose deductions simply because they could not produce the election document, not because the expense itself was disallowed. Another counter-intuitive point is how mixed-use expenses behave on this line. Say you buy a tablet that you use 60 percent for business and 40 percent for personal reasons. You can only deduct the business portion. The percentage has to be defensible. Screenshots, a contemporaneous log, or a calendar showing business use are all acceptable. A hand-wave estimate is not. I had a client who claimed 90 percent business use on a tablet without any documentation. The auditor reduced it to 50 percent based on typical usage patterns for that device type. The taxpayer ended up paying additional tax and interest on the difference. Had the client kept a simple monthly log, the result would have been completely different.
There is also a nuance around meal expenses that deserves attention. The 50 percent limitation still applies to most business meals, even though the temporary 100 percent deduction for restaurant meals expired after 2022. If you are deducting meals on line 24 and then rolling the remainder into line 27, you are creating confusion. Keep meals separate, keep them documented, and do not bury them in the misc other line. The IRS computer matching program flags returns where the meal deduction appears unusually low relative to other expense categories, which is a suspicious signal. For people who run a home office, the safest approach is to keep a dedicated business bank account and a separate credit card. Commingling personal and business transactions creates gaps in the audit trail that are painful to close. When I audit my own returns, I print the statement for the business card and match it against the bookkeeping report. Any transaction that appears on both the statement and the personal card gets flagged for review. This usually catches misclassified expenses within ten minutes of starting the process. If you prefer using software, most modern platforms will generate the attachment automatically. QuickBooks, FreshBooks, and Xero all produce a line 27 schedule in PDF or CSV format that matches the IRS layout. The trick is to verify the output before attaching it. I have seen software pull in a personal grocery purchase because it was charged to the same card used for business purchases. These errors are rare but costly when they happen. A ten-minute manual review eliminates the risk entirely.
Get the Full Details

Cost of goods sold deserves a mention here. If your business involves inventory, COGS goes on lines 2 and 3 of Schedule C and is completely separate from line 27. Some sole proprietors mistakenly include inventory-related costs in the other expenses section, which understates COGS and inflates misc other. The IRS prefers COGS to be reported correctly because it affects gross profit, which is a key metric in their examination algorithms. Double-check that inventory costs are not accidentally landing on line 27 before you file. Finally, if your total other expenses exceed a certain threshold relative to gross receipts, you may want to prepare a more detailed narrative explanation. There is no fixed dollar amount that triggers this, but experience shows that returns with line 27 amounts above $5,000 on a return with gross receipts under $50,000 attract disproportionate attention. In those cases, attaching a brief one-page summary explaining the nature of the expenses and referencing the supporting attachment reduces the chance of a request for additional information. It also signals to the examiner that you have organized your records properly. The bottom line is that line 27 is not a dumping ground. It is a legitimate reporting line when used correctly, but it requires discipline to keep the numbers accurate, the attachments complete, and the categorization sound. Spend the time upfront to classify every expense properly, keep the documentation tight, and do not let software defaults override your judgment. That is the only reliable way to file this without inviting an audit.


