What Card Modernization Actually Looks Like in Practice
Most payment processors don't fail because the technology is impossible. They fail because the institutions underestimate how messy it is to untangle decades of accumulated configuration. When I first looked at card modernization platforms, I expected something clean and enterprise-grade. The reality is usually a patchwork of middleware, API wrappers, and a lot of phone calls to your existing provider. Platforms like acgcardservices.com position themselves as all-in-one solutions for organizations looking to move away from aging card processing infrastructure. The core promise is straightforward: replace a legacy card management system with something that can handle modern payment flows, new card schemes, and the compliance requirements that come with them. In theory, this sounds great. In practice, there are steps and gotchas that nobody puts in a brochure.
Unraveling The Mystery Of Acgcardservices Com Your Ultimate Card Modernization Solution
What the Platform Actually Does
Card modernization platforms typically cover a few core areas. First is card lifecycle management — issuing, activating, reissuing, and deactivating physical and virtual cards. Second is processing infrastructure migration — moving your transaction routing from an old acquirer or processor to a new one with minimal disruption. Third is compliance and schema support — handling EMV, tokenization, PCI DSS requirements, and the various card network rules that change constantly. Fourth is integration layer — providing APIs that your existing banking or fintech stack can talk to without a complete rebuild. Acgcard services, as their positioning suggests, bundles these functions into a single pane of glass. That is their value proposition. The question is always whether that single pane actually reduces complexity or just hides it somewhere behind a dashboard.
How I Approach a Migration Like This
I have walked through several of these migrations, and they almost always follow the same skeleton, even if every project has its own complications. Here is the process I use, not as a rigid blueprint but as a practical outline. The first step is always a full audit of your current card environment. I need to know every card product you issue, every processing relationship you have, every vendor who touches card data, and every custom integration that exists. This sounds obvious. Most teams skip it. I have seen migrations stall for months because someone had a custom card blocking feature built into a legacy system that nobody documented. Next comes the data mapping exercise. Every card account in your old system needs a corresponding record in the new one. Card numbers, expiration dates, PIN blocks, reward points, pending transactions — all of it has to move. This is where the work gets tedious and where mistakes happen. I recommend building a checksum validation step that cross-references every migrated record against the source data before you touch production.
Get the Full Details
Then there is the processor and network migration. If you are changing acquirers or card networks as part of the modernization, you need to coordinate testing windows with every party involved. Getting a test card approved on Visa or Mastercard's sandbox takes longer than most people expect, and scheduling is often a bottleneck. Plan for eight to twelve weeks here if you are doing a full processor switch. The integration phase is where your internal engineering team comes in. You will be working with APIs, webhooks, and sometimes batch file exchanges depending on what your bank partners require. I always recommend starting with the lowest-risk integration first — typically something like card status lookup — before tackling transaction processing.
A Real Problem I Hit and How I Worked Around It
During one migration involving a regional credit union, we discovered that their legacy system had a custom field for member card tier designation that didn't exist in any standard card schema. It was stored in a non-standard database column with no documentation. When we tried to map it to the new platform's tier system, three thousand accounts fell through because the field was empty for members who had been there before the digital migration in the late 2000s. The workaround was tedious but straightforward. I pulled the original paper application files from offsite storage for affected members, cross-referenced them against the card tier rules from that era, and manually populated the missing data before the final migration run. It took about three weeks of part-time work. I now include a requirement for a manual data quality review as a mandatory step before any migration plan goes forward.
What Most People Miss About These Platforms
One counter-intuitive thing about card modernization platforms is that the software itself is rarely the hard part. The hard part is everything around it — your bank relationships, your compliance obligations, your internal change management. A platform like Acgcard Services might handle the technical switch beautifully, but if your acquiring bank hasn't been properly notified and aligned, transactions can decline during the transition window without any obvious technical error. Another thing beginners overlook is tokenization state. If you use tokenized cards in mobile wallets or recurring billing setups, those tokens are bound to specific processing paths. Moving the backend without properly remapping or reissuing tokens means some of your customers will suddenly find their Apple Pay or Google Pay cards stopped working. I always run a token inventory audit before touching anything.
The Downsides and Where It Doesn't Work
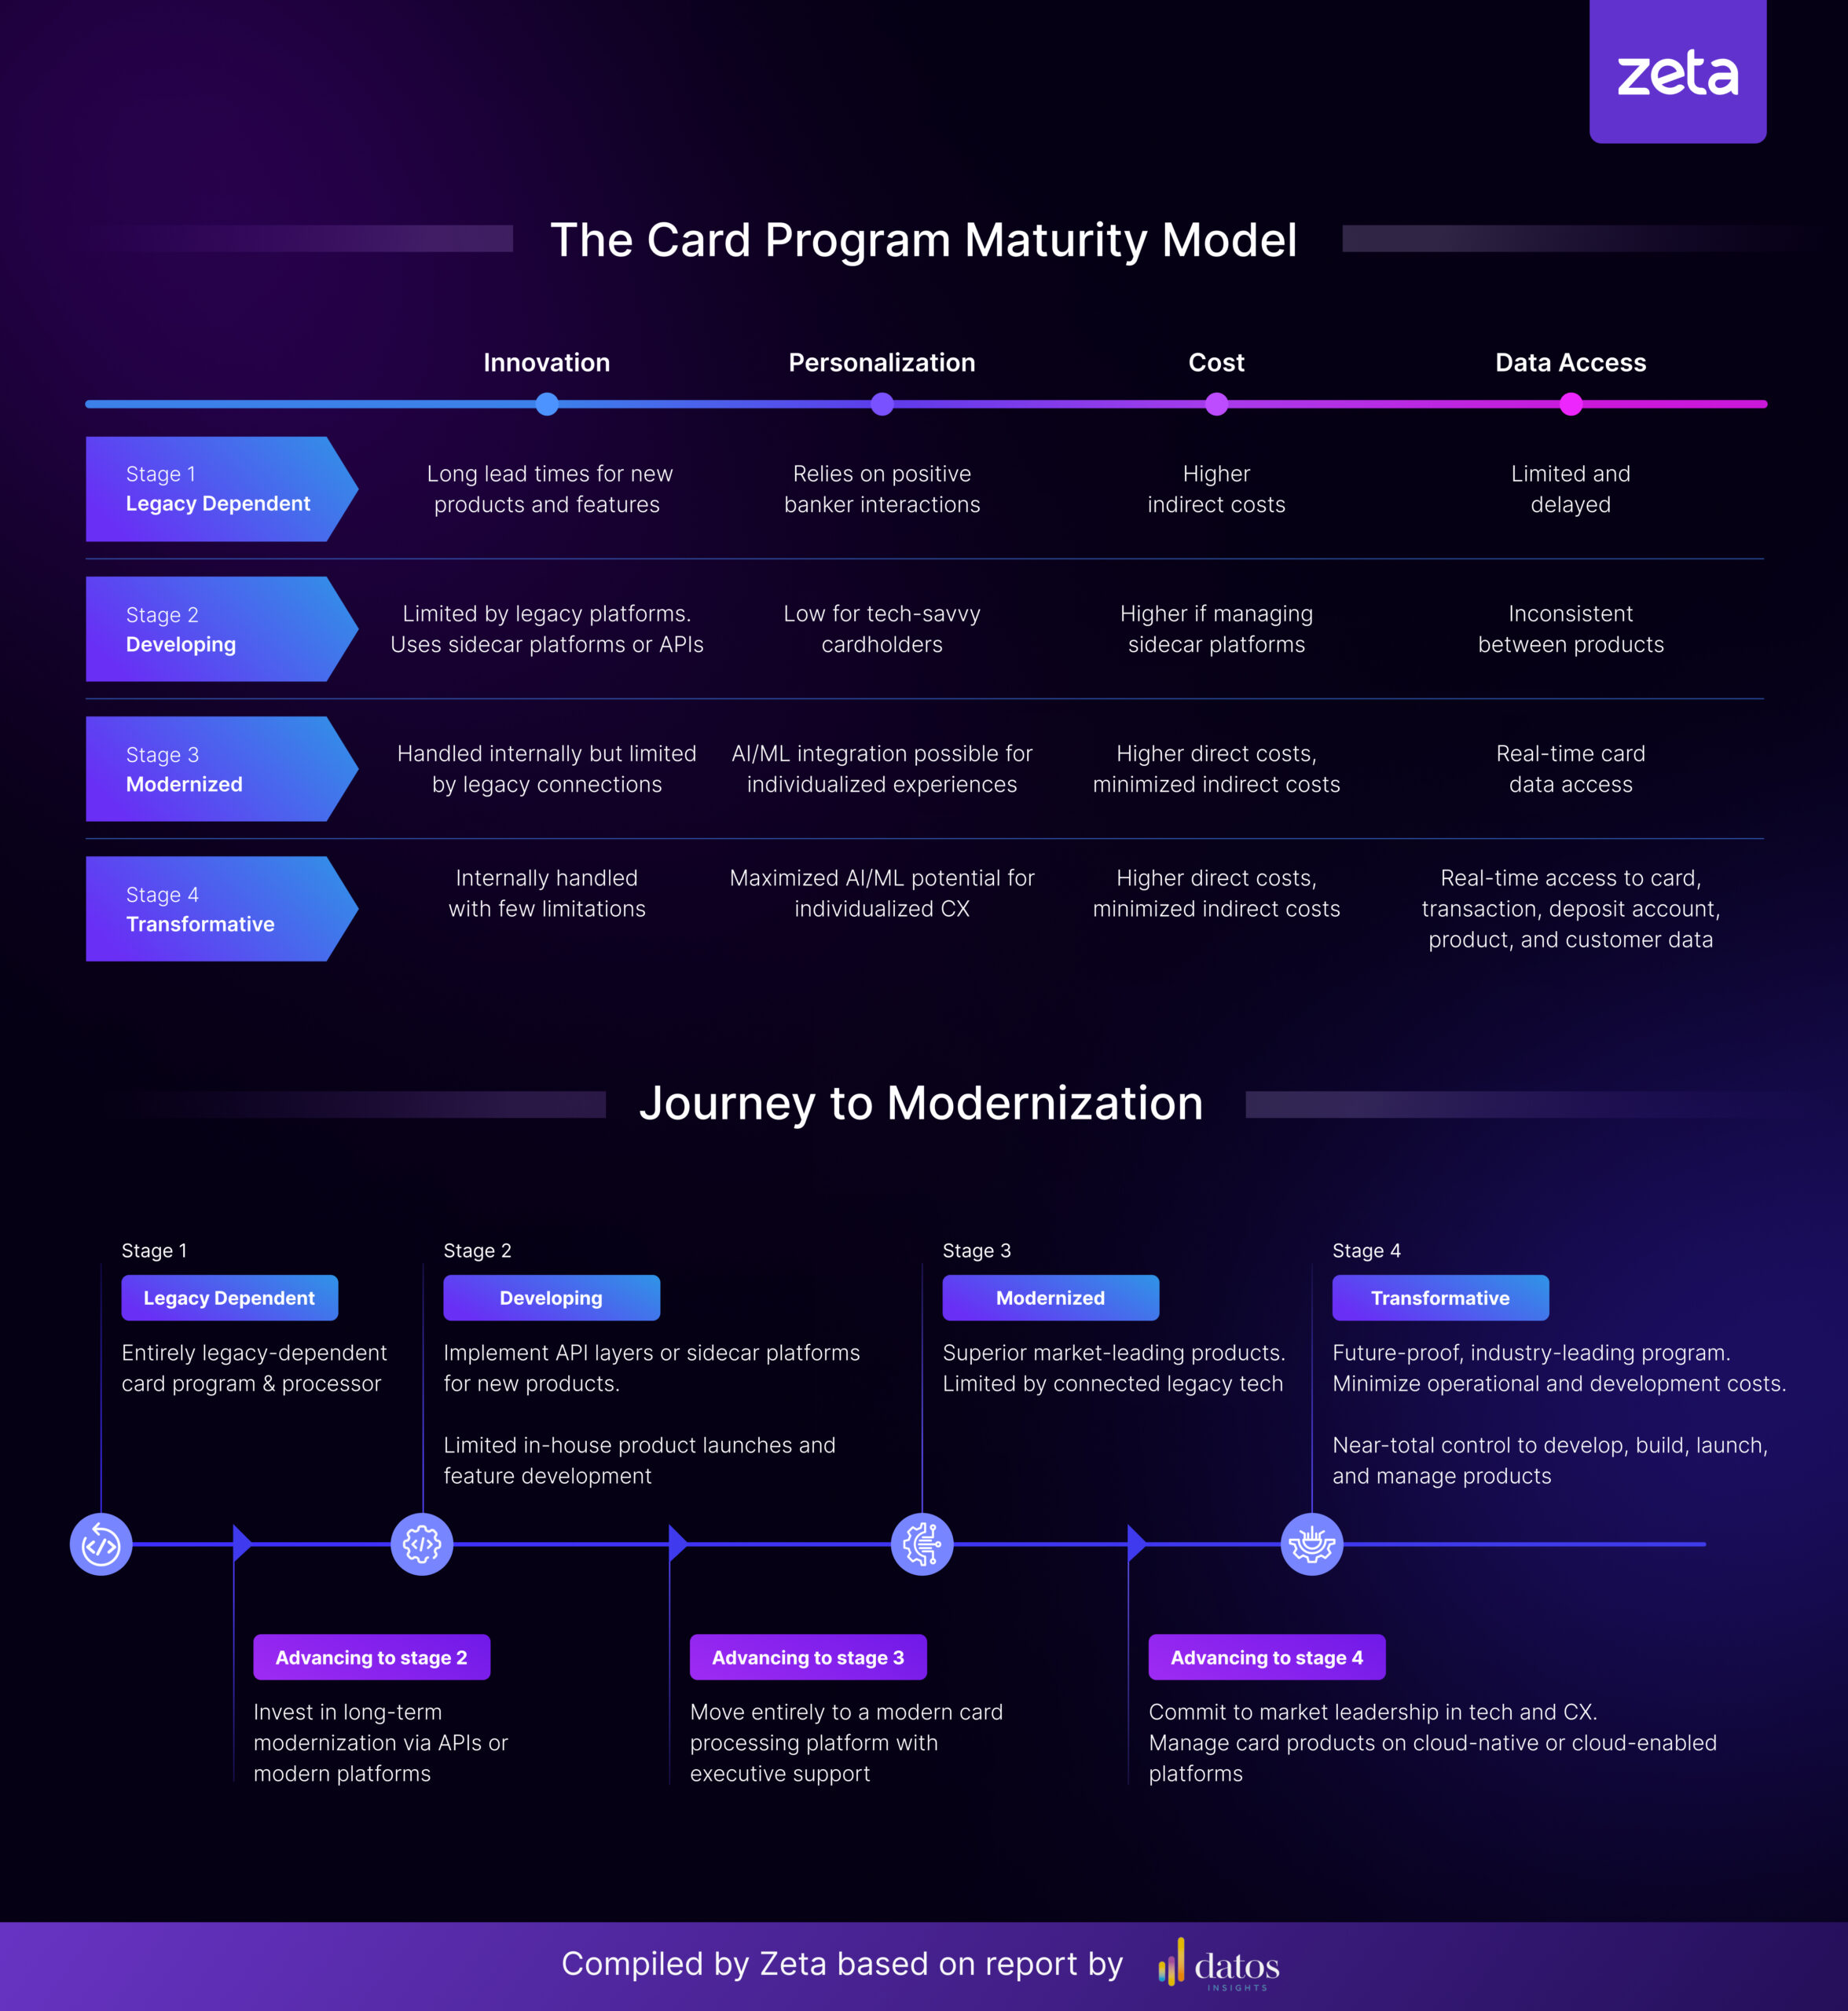
These platforms are not a magic bullet. There are scenarios where they simply cannot help, and you should know about them before signing a contract. Highly customized legacy systems are the biggest friction point. If your current card platform has ten years of custom code and special handling logic, the modernization platform may not be able to replicate it without extensive custom development on their end — and that custom development is expensive and slow. In those cases, a phased approach where you migrate product by product rather than all at once is usually better. Small institutions with simple card portfolios may find that the cost and effort of a full modernization platform outweighs the benefits. If you issue fewer than a few thousand cards and your processing is relatively straightforward, the ROI on a platform like this becomes questionable. A simpler managed service or even sticking with your current provider's upgrade path might be more cost-effective.
Regulatory constraints can also block or complicate migration. Cross-border card issuance, for example, involves navigating different regulatory frameworks. A platform might handle the technical side, but your legal and compliance teams need to sign off on the new structure, and that process is independent of whichever software vendor you choose.
Practical Next Steps
If you are considering a card modernization initiative, start with a clear understanding of your current state. Document every card product, every integration, every vendor relationship, and every custom feature. Get that baseline before you talk to any platform provider. It will save you months of confusion later. When evaluating platforms, ask specifically about their migration methodology and request a detailed case study from a recent implementation. Most providers can show you the polished version. Push for the version that includes the problems they encountered and how they resolved them. That tells you more about the platform's real capabilities than any sales deck. For Acgcard Services, I would recommend requesting a hands-on evaluation with your own test data loaded into their environment. Running your actual card products through their issuing and processing flow will reveal compatibility issues faster than any demo. Budget extra time for the data remediation work that always shows up during that phase.

The bottom line is that card modernization is achievable, but it is a project management exercise as much as a technical one. The platform gets you part of the way there. The rest depends on preparation, realistic expectations, and knowing where the rough patches are before you hit them.


