How to Calculate and Use the Equity Ratio in Practice
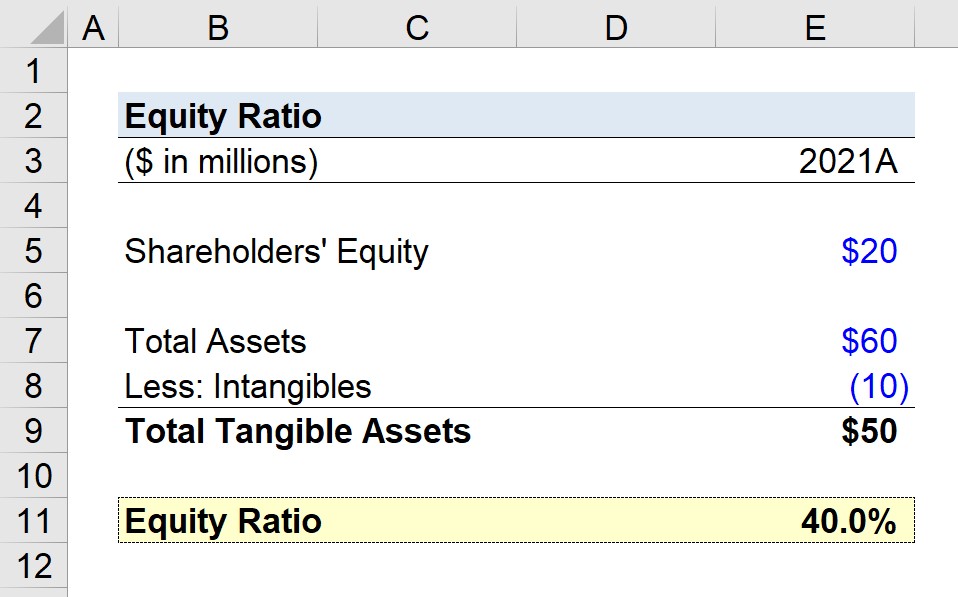
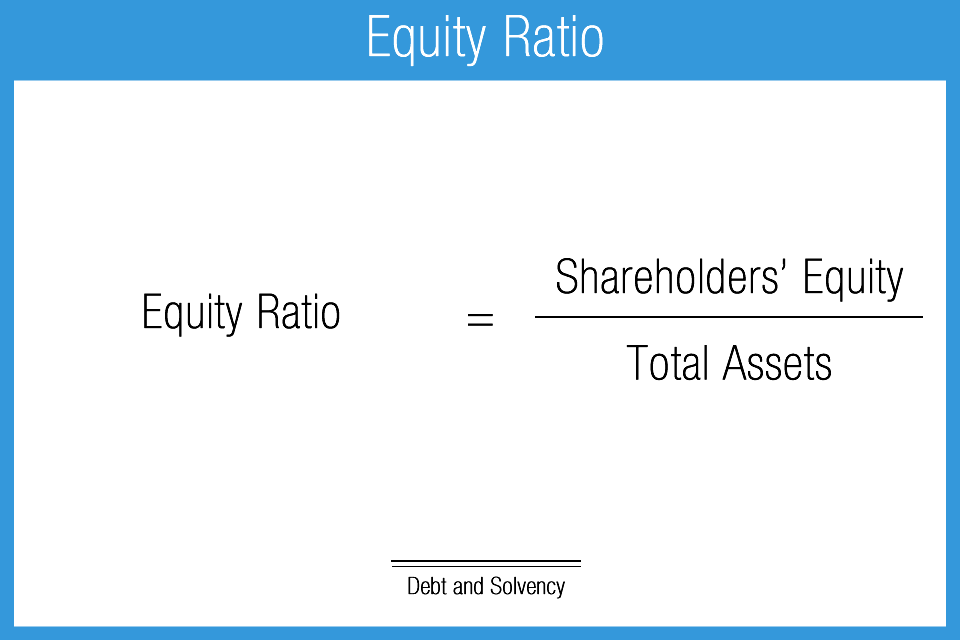
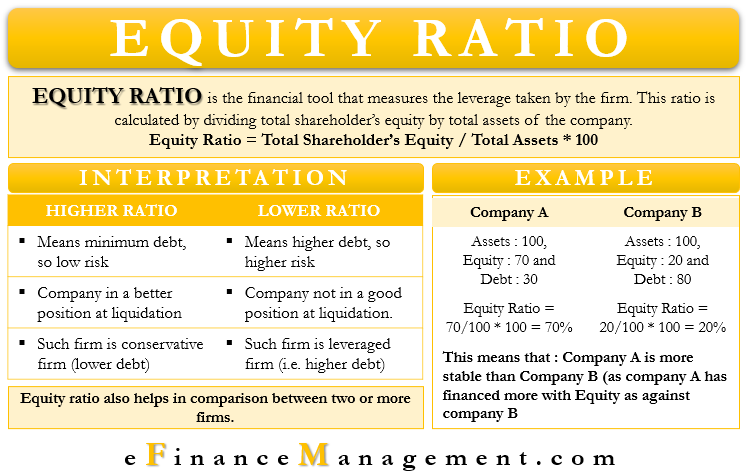
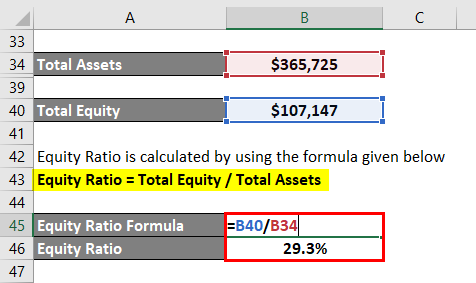
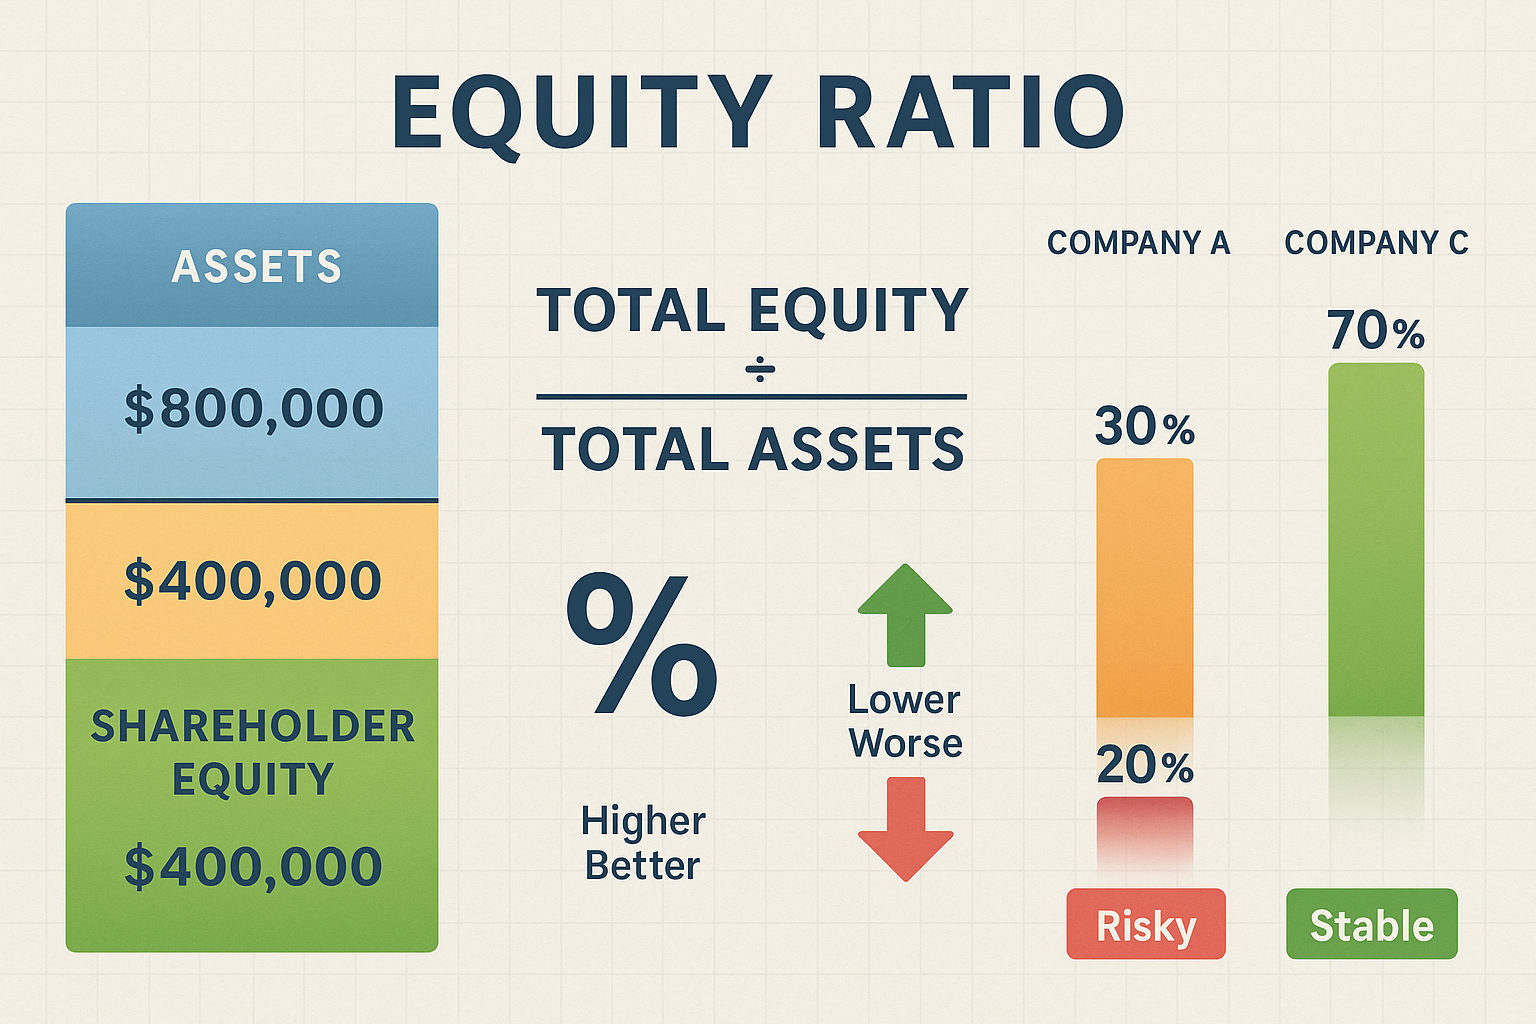
The equity ratio is one of those metrics everyone tells you to watch but rarely explains how it actually behaves under pressure. It's straightforward on paper: total shareholder equity divided by total assets. The formula itself takes about ten seconds. The part that matters is understanding what the number is hiding. Total equity goes on top. Total assets on the bottom. Simple division. If a company has $600 million in equity and $1.2 billion in assets, the ratio is 0.5 or 50%. That's the mechanics. Most people stop there and make decisions based on it anyway.
Unraveling The Mysteries Of The Equity Ratio Formula Unlocking Business Success
Here's what nobody puts in the textbook: the equity ratio can be manipulated without changing a single dollar of real economic value, and it happens more often than you'd expect on balance sheets that look perfectly fine. I ran into this during a commercial lending review about three years ago. A manufacturing client reported an equity ratio of 42%, which looked healthy on the surface. When I dug into the equity line items, I found they'd revalued a property they'd owned since 1998 to reflect a speculative commercial appraisal, adding roughly $8 million to their equity base overnight. That revaluation pushed their ratio above the bank's threshold for better loan terms. The cash flow hadn't changed. The actual debt-servicing ability was identical to the month before. The ratio improved, but nothing real moved. The workaround I used was to construct a adjusted equity ratio that excluded revaluation surpluses and other comprehensive income items, using only contributed capital and retained earnings. That version came out to 31%. We underwrote against the lower number and structured the loan accordingly. The borrower wasn't unhappy — they understood why we needed a more conservative measure. The equity ratio tells you what percentage of assets are owner-funded versus creditor-funded. A higher ratio generally means more financial stability. A lower ratio means more leverage and more risk. That's the basic framework. But the useful information lives in the details between those two sentences.
There's a counter-intuitive situation where a rising equity ratio isn't actually a good sign. If a company is shrinking its asset base faster than it's paying down debt, the ratio climbs because the denominator is collapsing. A mining company selling off its equipment and properties while maintaining the same debt load will show an improving equity ratio over two or three years. The trend looks positive until you realize they're liquidating the business rather than strengthening their balance sheet. I've seen this play out in the energy sector during commodity downturns. The ratio told one story. The operations told another. Another thing that trips people up is the treatment of preferred equity and minority interest. Depending on which accounting standard you're using, these sit somewhere between debt and equity on the balance sheet. If you include them in total equity, your ratio looks stronger. If you exclude them, it drops. There's no universal rule about which approach is correct — it depends on who's asking. Banks tend to exclude preferred equity. Equity analysts often include it. Both positions have merit in different contexts. When you're actually working with this ratio, the first step is pulling the numbers from the most recent balance sheet. Total shareholder equity, sometimes called total owners' equity or book value of equity depending on the jurisdiction. Total assets, which should include everything the company owns and controls. Run the division. Express it as a decimal or percentage.
Get the Full Details
Then do the things most people skip. Check the trend over at least three years. A single data point tells you very little. Look at what's driving the changes quarter over quarter. Is equity growing through retained earnings, or through capital injections? Are assets growing through organic investment or acquisitions? The answers to those questions matter more than the raw ratio. Compare the ratio to peers in the same industry. A 40% equity ratio might be excellent for a software company and terrible for a utility. Capital-intensive industries naturally carry lower ratios because they require massive asset bases that are often debt-financed. Service businesses typically run higher. The comparison group matters. One practical application I use regularly is stress-testing the ratio under different scenarios. What happens if revenue drops 20% and the company takes a write-down? Recalculate equity and assets under that assumption. The ratio might drop below a critical threshold that triggers covenant violations or makes refinancing impossible. This exercise usually takes about twenty minutes in a spreadsheet and has saved me from approving deals that would have looked fine on a static snapshot.
There are also scenarios where the equity ratio is essentially useless. If a company holds significant intangible assets — goodwill from acquisitions, brand value, customer relationships — those are often recorded at values that don't reflect realizable worth. In a liquidation scenario, intangibles may generate nothing. Stripping them out of the asset base gives you a much lower equity ratio that better represents recovery potential. I learned to do this manually after working with several tech companies where goodwill made up over half of total assets. The reported equity ratios were misleading in ways that only became apparent when things went wrong. The equity ratio also doesn't capture off-balance-sheet obligations. Operating leases, pension liabilities, contingent commitments, and joint venture obligations can all create real financial exposure that isn't reflected in the ratio. Under newer lease accounting standards some of this has improved, but gaps remain. A company with a strong equity ratio can still be sitting on significant hidden leverage if management is aggressive about keeping obligations off the books. My general approach when evaluating a company is to calculate the equity ratio, adjust it for revaluations and intangibles, check the three-year trend, compare to peers, run a downside scenario, and then reconcile what the number says against what the cash flow statement actually shows. If the equity ratio is healthy but free cash flow has been negative for two years, the ratio is probably going to deteriorate regardless of what it looks like today. Cash flow is the leading indicator. The balance sheet is the lagging indicator.
The equity ratio is a useful starting point, not a destination. It works best when combined with leverage ratios like debt-to-equity and interest coverage, and when you understand what's behind the numbers rather than treating the calculation as the analysis itself.