The Role Most People Get Wrong
Asset management supervision in practice has very little to do with spreadsheets and very little to do with what the job descriptions say. You have physical assets scattered across locations, depreciation schedules colliding with unexpected failures, budget cycles that don't align with anything sensible, and people who genuinely believe that because an asset is tagged it is somehow accounted for. That last one comes up constantly. When I first took on the supervisor side of asset management, I spent about three months dealing with an ERP system that showed $2.4 million in fixed assets while the warehouse inventory count came to roughly $1.8 million. The gap wasn't theft. It was capitalized work in progress that nobody had derecognized after projects finished, spare parts that were expensed on purchase but still sitting in the system as assets, and about fourteen pieces of equipment that had been fully depreciated but never removed from the register. That's not a rare situation. It's the default state for most organizations that treat asset management as an accounting function rather than an operational one.
Unraveling The Mysteries Of Supervisor Manajemen Aset A Comprehensive Guide
The core of this work breaks down into about five operational rhythms that repeat on different timeframes. I'll list them in the order they actually matter to someone trying to keep their head above water, not in textbook order. Physical verification cycles. This is where most programs fail before they start. A annual stocktake of fixed assets sounds reasonable until you remember that a manufacturing plant with rotating equipment, temporary job-site tools, and inter-department transfers can easily move forty percent of its register in a single quarter. The workaround I learned was to stop trying to verify everything at once. Instead, I segmented the register by risk tier and movement velocity. High-risk assets—those above a certain value threshold or with transfer history—got quarterly counts. Low-risk furniture and fixtures got sampled annually. IT equipment with known lifecycle patterns got verified at deployment and removal. This cut verification time from roughly six weeks of full lockdown to about ten days of rolling counts that didn't require shutting anything down. Depreciation and revaluation discipline. The textbook answer is to follow your local accounting standard and recalculate schedules monthly. The practical answer is that depreciation errors in asset registers cascade. A misclassified useful life on one category of machinery will throw off your depreciation expense for three years, your tax reconciliation, and your budget forecasting simultaneously. I found that maintaining a separate asset characteristics log outside the ERP—documenting the actual useful life based on maintenance history rather than the default table values—caught discrepancies early. When a pump originally scheduled for seven years showed consistent degradation at year four, adjusting the remaining book value rather than waiting for full depreciation prevented a sudden hit to the P&L during replacement planning.
The interface between procurement and the asset register. This is the bottleneck that causes the most headaches. Procurement buys something. The asset team hears about it three weeks later from an invoice that doesn't match the capitalized value. The asset gets recorded with the wrong cost center, wrong department, wrong useful life. By the time you catch it, three months of depreciation have already posted against the wrong bucket. The fix isn't more training. It's making the asset registration step a hard gate in the procurement workflow—a simple checkbox that won't clear payment until the asset record exists with the correct details. We implemented this through a basic integration between the procurement system and the asset management module. It took about two weeks to configure and eliminated about eighty percent of the misclassification issues we were seeing. Disposal and retirement process. Nobody enjoys this part. An asset reaches the end of its useful life, sits in a storage room for fourteen months because the disposal budget hasn't been approved, then gets sold for scrap and the proceeds disappear from the register entirely. The result is your physical count shows fewer assets than the book, you've taken depreciation on something that was gone months ago, and your gain or loss calculation on the next audit looks like a guess. I started requiring a disposal queue with expected retirement dates entered at the point of acquisition. When an asset approaches its scheduled end of life, a notification fires sixty days before. If no action is taken, it escalates. This doesn't prevent all disposal delays—budget cycles are what they are—but it makes the delays visible and documented rather than hidden until audit season. Reporting that actually gets used. Asset reports are among the most generated and least read documents in any organization. The typical one runs twelve pages of tables that no one opens. The useful report is five minutes to scan and answers one question: what do I need to know today? For a supervisor, that usually means a daily view of assets flagged for review—discrepancies from the last count, assets approaching end of life, items with no maintenance record in the past year, and any register changes made in the last forty-eight hours. That's it. Everything else goes on demand.
Get the Full Details

What Nobody Tells You About The Job
Asset management supervision is less about technical knowledge and more about managing the gap between what the system says and what exists. The system is maintained by people who don't walk the floor. The floor has people who don't understand the system. Your job is the translation layer between them. The most counter-intuitive thing I learned is that a slightly inaccurate register with regular reconciliation beats a theoretically perfect register that hasn't been touched in six months. Audit committees love clean initial setups. They tend to overlook the fact that every organization drifts from its register within ninety days of implementation. The organizations that look best on paper are usually the ones that just haven't been checked recently. Another thing that trips people up: software choice matters less than process enforcement. I've seen organizations spend hundreds of thousands on enterprise asset management platforms and still have worse data quality than a company using a basic inventory tool with daily verification habits. The platform doesn't manage assets. The habits around the platform do.
There are also scenarios where asset management frameworks completely fail, and it's worth knowing them before you commit to one. Organizations undergoing mergers are one. Two different depreciation methods, two different chart of accounts, two different disposal policies—the integration work alone can consume a full fiscal quarter with no improvement in data quality during that time. Restructuring with frequent department transfers is another. Every asset move becomes a reconciliation task, and if the transfer policy isn't enforced, your register becomes a historical record rather than a current one. In both cases, the workaround is maintaining a parallel tracking register for the transition period until the data stabilizes.
Practical Starting Points
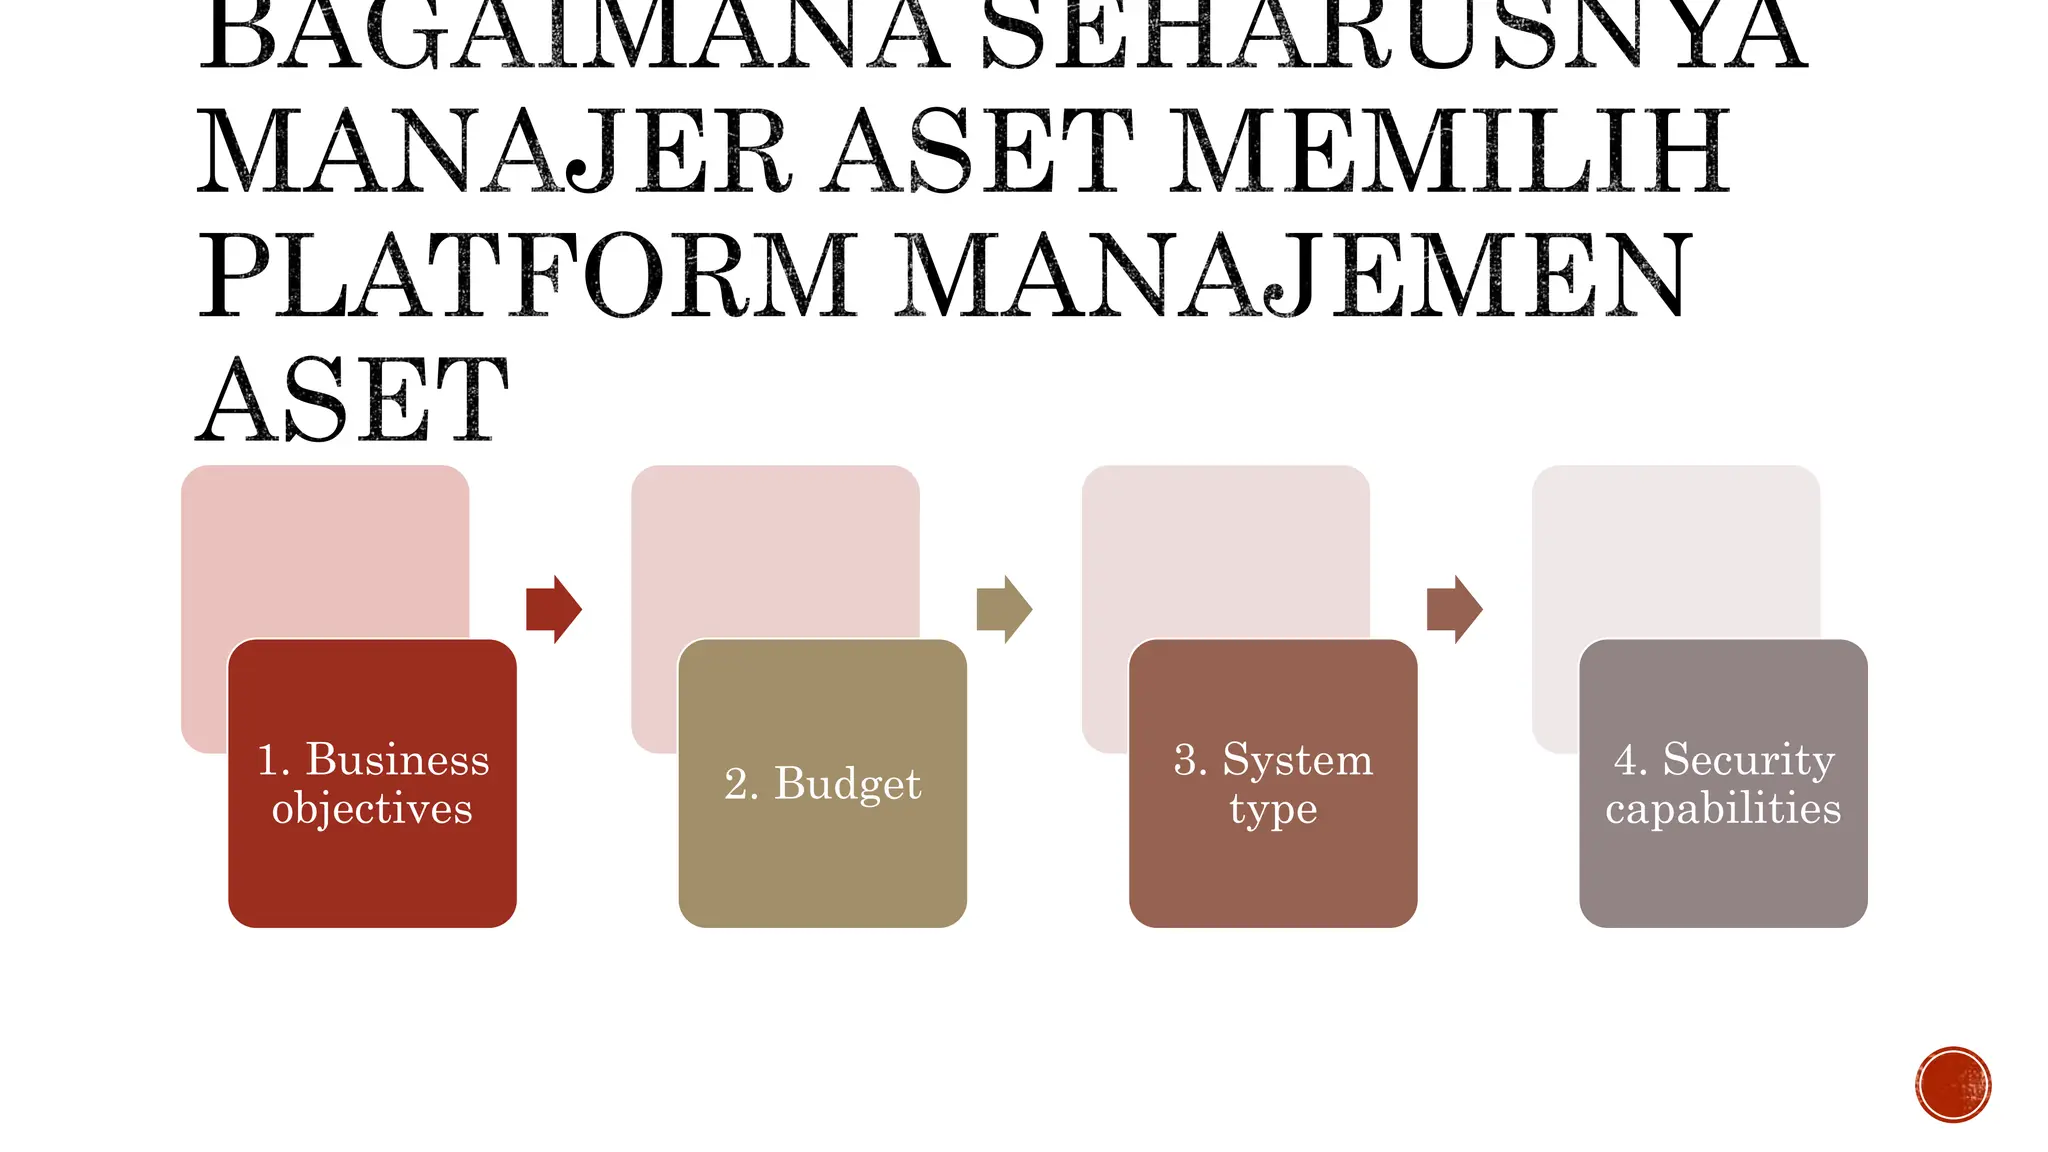
If you're new to this role and your organization doesn't have an established system, here's what I'd prioritize in order. First, establish a unique identifier system that survives procurement, transfer, refurbishment, and disposal. Barcodes or RFID tags are standard now, but the identifier needs to be tied to the asset record in a way that doesn't break when the tag is replaced or damaged. Second, run a baseline physical verification across your entire register before you implement anything else. You need to know where you actually are before you can improve. Third, define the procurement-to-registration handoff process and get it embedded in the purchasing workflow before you invest in any software. Fourth, set up the disposal queue system I described earlier. Fifth, build the daily review report. Software recommendations depend entirely on your scale and industry. Small operations under fifty assets can manage with a well-structured database and strict entry protocols. Mid-size operations typically need a dedicated asset management module integrated with their ERP. Large organizations with complex maintenance requirements usually end up on platforms like Fiix, UpKeep, or an ERP-native solution. The decision should be driven by your transaction volume and integration needs, not by feature lists. If your register changes less than five percent per month, you don't need real-time tracking. If your maintenance team needs work orders linked to asset history, that changes the requirement significantly. The most useful resource I found wasn't a certification program or a textbook. It was maintaining a personal log of every discrepancy I encountered, categorized by root cause. After six months of that, the patterns become obvious and preventable. The log also becomes your evidence base when you need to justify process changes or budget requests to management. Numbers from your own operations carry more weight than any industry benchmark.
There's also a learning curve around the regulatory side that most guides skip. Depending on your jurisdiction, there are tax implications for depreciation methods, specific requirements for certain asset categories, and reporting obligations that vary by industry. Environmental regulations may apply to hazardous equipment disposal. Insurance requirements may dictate how you classify and value certain assets. This isn't optional background knowledge. It's the difference between a register that satisfies your accountant and one that satisfies everyone else who has a claim on your data. One final thing that isn't covered in most materials: the human side of this work. Asset managers and supervisors spend a lot of time convincing other departments that tagging their equipment and filling out transfer forms matters. The resistance is real and usually comes from people who view these processes as administrative overhead rather than operational necessity. The most effective approach I found was to make the system benefit them directly—showing maintenance teams that a well-maintained asset register meant they had spare parts available when needed, or demonstrating to department heads that proper classification meant their budgets weren't being depleted by assets owned by someone else. When people see the practical value, compliance improves without enforcement. The role itself is steady work with periodic intensities. Most weeks involve routine verification and data maintenance. Certain periods—quarterly close, audit season, budget planning—concentrate the pressure into manageable spikes. If you approach it as a data cleanliness problem rather than a technical accounting problem, it's straightforward. If you treat it as purely a compliance exercise, it becomes endless and unrewarding. The best supervisors I've worked with treated it as an operational intelligence function. The register wasn't a compliance document. It was the organization's actual picture of what it owned, where it was, what shape it was in, and what it would cost to replace. That framing changes everything about how you prioritize the work.


