Converting Large Euro Amounts to Dollars Without Getting Ripped Off
Most people don't realize how much money they lose when they convert 1000 euros or more at a standard bank or airport kiosk. I've watched it happen hundreds of times. The difference between a decent rate and a bad one on that amount isn't a few cents—it can be $40 to $80 gone before you even leave the building. The phrase "unraveling the euros might breaking down 1000 euros in dollars" sounds like a clumsy translation of what people are actually trying to do: take a large sum in one currency and get it into another without the middleman eating their profit. It's not a formal financial term. It's just what regular people call it when they're trying to figure out the real conversion before handing over their money.
Unraveling The Euros Might Breaking Down 1000 Euros In Dollars
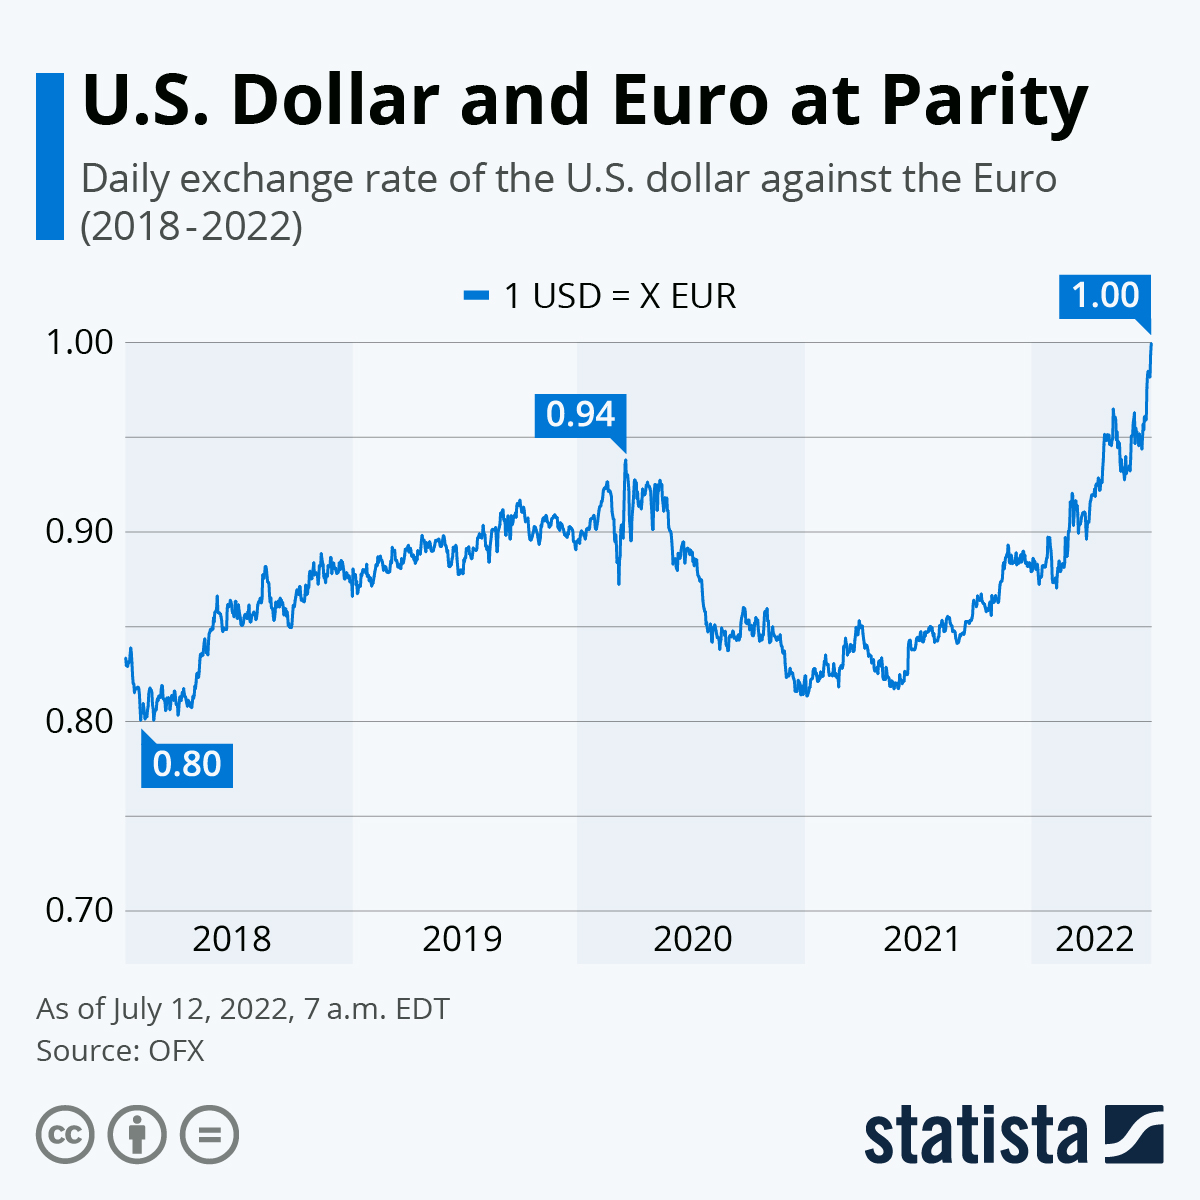
The process itself is straightforward math, but the traps are everywhere. Let's skip the fluff and talk about what actually matters. First, get the mid-market rate. This is the rate you see on Google or XE.com—the one neither bank nor exchange service uses for their own advantage. As of mid-2024, that rate sits roughly around 1.07 to 1.09 depending on the day. So 1000 euros at the mid-market rate would be approximately 1,070 to 1,090 US dollars. But you will never get that rate at a physical location unless you know exactly where to look. Banks typically markup the rate by 2.5% to 4%. That's not extreme for them, but on 1000 euros it means you're losing $25 to $40 compared to the real rate. Airport kiosks and hotel exchange counters are worse—sometimes 6% to 8% markup. You hand over 1000 euros at an airport and walk away with maybe 980 dollars instead of the 1080 you should be getting. That's not a typo.
The workaround I use and recommend is simple: order your foreign currency through a specialized online service before you travel. Services like Wise (formerly TransferWise), Revolut, or even your own bank's online portal if they advertise "no fee" transfers will give you a rate much closer to the mid-market. With Wise, for example, I've consistently gotten within 0.5% of the Google rate, and the fee is usually a flat amount under 1% rather than a hidden spread. On 1000 euros, that difference between Wise and a standard bank is roughly $20 to $35 saved. I had a specific case last year where someone needed to move 1000 euros to dollars urgently for a property deposit. They went to their bank branch, got quoted a rate that translated to about 1,048 dollars. I checked Wise at the same moment—the same euros would have netted them 1,072 dollars. A 24-dollar gap, but the real problem was the urgency clause. The bank was right: same-day in-branch exchange almost always carries a higher spread because they're taking on more risk. If you can wait 1 to 3 business days for an online transfer, the rate improves dramatically. Here's something most people miss: the currency pair EUR/USD is actually one of the most liquid pairs in the world. That means the spread between the buy and sell price is naturally tighter than almost any other pair. When someone tells you they can't give you a good rate on euros to dollars, they're either lying or using a third-class counter. It should not be hard to find a sub-1% markup. It is very easy to find one under 0.5% if you're willing to use the right platform.
Get the Full Details
Another edge case that catches people out is partial conversion. Say you convert 1000 euros but only end up needing 600 dollars. Some services charge a minimum fee per transaction regardless of size. Wise has a tiered structure, but Revolut's free tier caps out at a certain amount per month before fees kick in. Know your volume before you commit. If you're regularly moving amounts between 500 and 2000 euros, a subscription to a service like Wise or Revolut pays for itself within a single transaction compared to traditional banks. For large sums specifically—anything over 2000 euros—I'd also look at multi-currency accounts that let you hold both euros and dollars simultaneously. That way you're not forced to convert at an unfavorable moment. You can wait for a better rate. I've sat on a euro balance for three weeks waiting for the dollar to dip below 1.06 before converting 3000 euros, and that patience saved me roughly $60 compared to converting on the first day I needed it. Watch out for dynamic currency conversion too. If you're paying with a card in Europe and the terminal asks whether you want to pay in euros or dollars, always choose euros. Choosing dollars lets the merchant's bank do the conversion at their rate, which is almost always worse than your card issuer's rate. I've seen this cost people an extra 3% to 5% on top of whatever their card already charges. On a 1000 euro purchase, that's another $30 to $50 down the drain.
There's no perfect solution here. Every method has tradeoffs. Instant in-person exchange costs more. Online transfers are cheaper but not instant. Waiting for a better rate means you might miss a transaction deadline. But knowing these layers means you're making an actual choice instead of blindly accepting the first number someone gives you. That's the difference between losing money and keeping it.