What EBIT Margin Actually Tells You
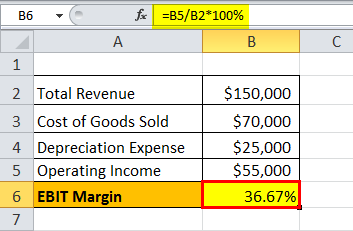
Most people calculate EBIT margin and then stop. That is where the mistake happens. Earnings before interest and taxes divided by total revenue gives you a percentage that represents how much operating profit a company keeps from every dollar of sales. The formula is EBIT / Revenue x 100. Simple enough. The problem is what people do with the number afterward. I spent years looking at margin profiles across different industries and the ones that consistently trip people up are not the calculation itself. It is the interpretation. Take two companies in the same sector with identical revenue and identical EBIT margins. One will destroy cash. The other will print it. The margin number looks the same. The reality could not be more different. I do not pull EBIT margin in isolation. The first thing I check is the relationship between EBIT and operating cash flow. If EBIT margin is 15 percent and operating cash flow margin comes in at 4 percent, something is eating the difference. Usually it is working capital moves. Inventory builds up. Receivables stretch. The business looks profitable on paper and is quietly running out of money.
When I look at a financial model, I pull EBIT directly from the income statement. Then I verify it against the cash flow statement. If they do not reconcile within a reasonable range, I dig into depreciation schedules and lease obligations before moving forward. This step usually takes about five minutes and catches problems that would otherwise sit hidden for weeks.
Common Pitfalls That Wreck This Metric
The biggest issue I see is treating EBIT as a cash proxy. It is not. Depreciation and amortization are deducted to arrive at EBIT, but they are non-cash charges. In capital-intensive businesses like manufacturing or telecom, EBIT margin can look healthy while free cash flow stays negative for years. A 20 percent EBIT margin means nothing if replacement capital expenditures eat 22 percent of revenue every year. Free cash flow is the number that matters for actual business survival. Another frequent mistake is ignoring how restructuring charges are handled. Some analysts strip them out. Others include them. The resulting EBIT margin can swing by several percentage points depending on your choice. When I compare companies, I use a normalized EBIT figure that removes one-time items and restructuring costs. This makes the comparison actually meaningful. I also flag a specific edge case that cost me time on a project a few years back. We were evaluating a regional logistics company and their reported EBIT margin came in around 11 percent, which looked strong for the sector. The catch was that they had recently exited a lease-heavy fleet model and recorded a large gain on disposal of operating equipment. That gain was buried inside operating income and inflated EBIT. After stripping out the non-recurring gain, the true EBIT margin dropped to 7 percent. The acquisition thesis changed completely once we adjusted for that. The lesson was straightforward: always trace the line items that flow into EBIT rather than trusting the subtotal as presented.
Get the Full Details
When EBIT Margin Fails Completely
Financial services and insurance companies are not worth analyzing with EBIT margin. Interest is a core operating expense for lenders. Subtracting it out produces a number that looks artificially high and is useless for comparison. Use net margin instead. Capital-intensive industries like utilities and semiconductors also distort EBIT margin because depreciation varies wildly between companies with different asset ages. Two plants doing identical work can report very different EBIT margins simply because one replaced its equipment last year and the other is running depreciated assets from a decade ago. Startups and pre-profit companies produce meaningless EBIT margin numbers during early growth phases. Revenue is small, fixed costs are large, and the margin swings are driven by accounting timing rather than operational reality. Free cash flow burn rate and unit economics are far more informative in those situations.
Practical Steps to Calculate It Correctly
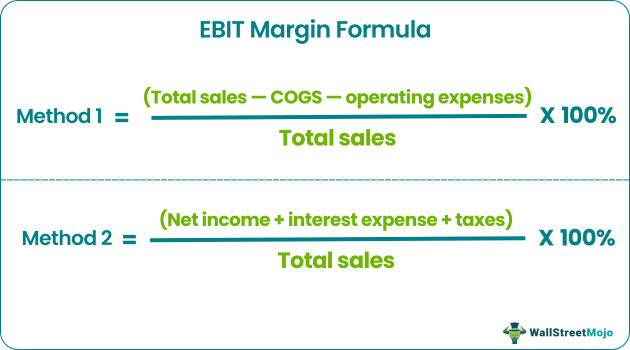
Find EBIT on the income statement. It appears as operating income in most standard formats. If the statement uses gross profit minus operating expenses without labeling it clearly, do the arithmetic yourself: Revenue minus cost of goods sold minus operating expenses equals EBIT. Do not include interest expense or income tax expense. Do not add back depreciation if your goal is to compare against peers who use GAAP operating income. Divide EBIT by total revenue. Multiply by 100 to get the percentage. Record the result alongside free cash flow margin and net margin on the same spreadsheet row. The three together tell a fuller story than any single number. I track EBIT margin trend lines over at least four quarters before drawing conclusions about a business. A single quarter can be noise. Four consecutive quarters smooth out seasonal effects and give you a reliable baseline. If the trend is improving, the operational changes are working. If the trend is flat or declining, no amount of narrative about market conditions will fix the underlying efficiency problem.
Adjusting for Real-World Complications
Operating leases used to stay off the balance sheet and below EBIT. Under current accounting standards, most operating leases are now capitalized, which changes how EBIT is calculated and how margins compare across periods. If you are reviewing historical data before the lease accounting change, adjust the numbers or flag the inconsistency. Comparing a 2019 EBIT margin to a 2024 EBIT margin for the same company without adjusting for lease recognition will give you a distorted view of operational performance. Foreign currency operations add another layer. If a company reports in dollars but earns revenue in euros or yen, EBIT margin fluctuates with exchange rates even when the underlying business is stable. I normalize EBIT margin by recalculating it at constant currency when cross-border exposure exceeds 15 percent of total revenue. This removes the FX noise and reveals the actual operational trend.
What Good Looks Like
There is no universal threshold. Software companies commonly sit in the 25 to 35 percent range. Retailers operate in the 5 to 10 percent range and survive on volume. Healthcare services cluster somewhere in between. The useful comparison is always against peers in the same segment and against the company itself over time. A hardware manufacturer jumping from 8 percent to 12 percent EBIT margin is worth investigating. A software company falling from 32 percent to 28 percent is also worth investigating. Direction matters more than the absolute number. The bottom line is that EBIT margin is a starting point, not an endpoint. It identifies operational efficiency. It does not account for capital intensity, working capital demands, or financing structure. Use it alongside cash flow metrics and relative industry benchmarks. The pattern across multiple periods tells you more than any single quarter.