What Bonds Actually Are When You Strip Away The Finance Jargon
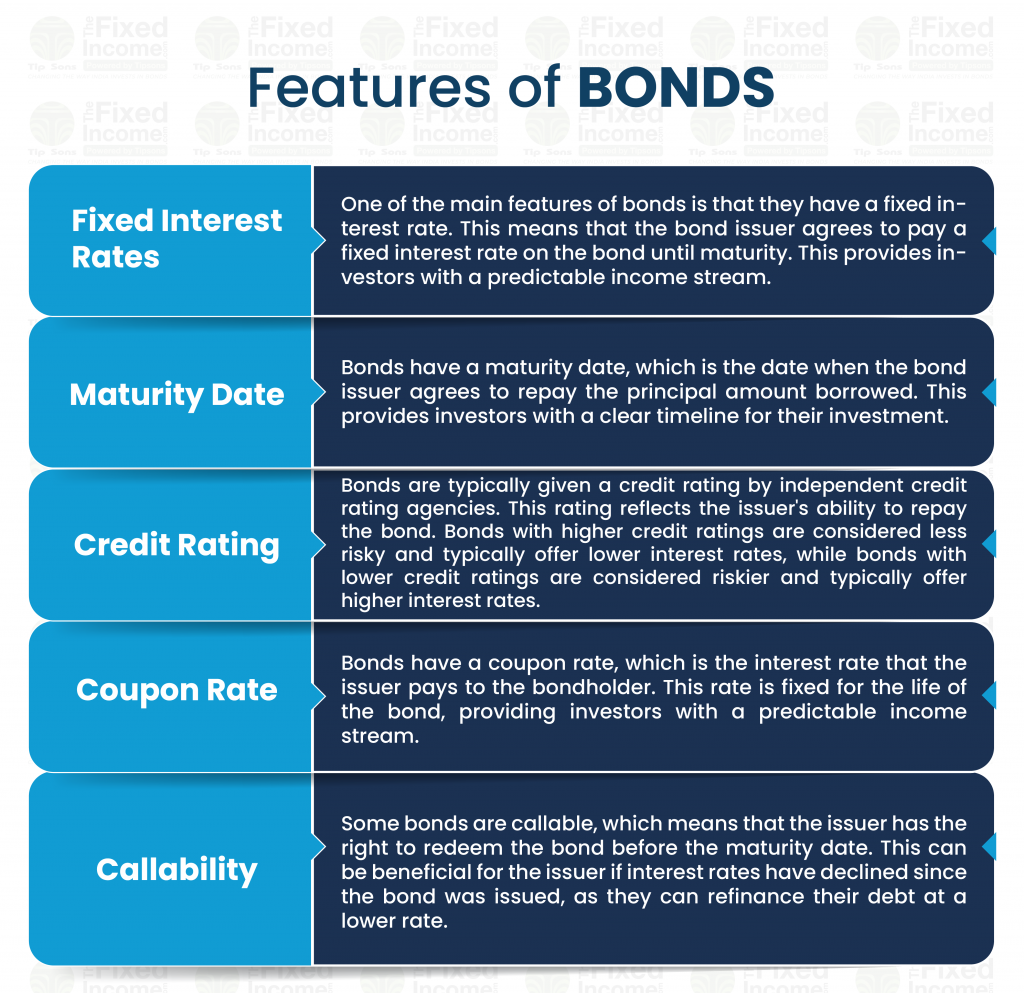
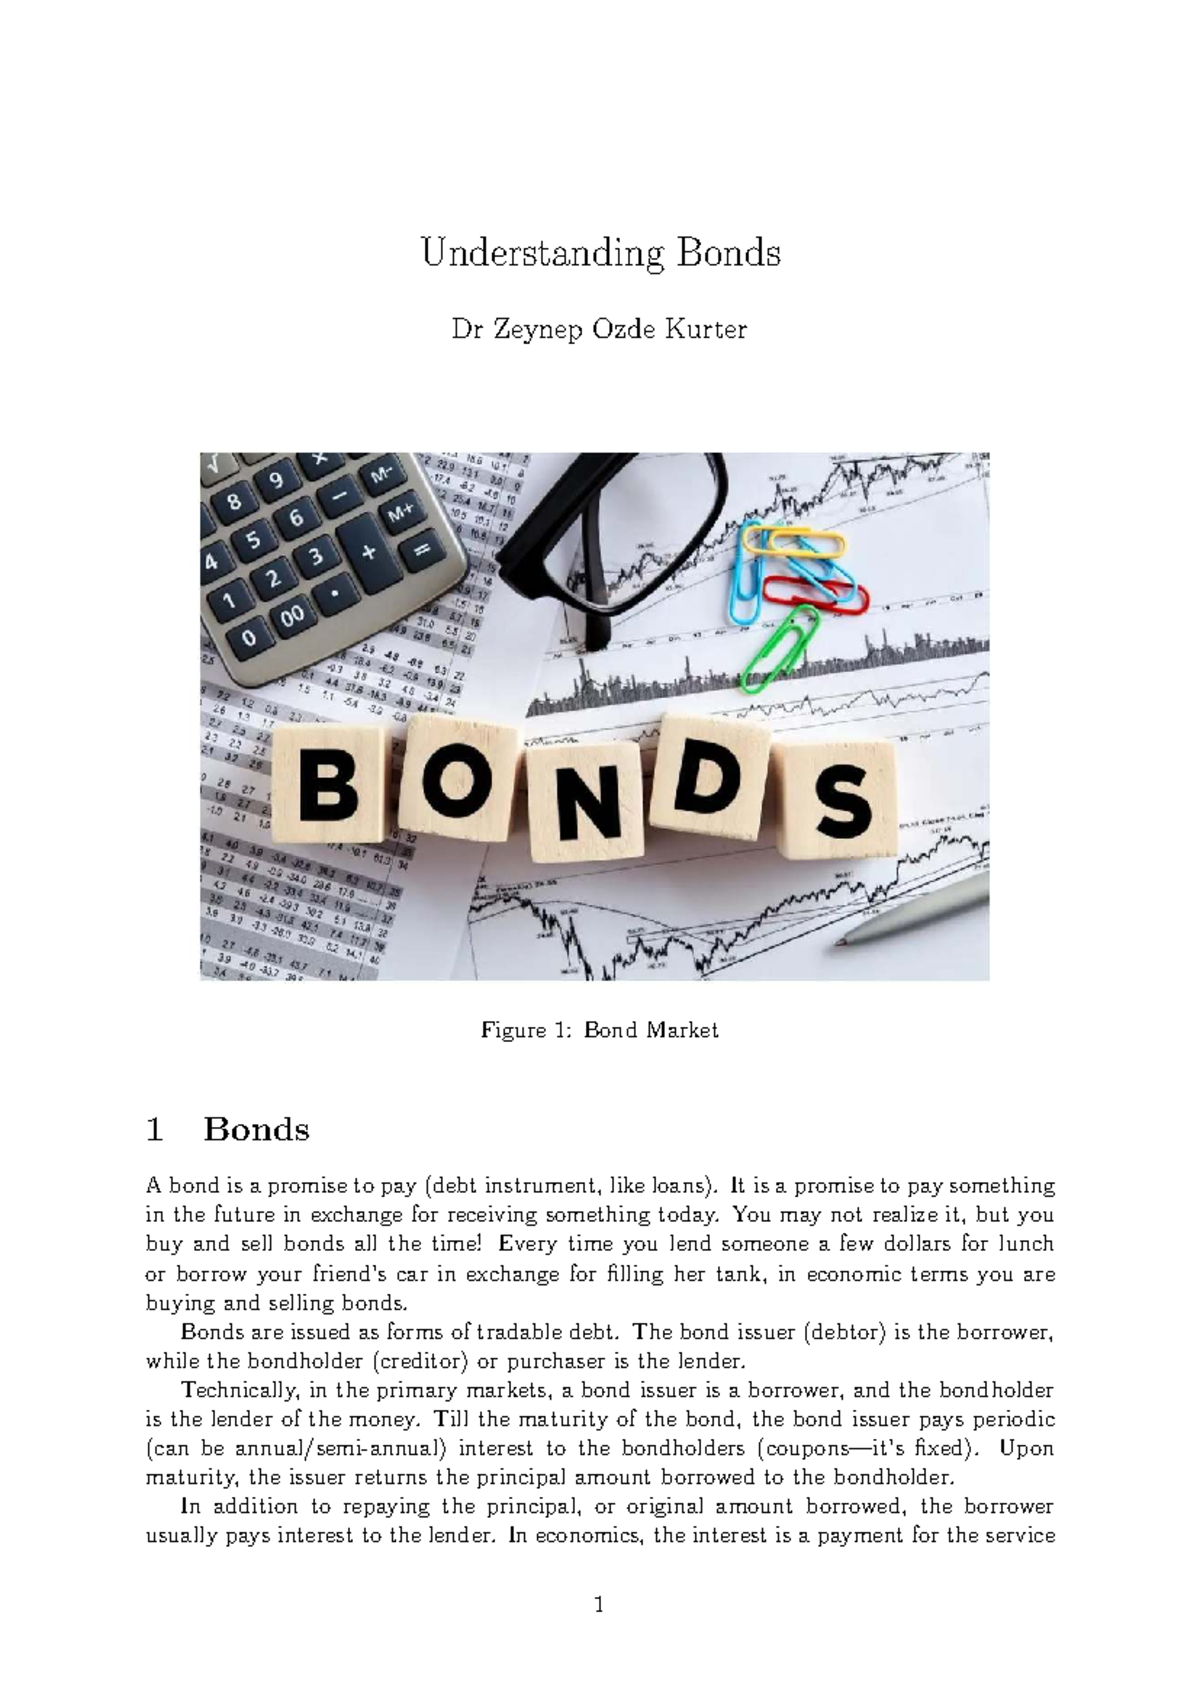
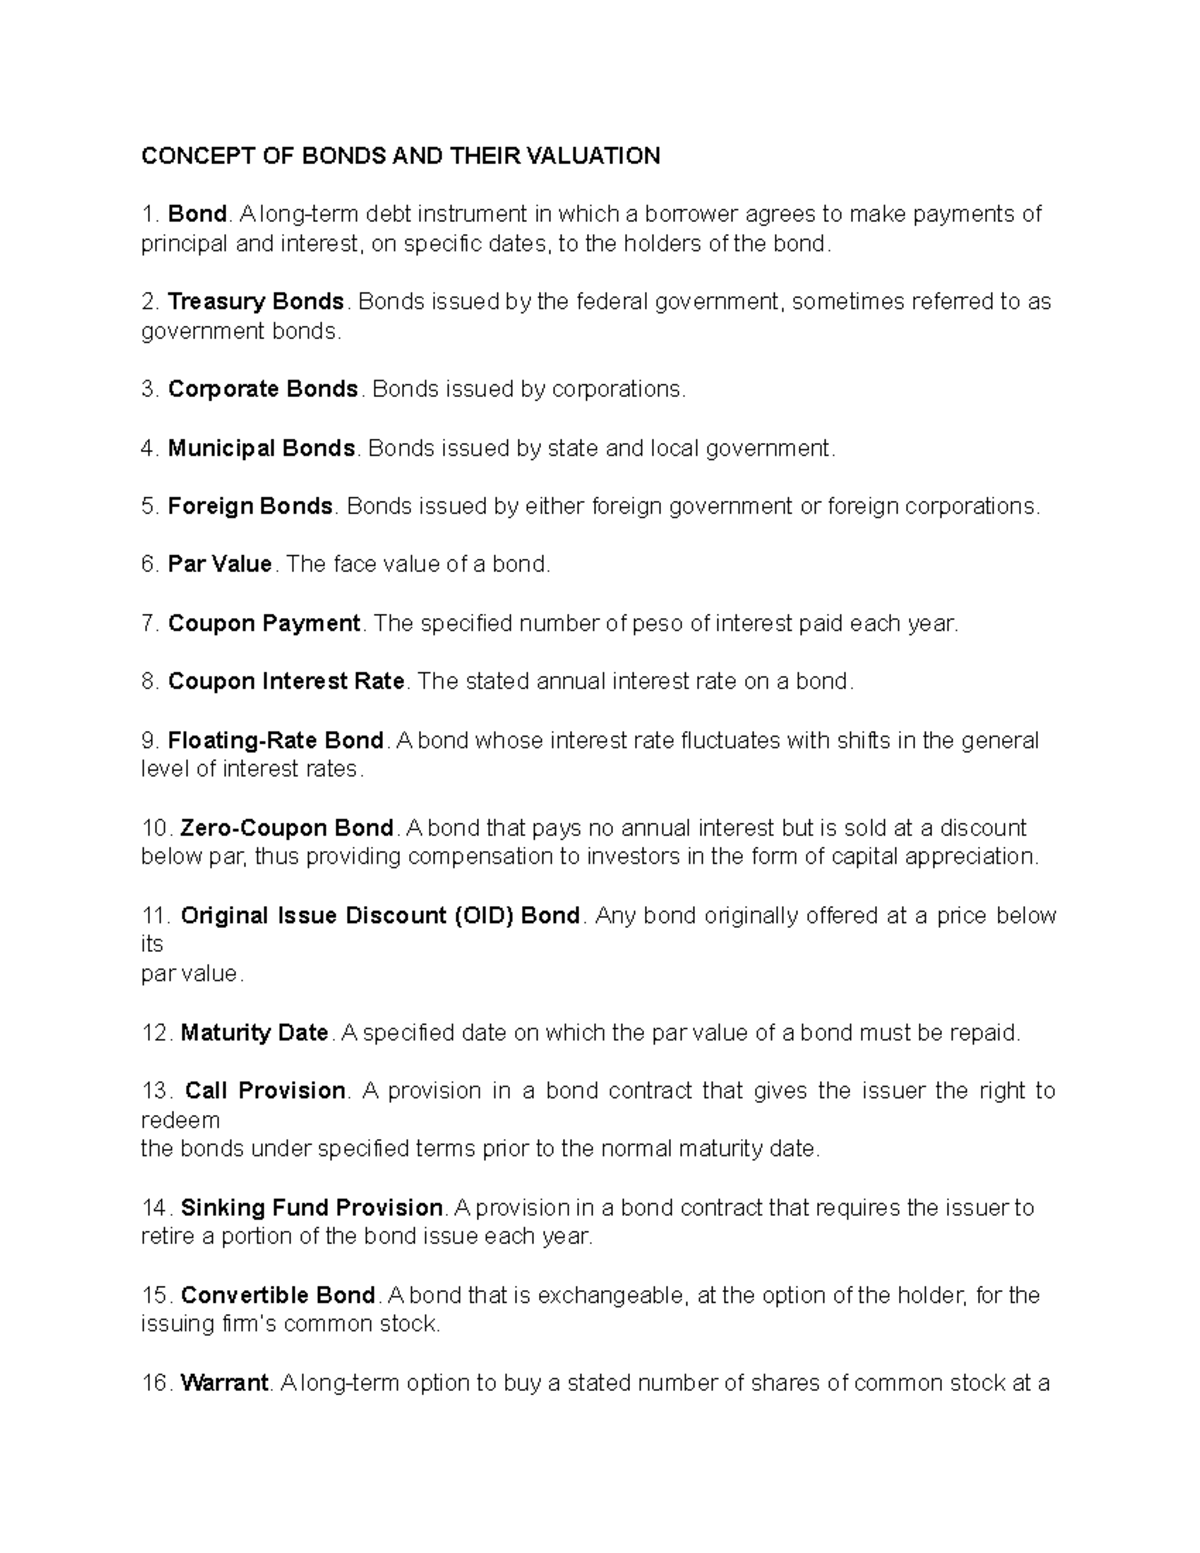
You lend money to a government or corporation, they give you a piece of paper that says when you get paid back and how much extra they throw in. That's the entire contract. Everything else is just wrapping it in different layers of risk and liquidity. The economic definition is straightforward: a bond is a debt instrument where the issuer borrows capital from an investor and promises to repay it at a future date with periodic interest payments. Fixed income. That's what people call it because the cash flow is predetermined. Not guaranteed in every case, but predetermined on paper. I've spent years watching people treat bonds like they're inherently safe. They're not. They're just differently risky than stocks. A bond from a company on the verge of bankruptcy pays a higher yield precisely because you might not see your principal back. I've seen portfolio managers ignore credit spreads because the coupon looked nice on the surface. They got burned in 2020 when the spread widened by 400 basis points in three weeks across high-yield issuers. The coupon doesn't protect you from default. Nothing does except diversification and understanding what you're actually buying.
Unraveling The Concept Of Bonds Understanding The Economic Definition And Its Role In Investing
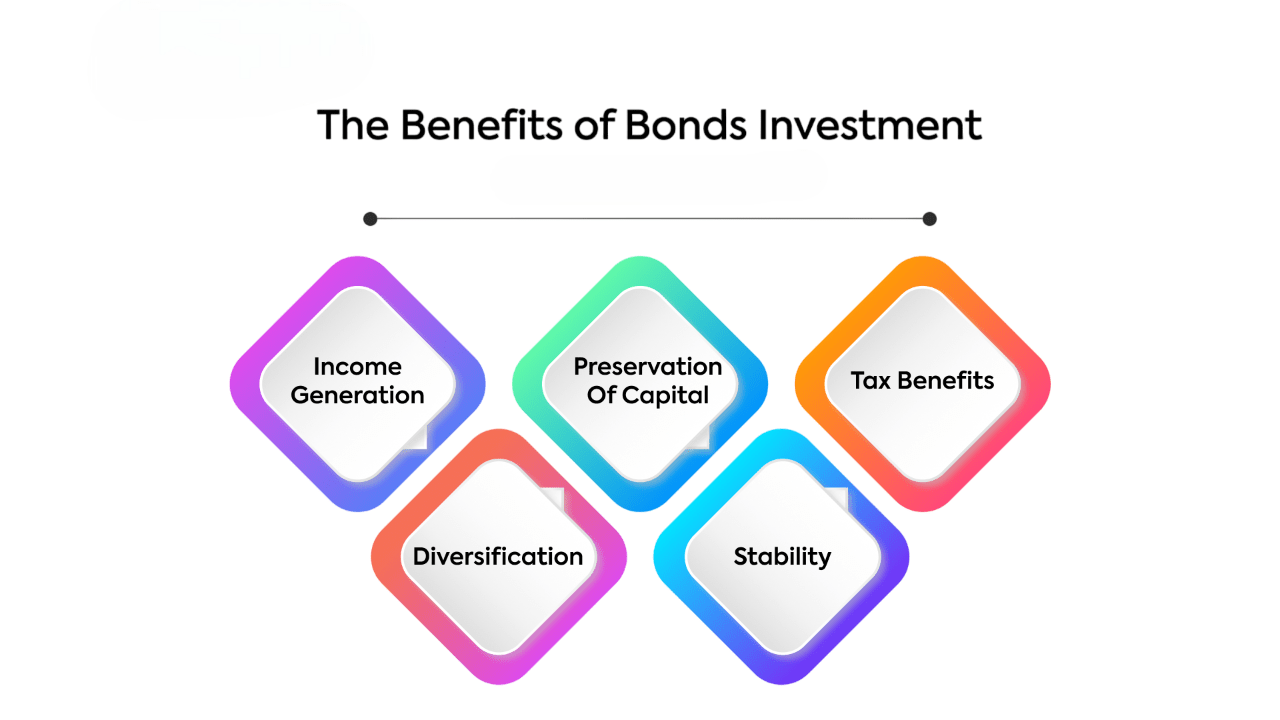
The role of bonds in investing is mainly about cash flow stability and reducing portfolio volatility. That's the textbook answer. The practical answer is more nuanced. Bonds serve as a ballast during equity drawdowns, yes, but that relationship isn't stable across all market environments. In 2022, both stocks and bonds fell together for the first time in decades because the Federal Reserve was raising rates aggressively. A portfolio that was supposedly diversified because it held 60% stocks and 40% bonds lost money across both sides simultaneously. Duration risk does exactly what it sounds like: it measures how sensitive a bond's price is to interest rate changes. A bond with a duration of 7 years will lose roughly 7% of its value for every 1% increase in interest rates. That's not theory, that's arithmetic you have to apply before you buy anything. Here's something most beginner guides don't tell you: the yield you see quoted on a bond isn't always what you'll actually earn. There's current yield, which is just the annual coupon divided by the bond's current price. Then there's yield to maturity, which assumes you hold the bond until it matures and that every coupon payment gets reinvested at the same rate. Neither of those assumptions holds up in reality. If interest rates drop after you buy a bond, you can't reinvest those coupons at the original yield. This is called reinvestment risk, and it's one of the most overlooked factors in bond investing. I ran into a specific problem a few years back working with a municipal bond holding that looked solid on paper. The bond was trading at a premium because its coupon rate was higher than prevailing rates. The yield to maturity was attractive. But the bond had a make-whole call provision that allowed the issuer to redeem it early if rates moved in their favor. I missed this because I was focused on the YTM number and didn't check the indenture documentation carefully enough. The bond got called two months later, and I was forced to reinvest at significantly lower rates. The workaround is simple but tedious: always read the call provisions and any embedded options in the bond's prospectus. It takes about 20 minutes per bond instead of the usual two, and it prevents exactly this kind of surprise.
Treasuries versus corporates versus municipals versus emerging market debt — each category has a completely different risk profile and tax treatment. Treasury bonds are backed by the full faith and credit of the U.S. government, so credit risk is essentially zero. But they're still exposed to interest rate risk and inflation risk. If inflation runs hotter than expected, the real return on a Treasury bond can go negative. I've seen this happen in the late 1970s and again in 2022. Corporates add credit risk on top of rate risk. The spread between a corporate bond yield and a Treasury yield of the same maturity is what compensates you for taking on that additional default risk. That spread is called the credit spread, and it widens during economic stress and compresses during expansions. Municipal bonds offer tax-exempt interest income at the federal level and often at the state level too if you're buying bonds from your home state. That tax advantage can make a lower nominal yield more attractive than a higher Treasury yield once you factor in your marginal tax bracket. The math is straightforward: if you're in the 35% federal tax bracket and a Treasury pays 4%, a municipal bond needs to pay more than 2.6% to be equivalent. Everything above that 2.6% threshold is actually better after taxes. But municipal bonds also carry credit risk, liquidity risk, and in some cases, the risk that state and local governments face fiscal distress. Puerto Rico is a well-known example where investors took losses on municipal debt.
Get the Full Details
How To Actually Evaluate A Bond Before Buying It
Start with the credit rating. Agencies like Moody's, S&P, and Fitch assign ratings that indicate the issuer's ability to meet its financial obligations. Investment grade starts at BBB- from S&P and Baa3 from Moody's. Anything below that is speculative grade, commonly called junk. The difference matters because junk bonds have historically delivered higher returns but with significantly more volatility and default risk. During the 2008 financial crisis, the default rate on high-yield bonds hit around 9%. That's not a theoretical number, that's actual money people lost. Next, look at the maturity and duration. Shorter maturities mean less interest rate risk but also less income. Longer maturities give you more income potential but expose you to bigger price swings when rates change. Duration is the metric that tells you exactly how much. A fund with an average duration of 10 years will move about 10% for a 1% rate change. This is critical when you're choosing between individual bonds and bond funds. Individual bonds let you hold to maturity and lock in your yield. Bond funds never mature, so you're always exposed to interest rate risk. If rates rise and they keep rising, the fund's NAV keeps declining with no point where it resets. Check the issuer's financial health. Debt-to-equity ratios, interest coverage ratios, free cash flow generation. These numbers tell you whether the company can actually service its debt. A firm with an interest coverage ratio below 2x is struggling to pay the interest on its existing debt, let alone new borrowings. I reviewed a mid-cap industrial company a while back that looked fine on the surface. Strong bond rating, reasonable yield. But their free cash flow had been negative for three consecutive quarters and their debt-to-EBITDA was climbing above 5x. I passed. They filed for Chapter 11 six months later. The bond dropped to 35 cents on the dollar.
For Treasuries, the key metrics are simpler. Look at the yield curve. The shape of the curve tells you what the market expects for future interest rates and economic growth. An inverted yield curve, where short-term rates are higher than long-term rates, has preceded every recession in the past 50 years. It's not a perfect predictor but it's worth watching. The spread between the 10-year and 2-year Treasury note is the most commonly cited version of this metric.
Common Mistakes People Make With Bonds
Focusing only on the coupon rate is the most common error. A bond paying 6% while trading at a steep discount could have a much higher yield to maturity than a bond paying 8% while trading at a premium. Always compare yields to maturity, not coupon rates. Another mistake is ignoring inflation. A bond yielding 5% when inflation is running at 6% is losing purchasing power every year. TIPS, or Treasury Inflation-Protected Securities, adjust their principal based on the Consumer Price Index and can help in inflationary environments, but they tend to underperform regular Treasuries when inflation falls. People also treat bond funds the same as individual bonds. They're not the same instrument. Individual bonds return your principal at maturity if the issuer doesn't default. Bond funds don't have a maturity date, so there's no guarantee you'll get your money back. During periods of rising rates, bond funds can lose value indefinitely. I've watched clients panic-sell bond funds in 2022 when NAVs dropped 10 to 15%, not realizing that holding individual bonds to maturity would have preserved their capital entirely. The lesson is that the vehicle matters as much as the underlying asset. There's also the Liquidity Trap. Some bonds, particularly certain municipal issues or emerging market debt, trade infrequently. The quoted price might not reflect what you'd actually get if you tried to sell. Bid-ask spreads can be enormous, sometimes 50 to 100 basis points or more. That's a hidden cost that eats into returns, especially if you need to exit quickly. I learned this the hard way with a small-cap corporate bond that had a quoted spread of 200 basis points over Treasuries. When I tried to sell a portion of the position, the actual execution price was 150 basis points worse than the quote. The market wasn't liquid enough to support the displayed price.

Practical Portfolio Allocation Considerations
The old rule of thumb is to hold bonds equal to your age, with the remainder in stocks. That's a starting point, not a strategy. A 30-year-old with low risk tolerance might still want 60% in bonds. A 60-year-old with significant pension income might only need 20%. Your allocation should reflect your actual cash flow needs, time horizon, and risk capacity, not a generic formula. Ladder strategies are worth considering if you're buying individual bonds. Instead of buying one bond that matures in 10 years, you buy bonds maturing in 1, 2, 3, 5, 7, and 10 years. This gives you regular liquidity events, reduces duration risk, and lets you reinvest at varying rate environments. It's more work to manage but it eliminates the uncertainty of having all your bond exposure at one maturity date. The trade-off is that laddering requires more capital to implement effectively and you lose some of the diversification that bond funds provide. For most investors, a combination approach works best. Core holdings in broad bond index funds for diversification and liquidity, with selective individual bond purchases for specific opportunities where you can find a mispricing or a favorable tax situation. The exact split depends on your circumstances. I typically recommend 70 to 80% in funds for the average investor, with the remainder in individual bonds for those who have the time and knowledge to do the due diligence properly. Trying to pick individual bonds without understanding credit analysis is how people lose money in what they thought was a safe asset class.
Bonds aren't exciting. They won't make you rich quickly. But they're the foundation of most portfolios that survive long-term market cycles. Understanding what you own, why you own it, and what could go wrong is the difference between holding bonds passively and actually investing in them. The economic definition is simple. The practical application requires more attention than most people give it.