Understanding Capital Structure Decisions
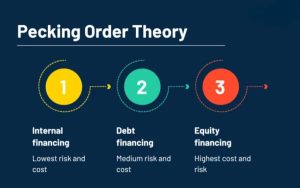
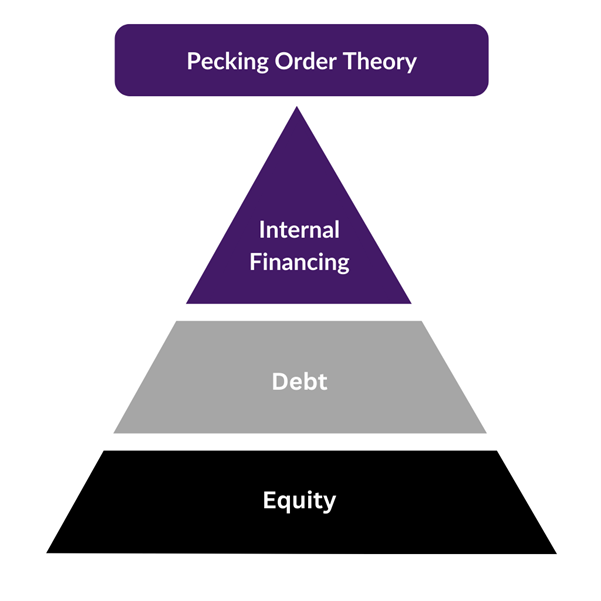
The pecking order theory comes up every time someone asks me why companies raise money the way they do. My first real encounter with this wasn't in a textbook. It was during a late-night board meeting at a mid-market manufacturing firm that needed about $40 million in working capital because their accounts receivable had ballooned unexpectedly after a major client changed payment terms. The CFO looked at the board and said we need to figure out where this cash comes from. The discussion that followed basically laid out everything the pecking order theory predicts, except nobody in the room knew it had a name. What the theory actually says The pecking order theory was formalized by Stewart Myers and Nicholas Majluf in 1984, building on earlier work by trade-off theorists who were uncomfortable with how little the existing models explained about real corporate financing behavior. The core idea is straightforward: companies have a hierarchy of financing preferences, and they move down that list in order when they need capital. At the top is internal financing, meaning retained earnings and depreciation. If internal funds aren't enough, the next step is debt. Equity issuance sits at the very bottom, last resort kind of situation.
The reasoning behind this isn't complicated, though it took academics a while to agree on it. It comes down to information asymmetry. Managers know more about the company's true prospects than outside investors do. When management issues new equity, the market assumes the worst because rational investors think a company wouldn't sell shares unless the stock was overvalued. That perception creates a negative signal. Debt doesn't carry the same problem. Lenders care about collateral and cash flow coverage, not whether the CEO secretly thinks the stock isundervalued. I remember analyzing a portfolio company around 2019 where the management team explicitly told me they would rather carry $15 million in short-term bank debt at 9 percent than dilute shareholders with a secondary offering. They were worried about the signal effect. The cost of debt was higher in that environment, sure, but issuing equity would have crushed the stock price by an estimated 12 to 15 percent on announcement day based on similar historical cases. They chose the expensive debt and avoided the equity. How it plays out in practice
When you look at actual corporate behavior across decades of data, the pecking order holds up reasonably well for mature firms. Large S&P 500 companies fund roughly 60 to 80 percent of their capital needs from retained earnings before touching external markets. When they do go external, debt issuance far outweighs equity issuance. The pattern reverses somewhat for startups and high-growth companies because they often have negative retained earnings by definition, but even then the tendency toward debt over equity when they can access it remains observable. One thing people miss is that the pecking order isn't a rigid rule. It's an empirical observation about behavior under normal conditions. When credit markets freeze, like in 2008, the whole hierarchy gets disrupted. Companies that would normally issue commercial paper or take bank loans found themselves unable to roll over short-term debt. They had no choice but to issue equity or raise money from alternative sources they would have avoided under normal circumstances. I saw several firms in that period fall back on asset sales and factoring receivables because the debt markets they depended on simply stopped functioning. The counter-intuitive part most guides skip
Get the Full Details
Here's something that doesn't get emphasized enough: the pecking order theory and the trade-off theory aren't mutually exclusive. They explain different things. Trade-off theory is about finding an optimal debt-to-equity ratio where the tax benefit of debt balances against the cost of financial distress. Pecking order theory is about the sequence companies choose when they need money, regardless of where their target ratio might be. A company can have a target debt ratio of 40 percent and still follow the pecking order. When internal funds run out, they issue debt until they hit that target. Only if they need more than that do they issue equity, which pushes the ratio below target, and then they accumulate retained earnings until they're back where they want to be. The pecking order describes the process. Trade-off describes the destination. Confusing the two leads to bad models. I worked through a case study a few years back with a healthcare services company that publicly targeted a 35 percent net debt-to-EBITDA ratio. Their actual issuance pattern over five years showed they issued equity three times and debt seven times in that window. On the surface that looked like they weren't following pecking order. But when I traced the timing, each equity issuance corresponded to a major acquisition that debt alone couldn't fund without breaching covenants. They were using equity to preserve headroom for future debt capacity, which is actually consistent with a sophisticated application of the theory rather than a violation of it.
Where it breaks down The pecking order theory has clear limitations. It assumes managers are rational and value-maximizing, which is a bigger assumption than it sounds. In practice, executive compensation tied to stock price can make managers avoid debt precisely because it depresses earnings per share, even when debt would be cheaper overall. Agency costs get ignored. The theory also struggles to explain why some companies maintain large cash reserves while simultaneously carrying significant debt, which seems contradictory to the idea that internal funds should be exhausted first. For small private companies, the pecking order is often irrelevant because their financing options are constrained by relationship banking rather than market access. A family-owned business isn't choosing between debt and equity based on signaling concerns. They're borrowing from the bank that's known them for twenty years or not borrowing at all. The theory was built to explain publicly traded firms in developed capital markets, and applying it universally leads to incorrect predictions.
What this means for analysis If you're evaluating a company's financing decisions, the pecking order gives you a baseline expectation. A firm consistently issuing equity in rising markets while hoarding cash in downturns is behaving in a way that contradicts the theory and warrants investigation. It might mean management is overly optimistic about valuations, or it might mean there are governance issues driving suboptimal capital structure choices. Conversely, if a company is rapidly accumulating debt without clear strategic justification, the pecking order alone won't tell you whether that's prudent or dangerous. You need to look at interest coverage ratios, debt maturity profiles, and covenant headroom. The theory describes the path of least resistance, not necessarily the path of optimal value creation.
The most useful application I've found is using it as a diagnostic tool rather than a predictive model. When financing patterns deviate from the expected hierarchy, those deviations usually point to something worth understanding, whether it's a temporary market dislocation, a specific strategic need, or misaligned incentives at the management level.