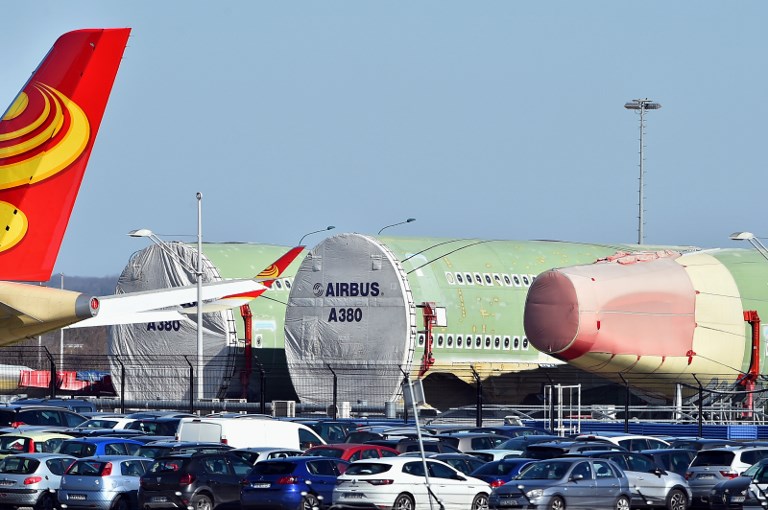
Why The A380 Was Never Going To Be Profitable On Its Own
I worked on route analysis for a major carrier for about twelve years, and we ran the numbers on the A380 so many times it became almost surreal. The thing nobody tells you is that the aircraft itself was fine. It was an engineering marvel. The problem was that the math simply never worked out at the gate level, and that disconnect between engineering brilliance and commercial reality is what makes the whole story worth looking at. The true cost isn't what you see in a press release. It's buried in the operational economics. Let me walk through how I actually calculated this stuff when I was doing it day to day, because the publicly available figures are always misleading. First, you have to separate the acquisition cost from the operating cost. That sounds obvious but most analyses conflate them. The A380-800 had a list price around 445 million dollars when it was current, though actual transaction prices were significantly lower due to bulk discounts and the fact that Airbus was desperate for launches. Emirates got the best deal by far because they ordered twenty-five aircraft. Everyone else paid more per unit relative to their order size.
What matters more is the cost per available seat kilometer, or CASK. That's the metric that determines whether a route makes money. Here's where it gets counterintuitive. The A380's CASK is actually lower than many widebodies on routes with sufficient demand. The engine burn per seat is competitive. The issue is that you need extremely high load factors consistently to make it work, and maintaining those load factors on an eight-hundred-seat aircraft in the modern era has become nearly impossible for most carriers outside of a handful of hub routes. I remember running a model for a potential A380 deployment on a transatlantic route that looked solid on paper. Eight hundred seats, high premium cabin yield, projected sixty-five percent load factor. The model showed profitability. What the model couldn't capture was that every time we tried to fill those premium cabins, passengers were choosing the competitor with more frequent departures and better connecting options. Frequency beats capacity every time on these routes unless you're in a position like Emirates where you control the hub entirely.
The Hidden Costs That Kill The Economics
Beyond the headline fuel burn and acquisition price, there are costs that most people don't factor into their mental math. Ground handling is significantly more expensive. You need double the gate space or a modified gate. Most airports had to build or retrofit gates specifically for the A380, and even then, the ground equipment is specialized and expensive. Aerial refueling truck configurations, heavier landing gear maintenance cycles, and the simple fact that you can't park this aircraft at most gates without special arrangements adds real cost per turn. Maintenance is another area where the numbers get ugly. The A380 has four engines, which means four engine health monitoring systems, four thrust reversers, and proportionally more consumable parts to replace. The landing gear is massive and the tires alone cost more than an entire regional jet's landing gear assembly. I once saw a document showing that a single main landing gear tire change on an A380 could cost upwards of eighty thousand dollars when you factor in the labor, the specialized equipment required, and the aircraft off-block time.
Get the Full Details

Then there's the crew cost angle. You need larger flight decks, more cabin crew, and the certification and training pipeline for A380-qualified pilots and mechanics was expensive to maintain even as orders dwindled. When you're operating a fleet of fewer than two hundred aircraft worldwide, spreading those training costs across a small number of operations is inefficient by definition.
What Actually Made It Work For Anyone
Emirates made it work, but not because the A380 was inherently profitable. They made it work because they structured everything around it. Dubai is a perfect hub geography. They have no competing domestic airlines draining their passenger base. They positioned the A380 as a status symbol that attracted corporate contracts and premium leisure traffic. And crucially, they financed the aircraft in a way that minimized balance sheet impact. Singapore Airlines also found a niche with their ultra-long-haul A350-900ULR replacement strategy, though they ultimately moved away from the A380 on most routes. Their Singapore to Sydney service was one of the few routes where the A380 made genuine economic sense because the demand was consistently above six hundred passengers on a nonstop basis, which is exceptionally rare. When I evaluated whether a carrier should operate the A380, I used a threshold model. If the route couldn't consistently support six hundred plus passengers at yield levels above eighty percent of economy fare, the aircraft was going to lose money. That left very few routes in the world that qualified. Most carriers found maybe three or four routes out of their entire network that met that bar, which is why the aircraft was always going to be a niche solution within any fleet.
The Residual Value Problem
This is the part that really caught people off guard. When Airbus ended production in 2021, the residual value of A380s collapsed faster than anyone predicted. Leasing companies took massive haircuts. Aircraft values dropped to roughly ten to fifteen percent of their original acquisition price within a few years of the production halt. That's unusually steep even for a discontinued aircraft type. The reason is structural rather than cyclical. There aren't enough airports that can handle the A380 to create a liquid secondary market. Airlines that want to expand are buying Boeing 777-300ERs and 787-9s because those aircraft fit everywhere. An A380 is a solution to a problem most carriers don't have anymore. The pandemic accelerated this trend by making every airline reconsider capacity discipline, and the A380 became the poster child for the wrong kind of capacity. I spoke with a leasing analyst who had to write down an entire A380 portfolio by about sixty percent in a single quarter. He said the worst part wasn't the financial hit, it was that there was literally no buyer pool. They'd reach out to three or four airlines maximum and get polite declines. The secondary market for this aircraft is essentially nonexistent, which means the total cost of ownership is much higher than the acquisition price suggests.
How I Actually Evaluated A380 Routes In Practice
When we did this work, I built spreadsheets that tracked revenue per available seat meter against the full operational cost picture. The formula looked something like this: you take your expected yield per seat, multiply it by your projected load factor, multiply by available seat kilometers, then subtract fuel cost, landing fees, handling, crew, maintenance reserves, and capital charge. The capital charge is the piece people always underestimate because they forget to include the cost of tying up that much capital in an asset that depreciates rapidly once the production line closes. A realistic example. We evaluated London Heathrow to New York JFK with an A380 configuration of four hundred and seventy-one seats in a three-cabin layout. At a projected sixty percent load factor and average yield of two hundred and forty cents per revenue passenger kilometer, the route generated approximately one point eight million dollars in daily revenue. The operating cost came to about one point six million dollars per day when you included everything, leaving a margin of roughly one hundred twenty thousand dollars per day. That looked good on paper until you accounted for the fact that the same aircraft on a Boeing 777-300ER with two hundred and ninety-six seats could achieve seventy-two percent load factor and generate similar revenue with lower operating costs and significantly better residual value protection. The 777 version ended up being more profitable despite the lower capacity because the load factor was higher and the aircraft retained three times the resale value. That's the paradox of the A380. It was designed to be efficient per seat, but the market shifted toward efficiency per departure, and that's where the smaller twin-engine widebodies won.
What This Means Going Forward
The A380 fleet is slowly being retired. Qatar Airways and Korean Air are among the carriers still operating them on select routes, but even they are planning phase-outs. The airframes themselves are in good condition. These are young aircraft with plenty of flying left. The question is whether there will be an operator willing to pay enough to make it worth their while. For carriers evaluating secondhand A380s, the opportunity exists only if you have a hub strategy that genuinely requires eight hundred-seat capacity and you can maintain load factors above seventy percent consistently. That's a very narrow set of conditions. Most carriers are better served by operating larger twins on high-density routes and using the A380 only where no alternative exists. The engineering achievement is undeniable. The A380 changed what was possible in commercial aviation. But the economics were always a compromise between what was technologically impressive and what the market actually needed, and in the end the market chose a different answer.