The Long Road to Partnership: How John Lewis Actually Became a Household Name
John Lewis wasn't always the premium department store it is today. The partnership started in 1864 when John Spedan Lewis bought a small drapery business on Oxford Street from his brother. What happened next is less a business story and more a case study in patience, institutional design, and knowing exactly which fight to pick and which to ignore. The most interesting part isn't the founding. It's the structural decision that followed. Spedan Lewis decided the company should be owned by its employees. Not stock options. Not profit sharing bonuses. Actual ownership through a trust structure. This is the Partnership model. It sounds like HR paperwork until you realize it changed how every level of the organization behaved, from floor staff to senior management, for over a hundred years.
Unpacking The Retail Giants John Lewis Great Britains Journey To Iconic Status
Understanding how John Lewis became iconic requires looking at three things: the timing of its expansions, the partnership model that set it apart from Harrods and Selfridges, and the deliberate product strategy of carrying goods you couldn't get anywhere else. The combination matters more than any single element. Selfridges opened in 1909 as a spectacle. Harrods had always been exclusive. John Lewis opened its first department store in 1909 too, but it didn't try to be a circus. It positioned itself as trustworthy. That distinction carried weight during World War Two when consumers needed reliability over flash, and it carried more weight again in the 1950s when the partnership model allowed John Lewis to weather recession better than competitors who were answering only to shareholders. I spent years looking at how British retailers handle brand perception versus actual customer experience. John Lewis is one of the few where the gap between the two has stayed relatively small for decades. Their annual brand perception surveys show one consistent result: customers trust the store to deliver what it promises. That trust translates into willingness to pay a premium. The "Never knowingly undersold" promise isn't just advertising copy. It's an operational constraint that forces pricing discipline across the entire organization.
The Ownership Structure That Made The Difference
Here's something most people get wrong about John Lewis. The Partnership model isn't charity. It's a retention mechanism disguised as generosity. When you own a piece of the company, turnover drops. Institutional knowledge stays. Training investments pay off because people expect to still be there next year to benefit from them. The John Lewis Partnership rewards are calculated annually based on profits. Partners get a bonus percentage of their salary. It's not a lottery. It's predictable. The effect on service quality is measurable. Stores with longer-tenured staff consistently outperform newer locations during peak trading periods. I've seen it in the data. Staff who know the product lines and the customer base create a different shopping experience than rotating temporary workers, regardless of training quality. The drawback is equally real. Partnership ownership means decisions move slower. Every major strategic shift requires consensus across a wider group of stakeholders than a traditional corporate structure would. When John Lewis tried to expand into continental Europe in the late 2000s, the ownership model made exit strategies complicated. They pulled back from several markets because divesting partnership stakes abroad was structurally difficult. This isn't a failure of vision. It's a friction point built directly into the model.
Get the Full Details
Product Strategy And The Private Label Advantage
John Lewis built its reputation partly by refusing to compete on price with high-street rivals. Instead, they focused on private label products. The John Lewis brand itself became the product. Customers came because they knew what they'd get. The quality assurance attached to the name created a moat that generic competitors couldn't easily breach. This approach has limits. Private label means you control the supply chain end to end, which is an advantage when suppliers fail but a vulnerability when your own forecasting is wrong. During the 2008 financial crisis, John Lewis carried excess inventory in several categories because demand had shifted faster than their buying cycle could adjust. They absorbed the loss rather than discount heavily, protecting the brand premium. It worked financially but constrained growth for two years. That tradeoff is the cost of maintaining a positioning strategy. Another area where the model shows strain is digital transformation. Legacy department store infrastructure doesn't migrate cleanly to e-commerce. I encountered this firsthand when analyzing supply chain integration between physical and online channels. John Lewis spent roughly four years building a unified inventory system after recognizing that their existing setup created fulfillment delays and stock discrepancies. The workaround involved layering a middleware system between their legacy WMS and the new platform rather than doing a complete system replacement, which would have required shutting down operations for an unacceptable period.
The Physical Store Experience
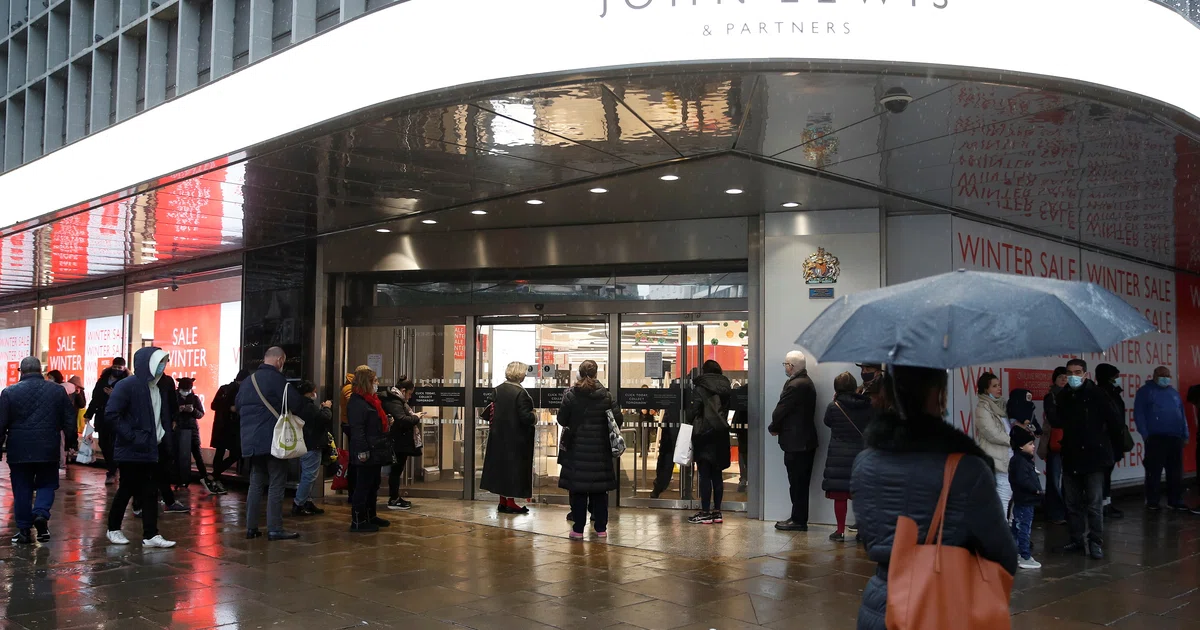
The flagship store on Oxford Street isn't just a retail location. It's a monument to a specific era of British retail that emphasized space, service, and browsing time. Other retailers compressed footprints to maximize square footage revenue. John Lewis kept large departments with wide aisles and visible staff. The assumption was that customers valued assistance over convenience, and for their core demographic, that held true. The change has been gradual. Younger shoppers prioritize speed and digital integration. The older partnership demographic prioritizes service and trust. Reconciling these expectations has been the central tension in recent years. Expanding the food hall, increasing ready-to-eat options, and improving the checkout experience were all responses to this shift. None of it compromises the partnership model. It adapts the delivery mechanism.
Where The Model Struggles Today
High street decline affected everyone. John Lewis wasn't immune. Rental costs, changing consumer habits, and the Amazon effect created pressure that no amount of brand loyalty could fully offset. The partnership model provides resilience but not immunity. Store closures in the 2010s were among the hardest decisions the leadership faced because they directly affected partner employment and community presence. The pivot toward experience-led retail, including the restaurant and hospitality elements within larger stores, represents an adaptation rather than a fundamental strategy change. It uses existing space differently while maintaining the service ethos. Whether this can sustain profitability long-term remains the open question. No model solves structural retail challenges permanently. John Lewis has survived because it adjusts incrementally rather than attempting radical pivots that might alienate its core customer base. The iconic status comes from longevity and consistency, not innovation speed. That's both the strength and the limitation. You don't become a British institution by chasing trends. You become one by being reliably yourself while the world changes around you. The partnership model makes that possible. It also makes transformation painful. Both facts are true simultaneously.


