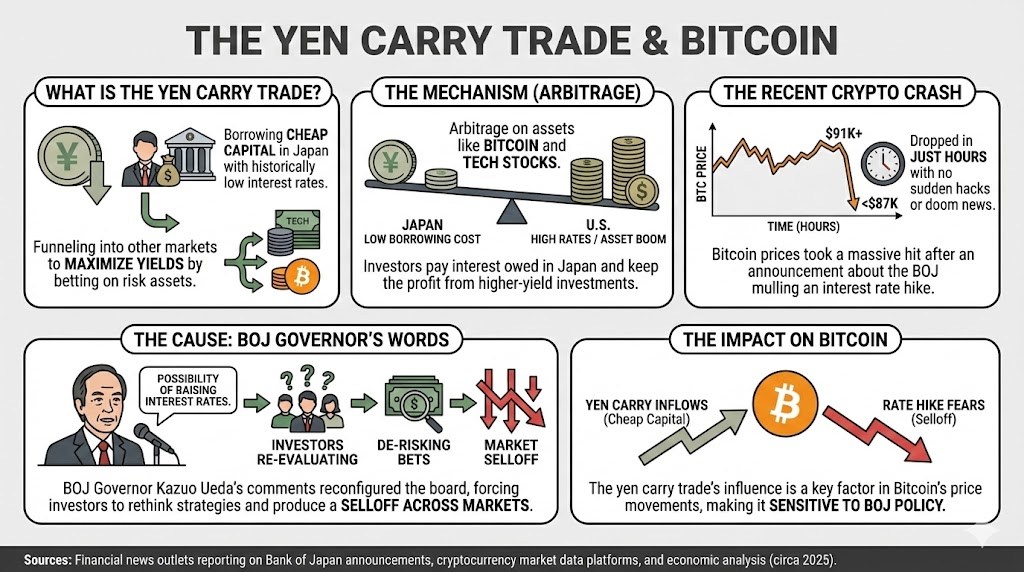
The Mechanics Before The Terminology
You borrow yen at near-zero interest, convert it to a higher-yielding currency, and park it in bonds or deposits that pay three to five percent. The spread is your profit, assuming exchange rates stay flat. That is the textbook version. The actual execution involves transaction costs, roll yields, and the constant risk that the yen strengthens enough to wipe out months of accumulated yield in a single session. I have been running carry trades across yen,Australian dollars, and Brazilian reais for over a decade. The structure looks simple on a spreadsheet. In practice, it is a exercise in managing tail risk while collection tiny positive carries that evaporate during market stress. One specific problem that kept coming up for me involved the timing of the BOJ policy shifts. During the 2024 period when the Bank of Japan began normalizing rates, I had several yen-funded positions that appeared stable on paper. The carry was positive. The spreads were healthy. Then the yen spiked roughly twelve percent against the dollar over three trading days. My unrealized losses on the FX leg exceeded the cumulative interest income I had collected over eighteen months. The workaround was not dramatic. I started using tighter implicit stop-outs based on yen volatility regimes rather than absolute rate levels. When the yen implied vol jumped above certain thresholds, I reduced gross exposure by about forty percent regardless of how attractive the carry still looked on paper. This cut my downside significantly without requiring me to predict BoJ moves.
Unpacking The Japanese Yen Carry Trade A Simple Guide
The Japanese yen carry trade has existed in various forms since the late nineteen nineties when the BoJ kept policy rates near zero following the asset price collapse. Investors borrowed in yen because the funding cost was effectively nothing. They then deployed those funds into currencies and assets offering materially higher returns. The appeal was straightforward. You collect the spread. You do not need the underlying asset to appreciate. You just need the yen to not appreciate faster than the yield you are earning. The core components are the funding currency, the target asset, the swap or conversion mechanism, and the holding period. The funding currency is the yen. The target asset can be anything from US Treasuries to Australian bank deposits to emerging market corporate bonds. The swap mechanism is typically executed through FX forwards or spot conversions with a simultaneous forward hedge if you are trying to lock in the spread. The holding period determines whether you are trading the yield curve dynamics or simply collecting income over quarters or years. What most beginners miss is that the carry trade is not a static strategy. It is a dynamic balance between positive yield and negative roll costs when the forward points move against you. In a normal upward sloping yield curve environment, the higher rate currency trades at a forward discount, which means rolling your hedge or refinancing your position gradually erodes your returns. This erosion is often smaller than the headline spread suggests. Over a twelve-month period, the net carry after roll costs might be closer to two percent instead of the four percent you calculated initially.
Another counter-intuitive point involves the relationship between carry trade profitability and global risk sentiment. The strategy tends to perform well during periods of low volatility and stable risk appetite. When stress hits, the yen strengthens as a funding currency repay accelerates and investors unwind positions simultaneously. This is not a theory. It happened in March twenty twenty when yen carry trades were aggressively flattened across institutional portfolios. The yen appreciated sharply and many carry trade profits reversed within days. The structural problem is that carry trade positions are heavily concentrated and often correlated. When unwinds happen, they happen fast and they happen together. Setting up a basic yen carry trade requires a few concrete steps. You open a margin or prime brokerage account that offers FX lending capabilities. You borrow yen at the prevailing overnight rate, which during much of the past decade has been between zero and point one percent. You convert the proceeds into your target currency at spot. You purchase the yielding asset, whether that is a government bond, a certificate of deposit, or a money market fund. You then monitor the spread between your asset yield and your borrowing cost, adjusted for any hedging expenses and transaction costs. The math is simple enough. If you borrow yen at point zero five percent and earn four percent on a US Treasury note, your gross carry is three percent minus ninety-five basis points. Transaction costs for a standard FX conversion and bond purchase typically run between five and fifteen basis points depending on size and execution method. After costs, your net carry might be around two point eighty-five percent annualized. On a one hundred million dollar position, that translates to roughly two point eight five million dollars per year before tax and financing complications.
Get the Full Details

The complications arrive quickly. Tax treatment differs depending on whether you are a US person, a Japanese resident, or a non-resident institutional investor. Withholding taxes on bond interest can reduce your effective yield by fifty to one hundred basis points. Funding rate changes, especially when central banks move, can narrow or eliminate your spread almost overnight. In 2024, several major pension funds and hedge funds reported that yen funding costs ticked up from near zero to around point five percent or higher as the BoJ ended negative rate policy. That single change cut carry trade returns roughly in half for positions that were not hedged against rate risk. There are scenarios where this entire approach breaks down completely. If the yen strengthens significantly while your target asset depreciates or stagnates, you face a double hit. The currency loss compounds against the narrowing yield spread. This is not rare. During periods of yen appreciation driven by risk aversion, carry trade investors have lost ten to twenty percent of their notional value within weeks while simultaneously losing the yield advantage. The strategy is not designed to survive those episodes. It is designed to profit during calm periods and require active management or exit during turbulent ones. A more sophisticated version of this trade involves using currency hedges to isolate the pure yield differential. You enter into a forward contract that locks in the exchange rate for the duration of your position. This eliminates FX risk but also eliminates the possibility of gaining from a favorable currency move. The cost of the hedge is embedded in the forward points. In most recent years, the hedge cost has been negative for yen funding because the interest rate differential favors the investor, meaning you actually get paid to hedge. But this dynamic flips when yield curves invert or central banks diverge rapidly, which is exactly when the carry trade becomes most dangerous.
The practical reality is that carry trades require ongoing monitoring. They are not set and forget strategies. Position sizing matters. Most professional investors limit carry trade exposure to ten to twenty percent of their total portfolio because the tail risk is disproportionate to the steady income stream. Diversification across multiple funding currencies and target assets reduces but does not eliminate correlation risk. When global markets sell off, nearly all carry positions face pressure simultaneously regardless of how diversified the book appears on a normal day. If you are considering this approach, the first thing to evaluate is your capacity to absorb sudden unrealized losses without being forced to close positions at the worst possible time. Carry trades look stable until they do not. The yield income provides a false sense of security during calm periods. The moment volatility increases, the strategy can generate losses faster than the positive carry can recover them. Understanding this asymmetry is more important than understanding the mechanics of the trade itself.