What Actually Happens When These GSEs Enter The Picture
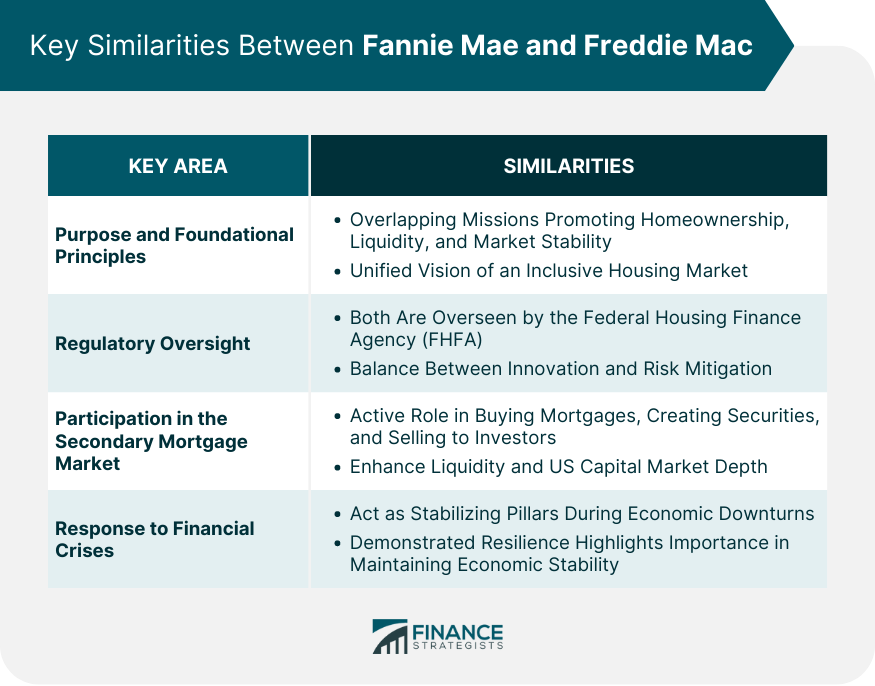
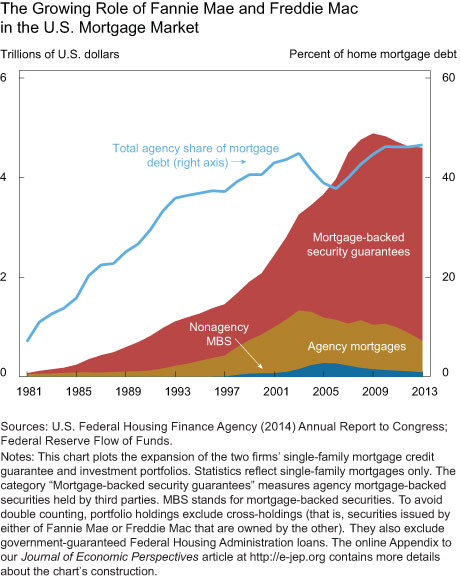
If you've ever wondered about Unpacking The Enigmatic World Of Fannie Mae Freddie Mac Whats The Deal, you're not alone. The conversation around them is either overly technical or wildly inaccurate. Neither helps. I'll walk through what these entities actually do, where things go wrong in practice, and what most people miss about how they operate. Fannie Mae and Freddie Mac are government-sponsored enterprises. That means they exist in a space between private ownership and public purpose. They were created by Congress in 1938 (Fannie) and 1970 (Freddie) to add liquidity to the mortgage market. When a bank issues a home loan, it typically bundles those loans together into mortgage-backed securities. Fannie and Freddie buy those bundles, guarantee the payments, and then hold or sell the securities to investors. The guarantee is what matters. They promise investors that principal and interest will be paid even if the underlying borrowers default. That guarantee backstops roughly half of the US residential mortgage market. Not all of it. Just about fifty percent, give or take depending on the quarter and refinance volume.
Here's what most people don't realize: Fannie and Freddie don't actually lend money directly to homebuyers. They're secondary market players. Your local bank or credit union makes the loan. Then Fannie or Freddie buys it from them. The original lender usually services the loan afterward, collecting your payments and forwarding them along the chain.
How The Conforming Loan Limit Actually Works In Practice
The conforming loan limit is the maximum amount Fannie and Freddie will purchase for a standard single-family home. In 2024, that was $766,550 for most of the country. Higher-cost areas can go up to around $1,142,575. Loans above that threshold become jumbo loans and follow different rules, different pricing, and different underwriting standards. I ran into a specific problem last year with a client in Boulder, Colorado. The property appraised at exactly the conforming limit plus about twelve thousand dollars. Their loan came back as a jumbo because the appraisal gap pushed it over. The seller agreed to a concession that would have brought it back under, but the timing was tight. We ended up restructuring the loan to keep it conforming by adjusting the loan-to-value calculation using the contract price instead of the appraised value. Worked. Barely. The key was getting the purchase contract to reflect the agreed-upon price before the appraisal locked in. Missing that window would have cost the borrower roughly forty basis points on their rate. The conforming limit isn't static. It adjusts annually based on changes in the Case-Shiller home price index. If home values spike, the limit goes up. If they flatline or drop, it stays where it was the previous year. There's no mechanism to reduce it.
Get the Full Details
What Nobody Tells You About The Conservatorship
Both Fannie Mae and Freddie Mac entered conservatorship in September 2008. The Treasury Department took over. They've been under federal control ever since. The official line is that it was temporary. It hasn't been. The Preferred Stock Purchase Agreements between Treasury and the GSEs give the government the right to inject capital as needed and receive a statutory dividend on preferred stock holdings. Here's the uncomfortable detail: in recent years, the GSEs have been paying dividends to Treasury that exceed what they'd technically owe under the original terms of those agreements. The net worth sweep, as it became known, effectively made them profit conduits for the government during profitable periods. That structure has been challenged in court. The legal proceedings have moved slowly. Nothing has changed materially in over a decade. The practical implication for anyone in the mortgage space is that policy risk is always present. Reform legislation gets introduced every Congress. Most of it goes nowhere. But the mere possibility affects pricing, sentiment, and how institutions plan long-term. It's a background condition you learn to factor in rather than something you can hedge against directly.
The Pricing Difference Between Agency MBS And Non-Agency
Agency mortgage-backed securities carry the explicit guarantee of Fannie, Freddie, or Ginnie Mae. That guarantee changes everything about risk pricing. When you're comparing yields, an agency 30-year fixed at 3.75% and a non-agency portfolio loan at 6.5% aren't comparable in the way a casual investor might assume. The non-agency loan carries credit risk. The agency security doesn't, in the sense that the government backstop makes default on the security itself virtually impossible. What beginners miss is that the guarantee comes with strings. Fannie and Freddie have strict eligibility requirements. The loans must meet their underwriting guidelines, documentation standards, and credit score minimums. A borrower with a 620 credit score and thirty percent down might qualify for a conforming loan. That same borrower with slightly different debt ratios might not. The guidelines shift. They always have and always will. During the pandemic, when rates dropped below three percent, Fannie and Freddie paused certain investor program options and tightened documentation requirements temporarily. Lenders who weren't tracking those updates in real time lost deals or made compliance errors. Staying current on the Fannie Selling Guide and Freddie Seller/Servicer Guide isn't optional. It's the baseline.
Why The Dual-Tracker System Exists
Having two GSEs instead of one was deliberate. When Fannie Mae became too dominant, Congress created Freddie Mac in 1970 to introduce competition. The theory was sound. The outcome has been more complicated. Both entities now operate under nearly identical guidelines and pricing structures. The competitive difference is marginal at best. You'll see small variations in price locks, fee structures, and investor program availability, but they converge quickly in normal market conditions. The real difference emerged during stress periods. In March 2020, when markets seized up, Freddie Mac moved slightly faster on certain program updates. Fannie Mae was methodical. Both reached the same destination. If you're processing high volume, having relationships with both matters because one will always be ahead on specific product rollouts.

The Taxpayer Exposure Question
Every few years someone publishes a figure showing estimated taxpayer exposure to Fannie and Freddie. These numbers range widely depending on methodology. The Congressional Research Service and the Government Accountability Office produce the most reliable estimates. The figure you should care about isn't the total exposure number. It's whether the GSEs are paying for their own guarantee through the uniform servicing fee and guarantee charge structure. They are. As of the most recent quarterly reports, both entities are generating positive economic income. That means the fees they collect from investors exceed the cost of guarantees and operations. When they're in that position, taxpayer exposure is theoretical rather than actual. The risk re-emerges only during severe downturns when default rates spike across the board and guarantee claims outpace fee income. 2008 was exactly that scenario. We haven't seen anything like it since.
What This Means For A Regular Borrower
Most homebuyers never interact with Fannie or Freddie directly. Their loan gets sold into the secondary market. What affects you is the conforming loan limit, the availability of down payment assistance programs, and the pricing environment shaped by GSE activity. When the GSEs are profitable and confident, rates tend to be more competitive. When uncertainty rises around their structure, spreads widen and borrowing costs increase slightly. If you're shopping for a mortgage, asking whether a loan will be sold to Fannie or Freddie is reasonable. Most conforming loans will be. The alternative is a portfolio loan held by the originating bank, which typically comes with a higher rate because the bank is absorbing risk it could otherwise offload. The difference is usually twenty-five to fifty basis points depending on market conditions. The whole system is larger and more interconnected than most people realize. It runs on guidelines that change quarterly, pricing models that adjust daily, and a legal framework that hasn't fundamentally evolved since 2008. Understanding the mechanics matters less than understanding that the mechanics exist and that they'll keep shifting regardless of what anyone says about reform.