The Simple Truth About Enterprise Value
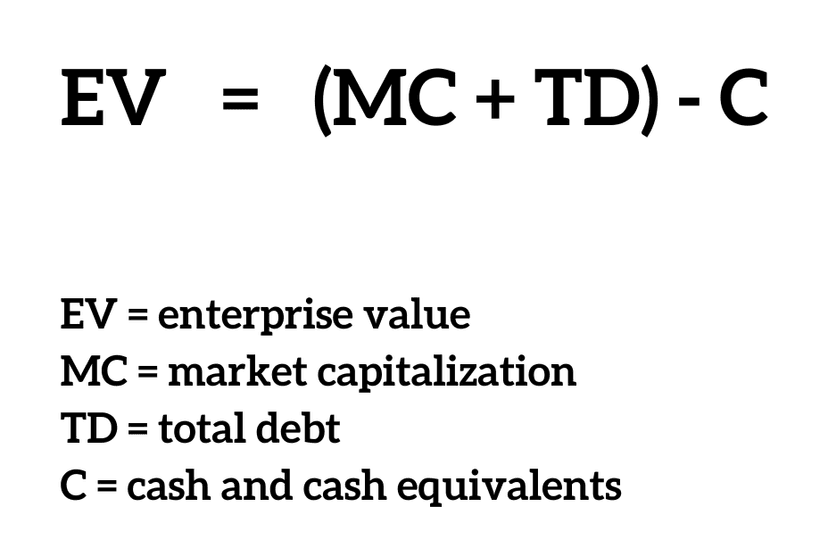
Most people I talk to still look at market cap as the primary way to judge if a stock is cheap or expensive. That approach works fine until you actually try to understand what it means when one company trades at 8x earnings and another at 25x, both in the same sector with similar growth rates. The difference usually comes down to how much debt they're carrying, how much cash they sit on, and whether they have other claims on their capital structure that market cap completely ignores. Enterprise value is essentially the total cost of buying a company if you were to acquire it today. You take the market cap, add total debt, add minority interest, add preferred shares, and then subtract cash and cash equivalents. That gives you a number that reflects what a real buyer would actually pay, not just what the stock market says the equity is worth on a given day. I spent about six months working through these valuations manually for a boutique research shop back around 2014. One of the first edge cases that absolutely threw me off was a mid-cap industrial company with a seemingly attractive EV/EBITDA ratio compared to its peers. The problem was that the company had a massive pension liability sitting on its balance sheet that standard EV calculations don't properly account for unless you dig into the footnotes. The debt number looked normal, but the underfunded pension obligation was effectively another form of leverage that would come due over time. I ended up adjusting the EV by adding the pension shortfall as a proxy for hidden debt, which bumped the enterprise value up by roughly 22 percent and completely changed the investment thesis. If you're doing this kind of analysis regularly, you need to learn to spot these off-balance-sheet items early rather than relying on whatever your screening tool gives you.
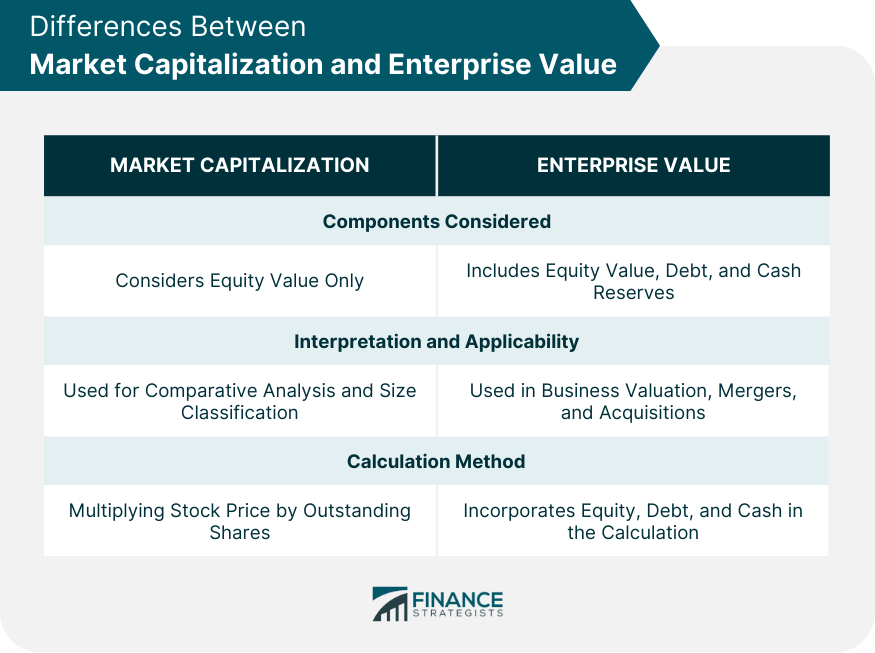
Here's another thing most tutorials don't mention clearly. When you're dealing with companies that have significant minority interests, like subsidiaries where the parent owns less than 100 percent, the standard EV formula can understate the true economic claim on the business. You have to add the minority interest to enterprise value, and many retail investors skip this entirely. It's a small adjustment in dollar terms for some companies, but for others in conglomerate structures it can be material enough to swing a valuation conclusion. Market cap tells you what the equity slice of the pie is worth. EV tells you the value of the entire pie, including what creditors and other stakeholders have a claim on. Those are two fundamentally different numbers and they diverge the more leveraged a company becomes. A highly indebted company and a cash-rich company can have identical market caps but wildly different enterprise values. That divergence is where the actual signal lives. One practical workflow I settled into involves pulling the balance sheet from the latest annual report, making sure you're looking at the consolidated statements and not just the parent company file. Add long-term debt and short-term borrowings together. Check for any convertible securities or preferred stock listed separately. Subtract unrestricted cash and short-term investments. Then compare the resulting EV to EBITDA, free cash flow, or revenue depending on the industry. For capital-intensive businesses, EV/EBITDA is the standard multiple. For software companies with minimal debt and high cash balances, the difference between EV and market cap is usually small enough that either metric works, though EV still gives you a slightly more honest picture during merger scenarios.
The main failure mode for this approach is when you apply it blindly across industries. EV/EBITDA works reasonably well for manufacturing, industrials, and telecom. It falls apart somewhat for financial services where debt is the core operating asset rather than a financing decision. Banks and insurance companies require a completely different framework, and using EV multiples on them will give you misleading comparisons against non-financial peers. I learned that the hard way when a colleague tried to value a regional bank using standard EV methodology and came back with a number that was completely detached from reality. Financials need book value and price-to-book ratios, not enterprise value multiples. Another limitation worth noting is that EV is a snapshot in time. It relies on current market cap, which fluctuates daily based on sentiment, macro news, and trading volume. A negative earnings report can drop the market cap by 15 percent overnight while the debt and cash positions remain unchanged, which artificially compresses the enterprise value and makes the company look cheaper without any operational improvement. This is why serious analysts smooth EV with trailing EBITDA or use an average market cap over a 30 to 60 day window rather than relying on a single day's price. If you want to run these calculations yourself without building something from scratch, spreadsheets are perfectly adequate. Set up columns for market cap, total debt, minority interest, preferred equity, and cash. Most financial data providers offer CSV exports that you can pull directly into Excel. The actual calculation takes less than five minutes per company once you have the data source set up. The time investment is in verifying the numbers, reading the footnotes for off-balance-sheet items, and understanding the business model well enough to know which valuation multiple actually applies.
Get the Full Details
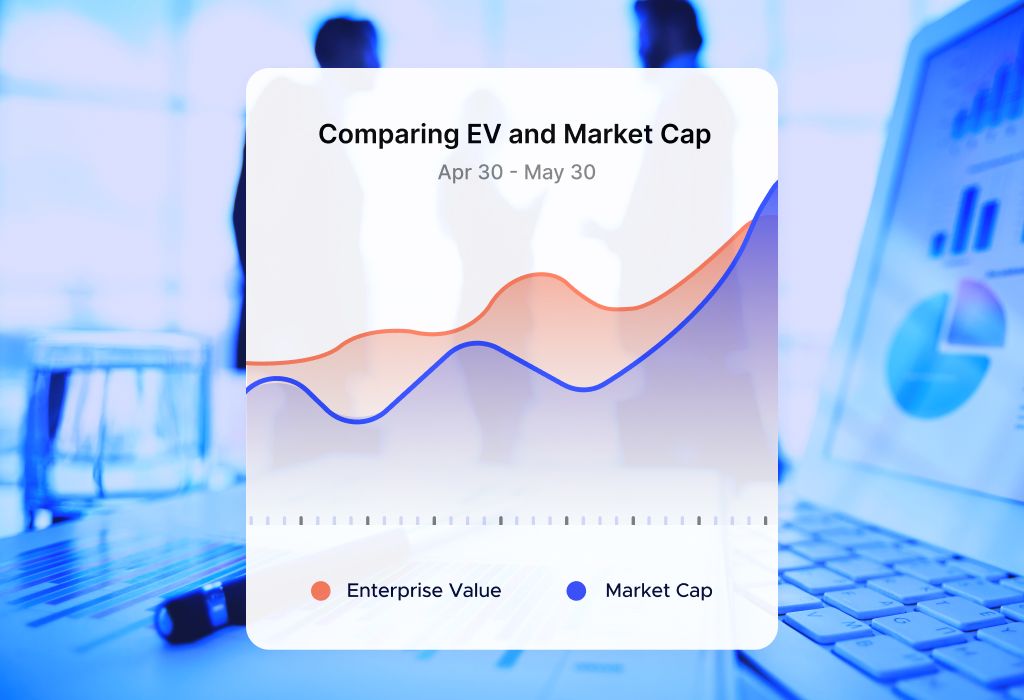
The reason this matters in practice is that you'll encounter situations where market cap alone sends you the wrong direction. A company might look expensive at 20 times earnings when you only consider equity value, but once you factor in that it carries almost no debt and sits on a large cash balance, the enterprise value multiple drops to something far more reasonable. The reverse is also true. A cheap-looking stock on a market cap basis can turn out overvalued once you account for a heavy debt load. Getting into the habit of checking both numbers before making any kind of comparative assessment saves you from a lot of obvious mistakes.