Understanding American Express Fee Structures: A Merchant and Consumer Guide
American Express fees are among the highest in the card industry, and most people don't fully grasp what they're paying or receiving. As a merchant who has processed Amex cards for over a decade, I can tell you the fee landscape is more complicated than a simple percentage. It varies by card type, transaction method, and volume tier. Let me walk through what's actually happening with these fees and how to work within the system. Amex operates differently than Visa and Mastercard. With those networks, the card issuer and the network are separate entities. Amex is both. This vertical integration means they control the entire chain, which also means their fees reflect that monopoly power. The merchant discount rate — the fee you pay when a customer swipes — typically runs between 2.5% and 3.5% for Amex, compared to roughly 1.5% to 2.5% for Visa and Mastercard on comparable transaction sizes. There's no single published rate. Your actual cost depends on your processing tier, whether you qualify for commercial pricing, and the specific Amex product being used. A regular Green Card might sit at one end of the spectrum while a Delta SkyMiles Platinum Card could push you toward the other end. Corporate cards carry even higher rates, sometimes exceeding 4% on certain transaction types.
Unmasking The Hidden World Of Amex Fees What You Need To Know
Most merchants look at their monthly statement and see one blended percentage. The reality is far messier. Inside that single number are multiple components that get combined differently depending on your processor. The base interchange fee passes through to Amex, but then there are network assessments, program fees, and various surcharge adjustments that your processor layers on top. When you don't understand the breakdown, you can't negotiate effectively. I spent years underpaying on Amex transactions because my processor was categorizing certain high-value cards at lower commercial rates that I didn't qualify for. It wasn't until I audited my statements line by line against the published Amex rate sheet that I caught it. The fix took about three weeks of back-and-forth with my acquiring bank, and I recovered roughly $2,400 from the previous quarter. The key was getting the raw assessment data from the processor rather than accepting the summary figure.
Annual Fees and Cardholder Programs
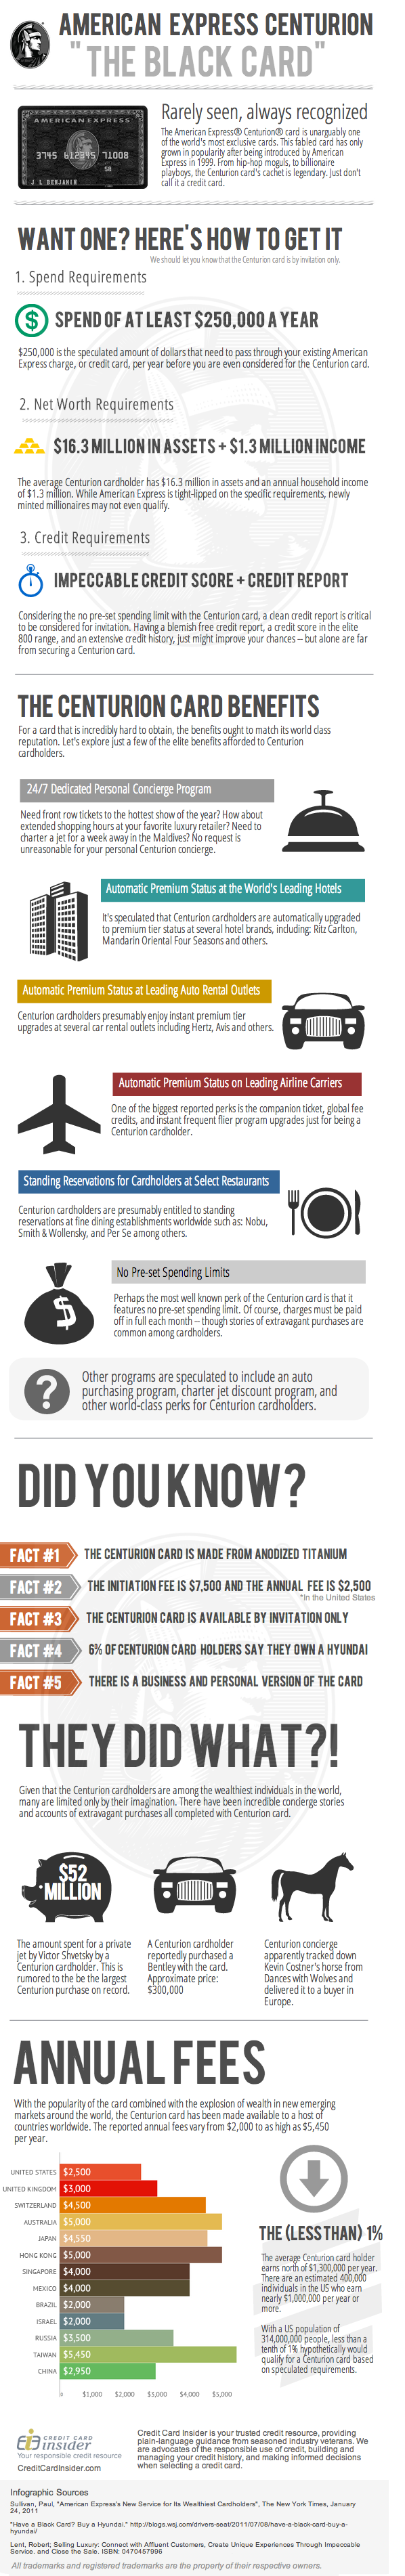
From the consumer side, Amex annual fees have climbed significantly across most of their card lineup. The Gold Card runs around $325, the Platinum Card sits at $695, and their co-branded travel cards have followed similar trajectories. These fees fund the rewards programs that keep customers loyal, and they've been effective — Amex retention rates consistently outperform Visa and Mastercard. What consumers often miss is that the fee isn't arbitrary. The higher-tier cards like the Platinum come with credits that can offset the cost if you actually use them. The $200 airline fee credit, the $200 Hotel Credit, the $189 Saks Fifth Avenue credit, and others add up quickly for people who fly and stay in hotels regularly. But I've seen plenty of people pay the full annual fee without touching a single credit. In those cases, the card is actively costing them money every year.
Get the Full Details

Chargeback and Dispute Fees
This is where things get ugly for merchants. Amex chargeback fees sit at $25 per dispute, and unlike some other networks, they tend to side with the cardholder more aggressively. The dispute process itself is also less merchant-friendly — you often have less time to respond and fewer pathways to present your case. I had a merchant account client lose a dispute over a clearly documented digital delivery simply because the timing on their evidence submission was off by hours. The fee was $25, but the chargeback amount was $340, and the appeal window had already closed. For high-volume Amex merchants, these fees add up fast. A single bad month with elevated chargeback activity can erase weeks of margin on Amex transactions alone. The workaround I recommend is proactive customer service escalation before a dispute gets filed. A refund offered directly to a frustrated customer almost always costs less than fighting a chargeback through Amex's system.
Foreign Transaction Fees and Cross-Border Pricing
If you process international cards, Amex foreign transaction fees stack on top of your base rate. We're talking an additional 1% to 1.5% on top of whatever discount rate you're already paying. For merchants doing significant cross-border business, this can make Amex genuinely unprofitable on certain transactions unless you implement a proper surcharge that complies with local regulations. First, get your statements in raw form. CSV or detailed PDF with line-by-line fee breakdowns, not the summary statement your processor sends you by default. Second, compare your effective rate against the published Amex rate sheet for your category code. If your rate is more than 30 basis points above the published interchange, something is off. Third, consider surcharging where legally permissible. Most states allow it, and it shifts the cost to the customer rather than absorbing it into your pricing. Fourth, renegotiate annually. Processor loyalty doesn't get you better rates — it gets you forgettable rates. Amex fees aren't going away. The network has too much market share in the premium card segment to offer deep discounts to merchants. The smart approach is to understand exactly what you're paying, identify where your processor is overcharging, and structure your acceptance strategy accordingly. The merchants who win with Amex aren't the ones who complain about the fees — they're the ones who know every component of their statement and fight for every basis point they can recover.