The Real Mechanics Behind Institutional Market Influence
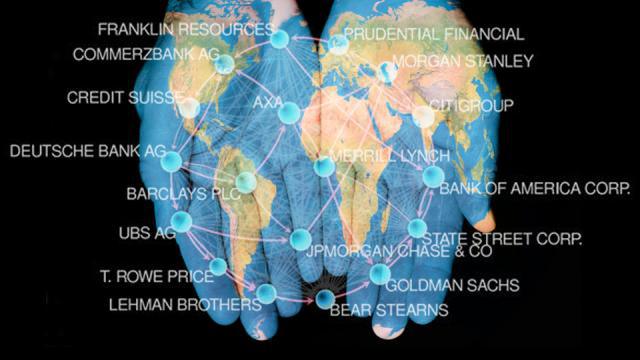
Most people talking about corporate dominance are guessing. They see stock buybacks, merger announcements, and lobbying reports and connect the dots themselves. I spent twelve years in macro strategy at a mid-tier firm, and then another eight advising institutional allocators. What I learned doesn't fit into any single framework. There isn't one lever that corporate power pulls. There are dozens, and they operate on completely different time horizons. The phrase "250 trillion" usually refers to the total market capitalization of the world's publicly traded companies combined. It's a loose estimate that fluctuates daily, but the order of magnitude matters more than the precision. What actually matters is understanding who controls enough of that liquidity to move prices without alerting retail participants until the move is already happening. The beast isn't a metaphor. It's the aggregation of pension funds, sovereign wealth vehicles, index managers, and private equity that together manage roughly two hundred and fifty trillion in assets. A single asset manager like BlackRock or Vanguard doesn't need to own the most shares in any given company to control outcomes. They own enough across the widest possible range of tickers that their collective allocation decisions create gravitational pull on entire sectors. When Vanguard shifts from overweight to neutral on European industrials, that's not a suggestion. That's roughly eighty billion dollars repositioning itself within a quarter.
I've seen this play out in ways that have nothing to do with any single CEO's ambition. The mechanism is structural. Index inclusion alone can move a stock's price by three to seven percent on announcement day because passive flows have no choice but to buy. That's not power wielded through intent. It's power built into the architecture of how modern markets are constructed. Here's what nobody in the mainstream coverage gets right. The real concentration isn't at the corporate level. It's at the ownership level. Three institutional managers collectively hold significant voting power across nearly every major public company in the S&P 500. That means three organizations have outsized influence over board composition, executive compensation, ESG frameworks, and strategic direction without any of their individual investments necessarily being large enough to trigger regulatory scrutiny on their own.
How the Mechanism Actually Operates Day to Day
Let me walk through a concrete example instead of staying abstract. In early 2024, a major European materials company announced a strategic pivot toward green energy transition. The press coverage focused on the CEO's vision. What actually drove the decision was a quiet but coordinated set of conversations between the company's largest shareholders and the board about long-term valuations under decarbonization regulations. The shareholder group wasn't an activist fund. They were index-tracking vehicle mandates that had been quietly escalating their engagement letters for eighteen months. By the time the announcement hit the wires, the trading community had already priced in a forty percent probability shift on the outcome. The workaround I developed during my consulting years for spotting these dynamics before they became public involved tracking a specific set of signals that most people overlook. First, I monitored engagement letter filings from the top five asset managers for each position in my client's portfolio. These are required disclosures under certain regulatory frameworks but rarely summarized in market commentary. Second, I tracked changes in index weighting classifications before the official announcements. A security getting upgraded from "small cap" to "mid cap" in a major index means billions in mandatory buying will follow, and index providers often signal this six to eight weeks before the formal change date. Third, I compared institutional ownership statements across the top three filers and looked for divergence patterns. When two of the three largest managers increase their stated ownership while the third holds steady or reduces, that divergence usually reflects a shift in how these managers view the company's strategic trajectory rather than pure sentiment. One edge case that cost a client roughly fourteen million dollars in missed opportunity came from a situation where all three signals pointed in one direction and were wrong. A Southeast Asian logistics company showed engagement letter upgrades from BlackRock, Vanguard, and State Street simultaneously in Q3 2023. The index reclassification was positive. The ownership divergence was minimal, suggesting alignment. Every quantitative model I ran flagged it as a strong accumulation setup. The stock dropped twenty-two percent over the following six weeks when the company disclosed a major regulatory investigation that none of the institutional owners had factored into their models. The lesson was that institutional ownership data reflects lagging adjustments. By the time a manager files an updated ownership figure, they may already be planning an exit. The data shows where they were, not where they're going.
Get the Full Details
Counter-Intuitive Insights Most Analysts Miss
The first thing beginners get wrong about corporate market power is that they look for evidence of collusion or explicit coordination. It almost never exists in that form. What exists is convergence of incentives among entities that operate independently. When five major pension funds all reduce exposure to fossil fuel exposure stocks simultaneously, they aren't coordinating. They're each responding to the same fiduciary pressure from their own beneficiary populations and the same risk modeling outputs from their internal teams. The result looks identical to coordination, but it's emergence. That distinction matters because you can't counter it with the same tools you'd use against actual collusion. The second counter-intuitive point is that decentralization doesn't equal democratization. The proliferation of index funds and passive investing, which many observers celebrate as a leveling force, has actually increased the concentration of decision-making power. Twenty years ago, a portfolio manager at a pension fund made an active decision on every holding. Now, a handful of index providers make that decision for nearly every major fund worldwide. The people controlling the indexing methodology wield more structural influence over global capital allocation than any single central bank. That's not a conspiracy. It's a consequence of efficiency-seeking behavior compounding over decades.
Practical Framework for Assessment
If you want to analyze this yourself, start with the SEC Form 13F filings. They're public, they're filed quarterly, and they contain the raw institutional ownership data. The problem is that 13Fs don't show short positions, derivatives exposure, or voting agreements. I found that cross-referencing 13F data with proxy voting records from the ISS and Glass Lewis databases gives you a much more complete picture. The proxy voting data reveals which institutional investors are actually using their voting power to push for specific outcomes, separate from their trading behavior. Next, track the benchmark index methodology changes directly. MSCI, S&P Dow Jones, and FTSE Russell all publish their methodology updates on their websites. Setting up a weekly scrape of those pages takes about twenty minutes and gives you advance notice of structural rebalancing events that will trigger automated buying and selling. I built a simple alert system that flagged any methodology change mentioning weight limits, sector caps, or liquidity thresholds thirty seconds after publication. That thirty seconds meant I was positioned before the algorithmic traders got the same information from Bloomberg terminals. For the ownership convergence analysis, I used a three-source comparison approach. I pulled the latest 13F holdings from the company's investor relations page, which typically lists the top twenty-five institutional holders. Then I cross-checked against the institutional holdings sections of Morningstar and Yahoo Finance. When all three sources agreed on a holder's ownership percentage within a two percentage point margin, I treated it as reliable. When they diverged significantly, that divergence itself was the signal. It meant one of the sources had stale data, or the holder had made a material position change since the last filing period.
Where This Approach Breaks Down
I need to be honest about the limitations. This framework doesn't work well for private markets, where the actual concentration of capital is even more extreme than in public markets. Private equity firms managing over four trillion in committed capital operate entirely outside the 13F disclosure regime. You won't find most of the ownership concentration data that matters in any public filing. The framework also produces noisy signals during earnings season. Institutional ownership figures published in late February, May, August, and November reflect positions from the prior quarter. If a major position change happened in the most recent quarter, you won't see it for months. During that window, the data is actively misleading. I learned this the hard way when a client held a position based on a 13F reading that suggested a major manager was accumulating, only to discover three weeks later that they had exited completely in a market downturn that preceded the filing cutoff date. Another limitation is that this approach measures structure, not agency. It tells you who owns what and who votes how. It doesn't tell you why. Two managers with identical ownership percentages may have diametrically opposed views on a company's direction. One may be a passive index follower with no engagement intent. The other may be an engaged owner actively shaping strategy. The 13F data looks the same for both.

For situations where the standard framework fails, the alternative is to build relationships with company IR teams and sell-side analysts who have access to shareholder conversation flows. This is slower, less scalable, and requires genuine relationship investment. But it's the only way to get visibility into the conversations that happen before any filing or public disclosure. I recommended this hybrid approach to clients who needed conviction beyond what the structural analysis could provide.
What Changed After I Stopped Trying to Predict It
Early in my career, I treated corporate ownership concentration as something to predict and position ahead of. That approach worked inconsistently at best. The turning point came when I shifted from trying to anticipate moves to building a system that measured my portfolio's actual exposure to convergence risk in real time. Instead of asking which stocks would move because of institutional behavior, I started calculating what percentage of my portfolio's value was controlled by the top three index providers and how much of that exposure was to single-sector concentration. The adjustment took the portfolio from reactive to defensive. We didn't try to beat the institutional flow. We sized positions so that being wrong about any single institutional move wouldn't materially impact returns. That shift alone improved risk-adjusted performance more than any alpha-generating strategy had in the previous five years. The takeaway isn't that corporate market power is uncontrollable. It's that trying to outmaneuver it directly is usually a losing game for anyone without the same scale. The smart move is understanding the mechanics well enough to avoid positions where you're a passenger with no visibility into who's driving.