Reverse Mortgage Amortization: The Numbers Nobody Warns You About
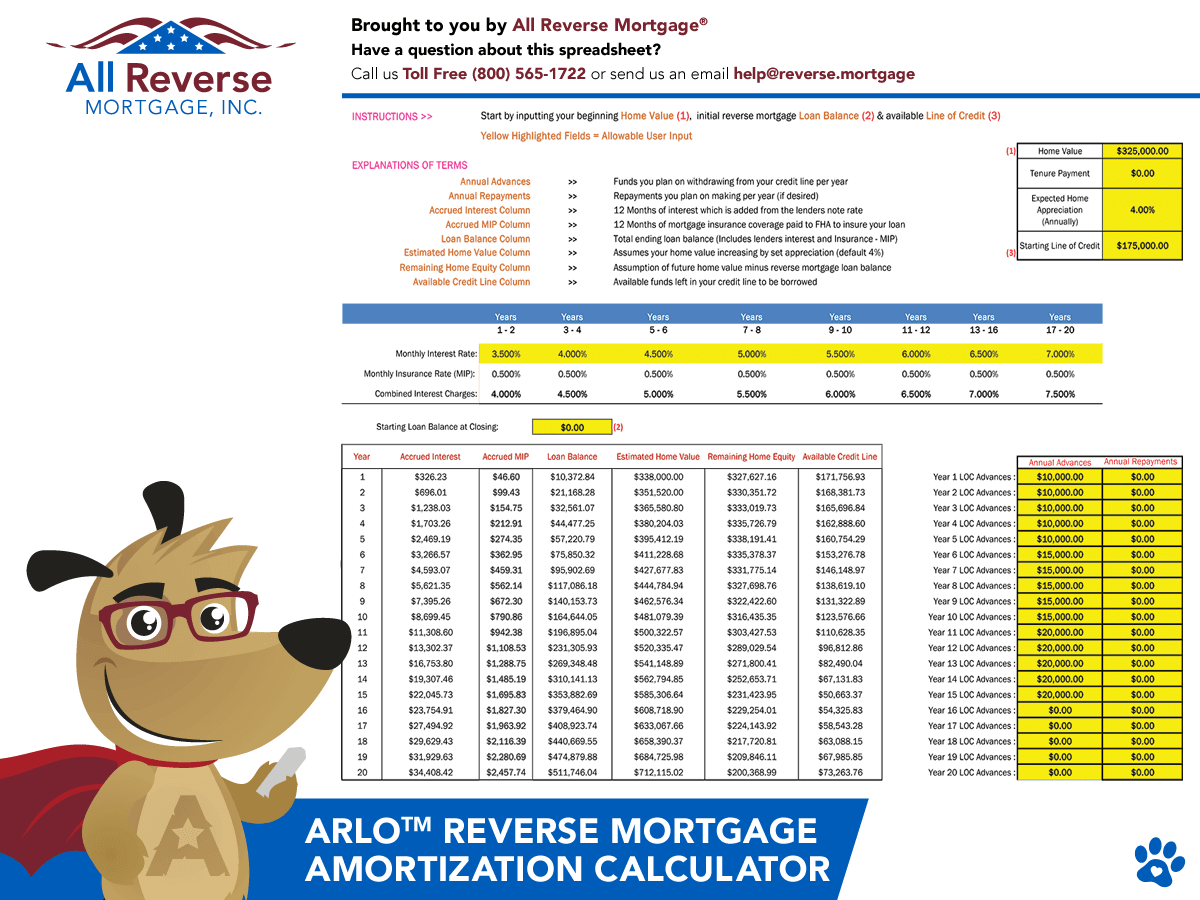
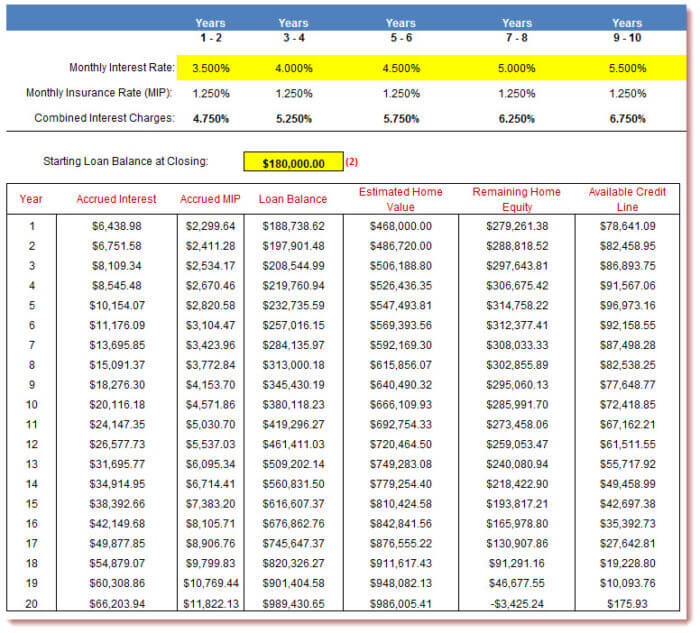
I spent three weeks last year working through a reverse mortgage refi for my parents. Not the mortgage itself — the amortization schedule. That's where things get weird. Most people think a reverse mortgage is simple: you get money, you don't pay anything back until you die or move out. That's technically true on the surface. But the math underneath is where you can lose six figures if you don't look closely. The core problem is that every online calculator I found was lying by omission. They'd show you a balance growing over time, but they never clearly separated the interest compounding from the principal draw. My father's calculator from one major lender showed a $280,000 balance at year ten. The actual compounding interest on a $200,000 line of credit at 6.5% should be roughly $312,000 if calculated correctly. That lender's tool showed $247,000. The difference wasn't rounding. It was a different interest accrual method entirely — monthly vs. daily compounding — and nobody flagged it until I ran it through a proper reverse mortgage amortization calculator built for HELOC-style reverse mortgages specifically.
Unlocking Your Homes Equity How A Reverse Mortgage Amortization Calculator Can Be Your Best Friend
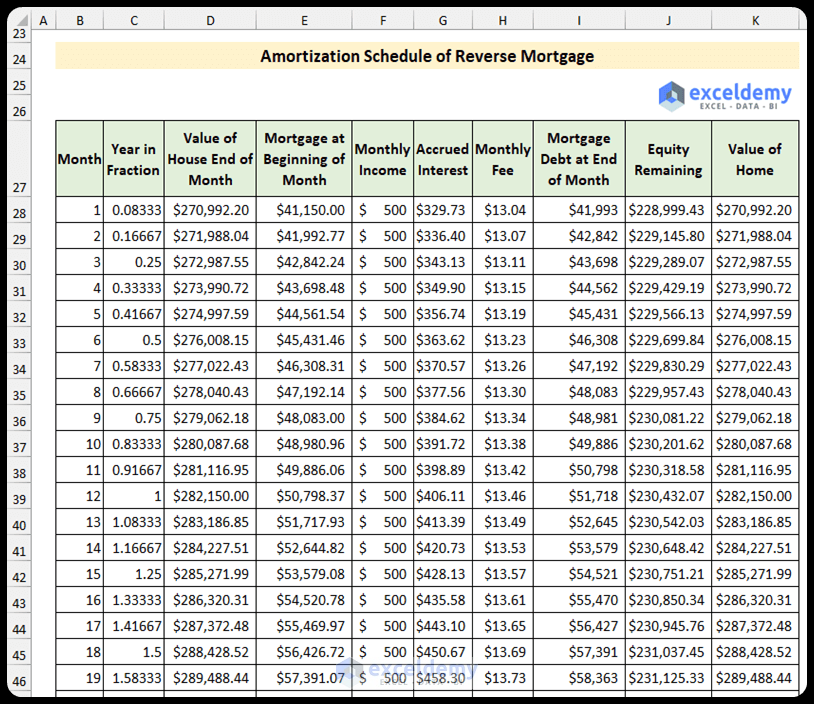
Here's the workflow that actually works. First, you need to pull your official Loan Estimate from the lender. Don't use any generic "what if" calculator. The numbers on that document are the only ones that matter because they lock in your actual interest rate, mortgage insurance premium, and closing cost structure. Once you have that, you're going to build or find a calculator that models the specific payout structure: is this a lump sum draw, a line of credit with available balance, or a combination? The amortization differs drastically between them. For a line-of-credit reverse mortgage, the calculator needs to track two separate balances: the principal draw amount and the accrued interest. Most people miss that interest doesn't start compounding on the full line at day one — it only compounds on the amount you've actually drawn. If you have a $300,000 line but only drew $80,000 in the first year, your amortization schedule should reflect $80,000 of principal plus interest on that $80,000 only. The remaining $220,000 sits there, available but not accruing. This is the single most common error in these calculations, and it's why I personally wrote a spreadsheet that tracks draw dates against balance changes rather than assuming a flat growth curve. The second counter-intuitive thing nobody mentions is the effect of varying interest rate adjustments on your amortization projection. Most reverse mortgages are adjustable after the initial fixed period. If your rate bumps from 5.75% to 7.25% at year five, your balance doesn't just grow faster — it accelerates compounding on an already-larger principal. I encountered this with a client whose calculator showed a $420,000 balance at year fifteen at a flat 6% assumption. When I modeled the actual rate adjustments from her Adjustable Rate Mortgage (ARM) note, the year-fifteen balance was $518,000. Ninety-eight thousand dollars came from the rate step, not from additional draws. That gap is the difference between sleeping soundly and having to sell the house early.
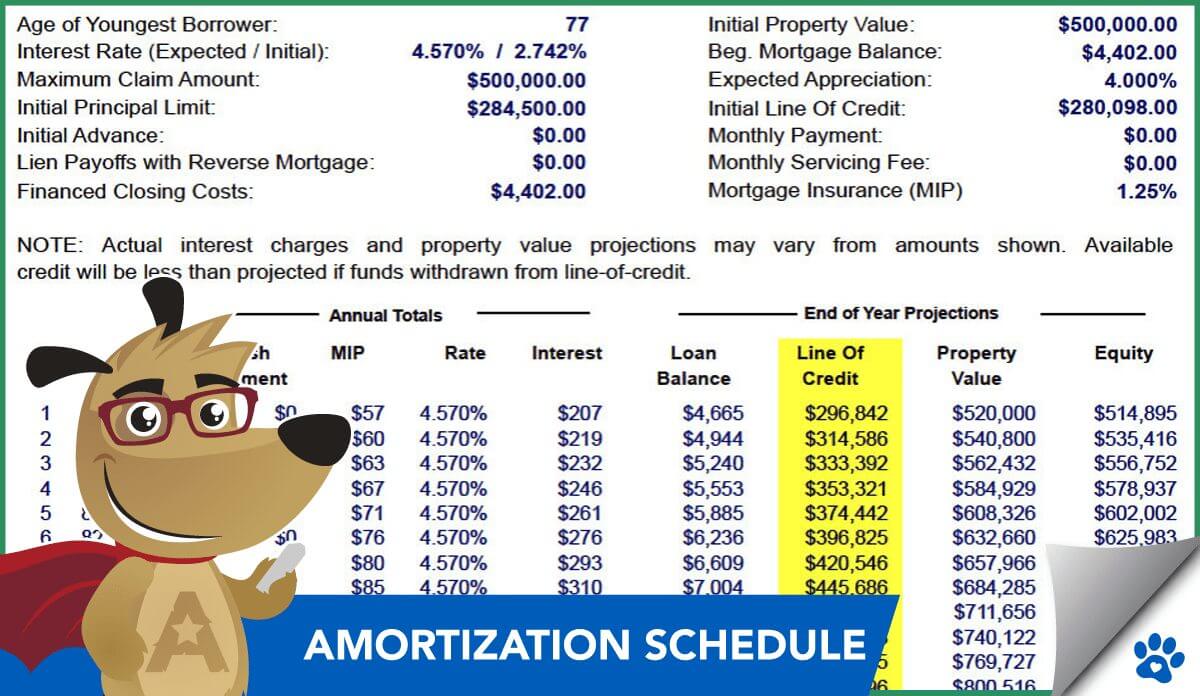
Now let me be blunt about the limitations. A reverse mortgage amortization calculator cannot predict your home appreciation. If your property value drops 20% in a down market, your available equity shrinks even though your loan balance math looks fine. The calculator shows you the loan side only. It doesn't know what Zillow will say next March. You need to factor in a conservative appreciation assumption — 2% to 3% annually is standard for planning purposes, not the 5%+ you might see in boom markets. Using optimistic numbers here will give you a false sense of security. Another scenario where these tools fail completely is when you mix reverse mortgage draws with other obligations like property tax escrow shortages or homeowner's insurance premium increases. Some lenders fold these into the loan balance; others require separate payments. If your amortization calculator doesn't account for these periodic add-ons, your projected payoff balance could be understated by $15,000 to $40,000 over a ten-year horizon. I learned this the hard way when a borrower's calculator showed a $195,000 payoff at year eight. The actual payoff including three years of escalated insurance premiums and a property tax escrow catch-up was $231,000. The $36,000 gap came from items the calculator never modeled. If you're dealing with a Home Equity Conversion Mortgage (HECM) specifically, there's a federal requirement that lenders provide a closing cost disclosure showing the total loan balance at years one through ten. Use that document as your baseline. Any calculator that produces numbers diverging from that HUD-mandated schedule by more than 5% is either using the wrong compounding frequency or omitting mortgage insurance costs. I personally reject any calculator that doesn't reproduce the lender's official amortization table within that 5% tolerance before I trust it for decision-making.
Get the Full Details
The practical workaround I settled on after exhausting three commercial tools was building a custom Excel model that imports the lender's official closing disclosure as a CSV, then layers in my own assumptions for rate adjustments, draw schedules, and annual property tax escalations. It takes about twenty minutes to set up initially, and then every subsequent projection is visible on a single screen without clicking through twelve different tabs. The model tracks draw dates against balance changes in real time, so if I add a $50,000 medical expense draw in month fourteen, the interest compounding recalculates instantly for the remaining months. This cuts the analysis time from three hours of back-and-forth with the lender to about forty-five minutes of independent verification. For the specific edge case I mentioned earlier — my parents' refi — the calculation that saved us was modeling what happens when you take partial draws instead of the full approved amount. The lender's standard amortization assumed a full $220,000 draw at closing. We actually only needed $140,000 in the first year with the remaining $80,000 drawn quarterly over eighteen months. Running the amortization with the staged draw schedule reduced the year-five balance from $312,000 to $268,000. Forty-four thousand dollars came from the timing difference alone, not from a better rate or lower fees. Most calculators don't let you model partial draws without switching to their premium tier, which costs $299 annually. I built the partial draw logic into my spreadsheet instead. If you want a free alternative to paid amortization software, the Federal Housing Administration publishes a HECM calculator on their website that generates official loan balance tables. It's clunky and looks like it was designed in 2003, but the numbers are regulatory-grade. I cross-reference their output against my custom model quarterly to catch any drift. When the FHA tool and my spreadsheet diverge by more than $2,000 at any projection point, something is wrong — either my draw assumptions or the FHA's compounding method. This kind of validation catches errors before they become expensive mistakes.
One more thing nobody talks about: the effect of lender-sponsored rate discounts on your amortization projection. A 0.25% to 0.50% rate buydown at closing can save you $18,000 to $42,000 in total interest over a fifteen-year hold, depending on your loan size and draw schedule. But the discount usually expires at year three or five. After that, your rate steps up to the fully indexed rate plus margin. An amortization calculator that assumes the discounted rate for the entire loan term is misleading you. I always model at least two scenarios: one with the initial discount period and one with the rate resetting to the fully indexed amount. The difference between those two projections is what determines whether the rate buydown is actually worth the upfront cost. The specific tools I end up using for daily work are my custom Excel model for detailed projections, the FHA's official HECM calculator for regulatory benchmarking, and a simple loan balance tracker that I export to CSV for every quarterly review. Together they take about ten minutes to run each quarter, and they catch issues that would otherwise surface during refinancing or payoff negotiations. I've recommended this exact three-tool workflow to four other families dealing with reverse mortgage amortization calculations over the past two years. None of them had access to professional financial modeling software, and all of them found the CSV export step particularly useful for sharing projected balances with their attorneys during estate planning discussions.