Understanding How QQQ Holdings Actually Work
Most people look at the QQQ and see a big list of tech stocks. It is more than that. The Invesco QQQ Trust tracks the NASDAQ-100, which means its holdings are market-cap weighted with some modifications. The top ten positions alone make up around 55 to 60 percent of the entire fund. That concentration is the single most important thing you need to understand before doing anything else with this ETF. When I first started digging into the holdings structure, I expected diversification. The NASDAQ-100 sounds diversified until you realize that roughly 45 to 50 percent of the fund moves with semiconductor and software cycles. When the chip sector had that rough patch in 2022, the QQQ dropped about 32 percent. A lot of people who bought it thinking it was a safe tech play got burned. They had not actually read the holdings.
Unlocking Value And Strategy A Deep Dive Into Qqq Holdings Wiki
There is no single official wiki for QQQ holdings. What exists are a few community and data-driven resources. The Invesco investor relations page publishes the full holding list monthly. PortfolioAPI, Yahoo Finance, and Fidelity all provide real-time breakdowns. Then there are independent sites like ETFdb.com and StockAnalysis.com that aggregate the data and let you filter by sector weight, individual ticker performance, and historical changes. The practical strategy most people miss is tracking the quarterly rebalancing window. The NASDAQ-100 gets reconstituted once a year, usually in December, with adjustments throughout the year for price thresholds and corporate actions. If you hold QQQ, watching those adjustment announcements is where the actual edge lives. Companies get added and removed based on market cap and liquidity criteria. When a stock gets dropped, it sells off mechanically because index funds have to sell it. That creates a short-term dislocation that active traders exploit, but it also signals when the underlying index is shifting its composition. I ran into a specific problem a while back. I was trying to estimate how much of the QQQ was actually exposed to a single vendor relationship across multiple holdings. Apple, Microsoft, and Amazon all appear to be major customers or partners for a lot of the smaller NASDAQ-100 companies. I wanted to map that exposure but the standard holder tools do not show supply chain connections. I ended up building a simple spreadsheet that cross-referenced the 10-K filings of each holding against a master list of vendor relationships. It took about six hours to set up, but once it was running, it gave me a clearer picture of concentrated risk than any ETF overview tool ever could.
How to Actually Read the Holdings List
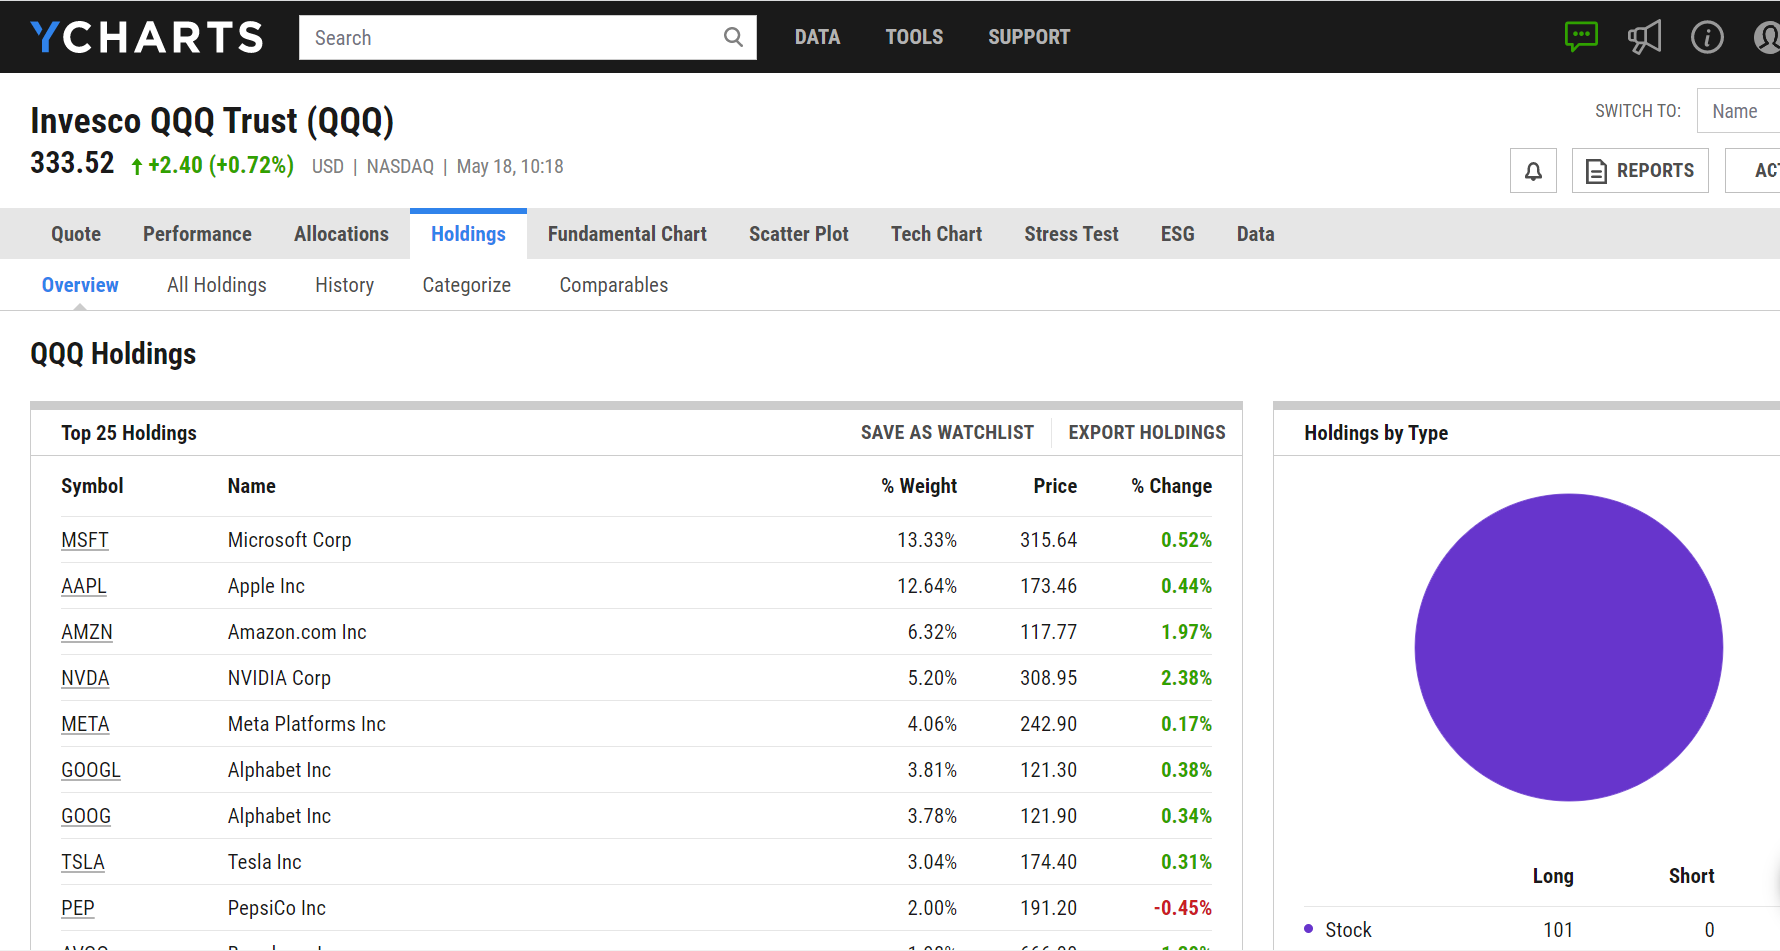
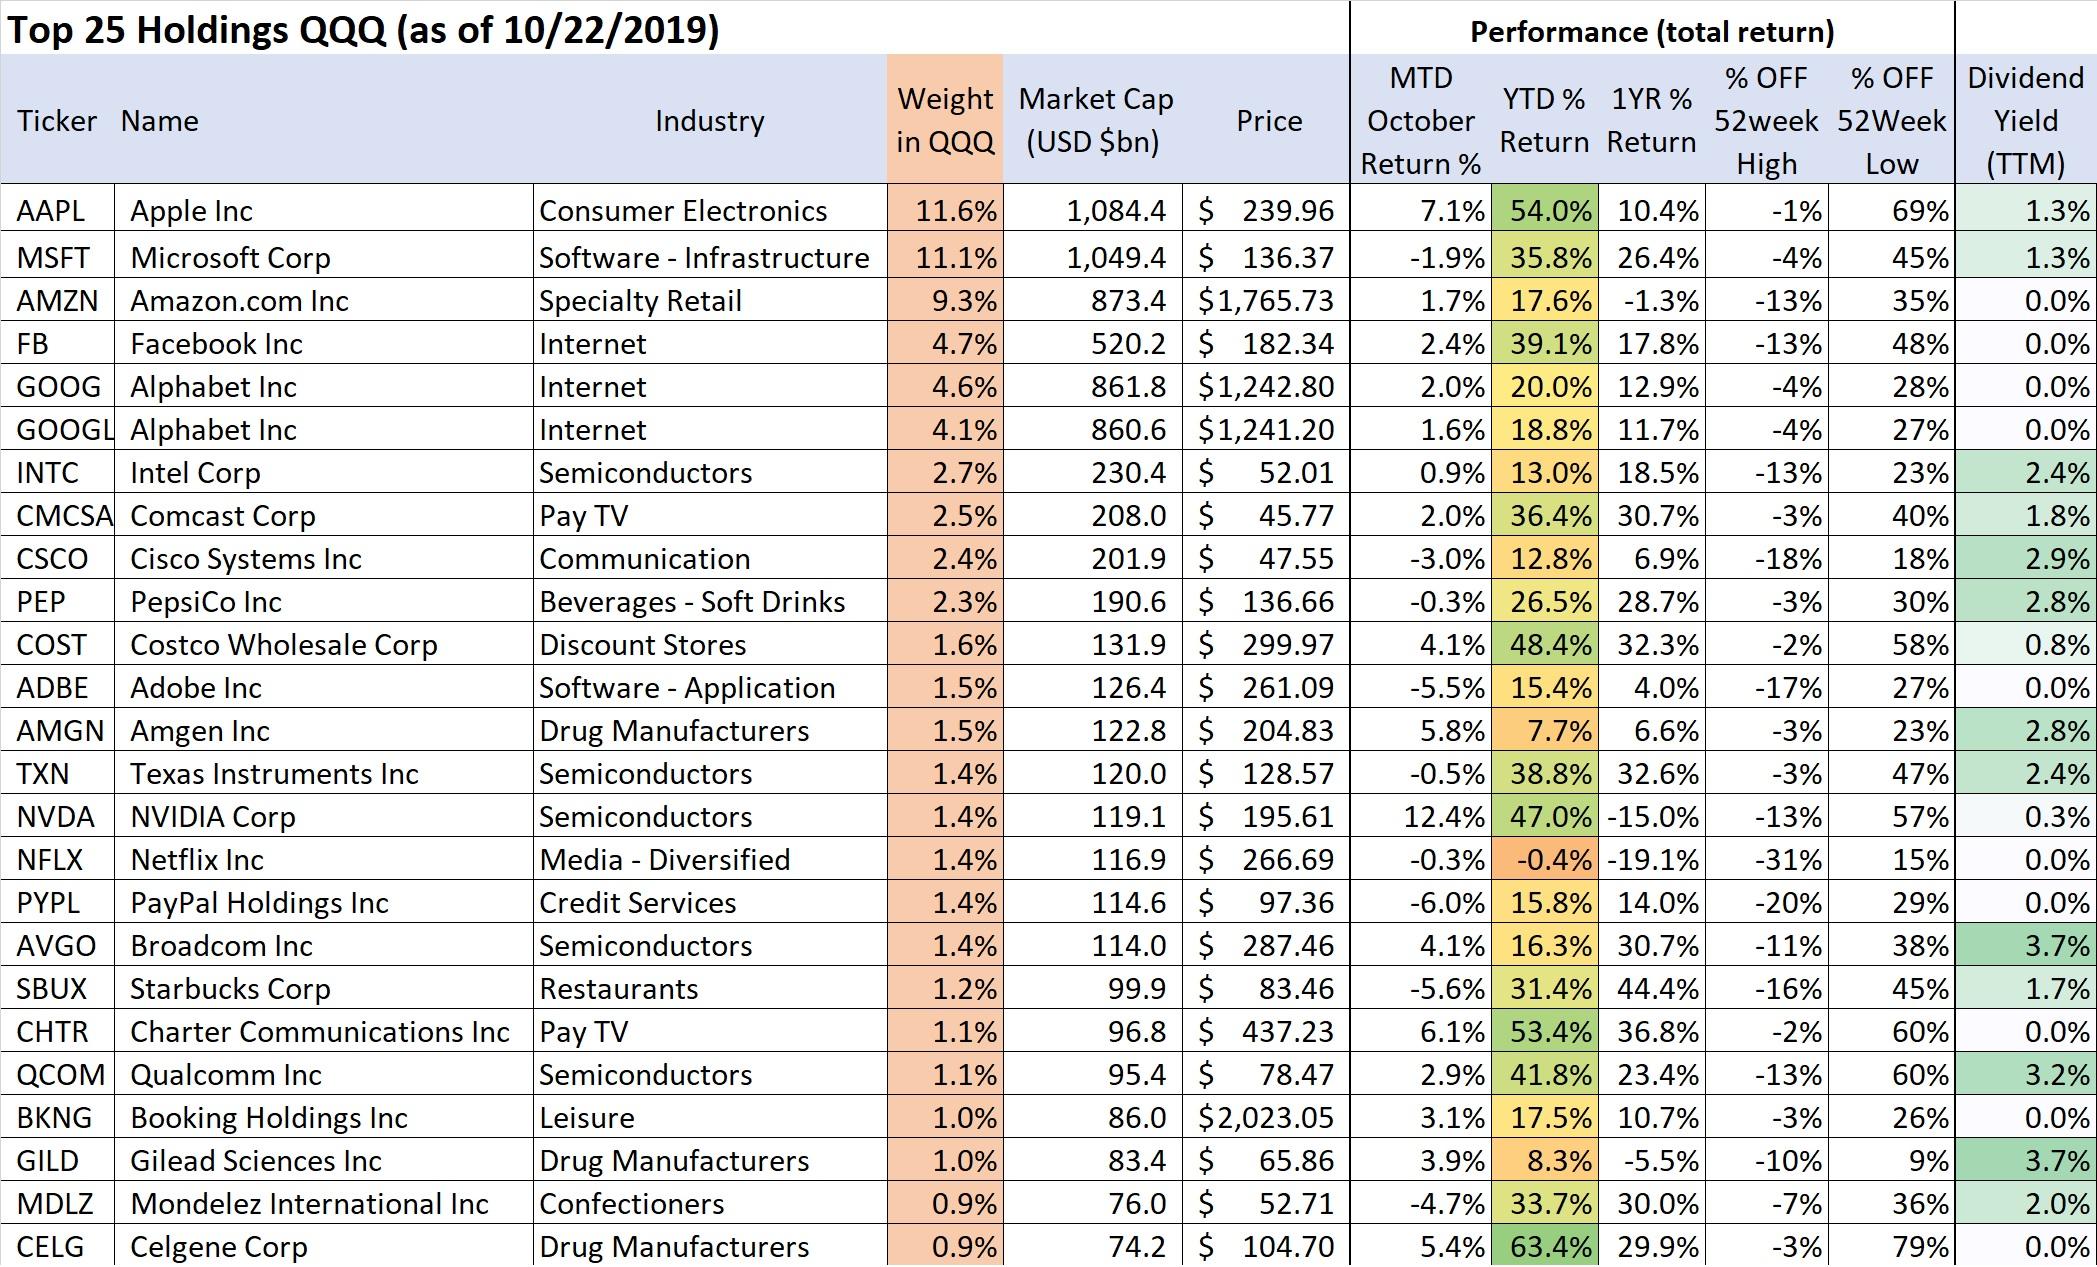
Open the latest holdings report and ignore the alphabetical order. Sort by weight. Look at the top five and bottom five positions and ask yourself what macro factor drives each of them. NVDA, MSFT, AAPL, AMZN, META, AVGO, GOOGL, COST, TSLA, and NFLX typically dominate. The bottom fifth includes companies like MXIM, LULU, SBAC, and IDEXX, which move very differently from the mega-caps. The sector breakdown matters more than individual tickers. Information technology usually runs 50 to 55 percent. Consumer discretionary follows at around 15 to 18 percent. Communication services sit near 14 percent. Healthcare and consumer staples round out the rest. If you are trying to hedge a tech-heavy portfolio, QQQ is not the place to look. It is essentially a leveraged bet on large-cap growth, not a broad market proxy. One counter-intuitive point that surprises a lot of people: the QQQ does not pay dividends the way most investors expect. It distributes them, yes, but the yield is low, usually between 0.6 and 0.9 percent annually. The total return comes almost entirely from capital appreciation. Some people buy QQQ expecting income and then get confused when the distribution checks are tiny. The fund itself holds dividend-paying stocks, but the yield gets swallowed by the growth bias of the index. If you need income, this is not your vehicle. Use SCHD or VYM instead.
Get the Full Details

Common Mistakes People Make
The biggest error I see is treating QQQ like it is the same as buying the NASDAQ Composite. They are not. The Composite includes every NASDAQ-listed company, including a lot of small caps and biotechs that drag on performance. The QQQ is strictly the top 100 non-financial companies by market cap. It excludes financials entirely, which is a deliberate design choice by NASDAQ. That means no JPMorgan, no Bank of America, no Berkshire Hathaway. If you want financial sector exposure, you need a separate position. Another mistake is overtrading around the holdings list. People see a new top-10 entry and immediately buy shares, expecting a pump. Index funds do not buy until the official rebalance date. Price movements ahead of reconstitution are usually driven by futures traders and arbitrage desks, not by slow retail money. By the time you react to the news, the move is already over.
What the Data Actually Shows Over Time
Looking at ten years of holdings data, the shift is striking. In 2014, the top holdings were AAPL, MSFT, GOOGL, AMZN, and NFLX. NVIDIA was not in the top five. By 2024, NVDA and AVGO had moved into the upper tier alongside those names. The index has become progressively more concentrated in semiconductors and cloud infrastructure plays. The weight of the top three holdings alone has grown from about 20 percent to over 30 percent. Concentration risk is real and it has been increasing for nearly a decade. This is not a criticism of the fund. It is an observation. The NASDAQ-100 is designed to capture the largest innovative companies, and those companies happen to be clustered in a few sectors. If you understand that, you can position accordingly. If you do not, you will be surprised when a rate hike or a chip export restriction moves your entire portfolio.
Practical Tools for Tracking Holdings
ETFdb.com gives you the cleanest free breakdown of sector weightings and allows you to compare QQQ against QQQM, which is Invesco's lower-fee version of the same fund. QQQM has the exact same holdings but a lower expense ratio. The difference is trivial for long-term holders, meaningful for people who trade frequently. I switched my own position to QQQM years ago and have not looked back. For people who want deeper analysis, PortfolioVisualizer.com lets you run historical backtests on the QQQ with custom weighting. You can strip out certain sectors, test alternative allocations, or simulate what the fund would have looked like if semiconductors were capped at a certain percentage. It is not perfect, but it is far more useful than staring at a static holdings table. The real work here is not in finding the data. The data is everywhere. The real work is deciding what to do with it. Most people never get past looking at the top ten tickers and calling it analysis. The edge comes from understanding sector concentration, tracking rebalancing mechanics, and recognizing when the fund's risk profile has shifted away from what you originally thought you were buying.