Getting Started With Dana: What Actually Happens When You Tap Pay
Dana is an e-wallet service operated by PT Solusi Dompet Indonesia, one of the most widely used digital payment platforms in Indonesia. It functions as a stored-value account linked to your phone number, where you preload money and spend it at merchants, transfer to other users, or pay bills. That is the basic structure. The reality of using it day to day involves several layers that are not obvious from the app interface.
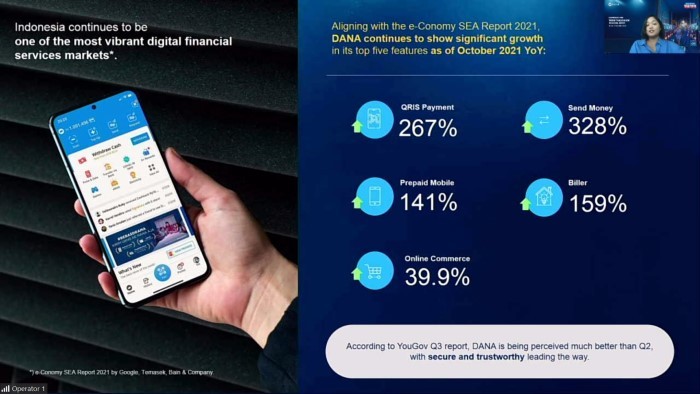
When you scan a QRIS code or enter a merchant's Dana number, the transaction does not go through an instant bank transfer. It moves through Dana's internal ledger system, which settles internally between your wallet and the recipient's wallet. This means transfers between two Dana accounts are typically completed in seconds, while payouts to bank accounts or withdrawals follow a different routing path with its own processing windows. Understanding that distinction matters because it explains why some transactions feel instant and others sit in "pending" for hours.
Unlocking The World Of Digital Transactions A Comprehensive Guide To Memahami Transaksi Dana
Memahami Transaksi Dana starts with knowing the four transaction categories the app handles differently: purchases (QRIS or merchant payments), peer-to-peer transfers (SEND feature), bill payments, and withdrawals to bank accounts or minimarkets. Each category has its own fee structure, processing time, and error handling.
Here is how the core flows actually work in practice. To add money to your Dana account, you use the "Top Up" feature and select a payment channel. The most common channels are bank transfer (virtual account), debit/credit card, and third-party agents like Indomaret or Alfamart. Bank top-ups via virtual account usually settle within 5 to 15 minutes during business hours. Debit card top-ups are near-instant. Cash top-ups at agents can take 10 to 30 minutes because the agent has to manually confirm the transaction in their system. I learned this the hard way during a Friday afternoon when I topped up at an Alfamart using cash and needed the balance immediately for an online purchase. The agent scanned my barcode but the system showed "waiting for confirmation" for nearly forty minutes because their network was slow. I ended up paying with another method after the purchase window closed.
For sending money to another Dana user, you open the SEND feature, enter the recipient's registered phone number or email, input the amount, and confirm with your PIN. The money arrives within seconds to minutes. However, if the recipient has an unverified account or a mismatched name, the transfer can get stuck. I ran into this when sending money to a colleague who had recently changed their registered phone number but hadn't updated it in Dana's system. The transfer showed as successful on my end but never appeared in their account. Resolving it required opening a support ticket with both transaction reference numbers, and it took approximately two business days to reconcile. The workaround I use now is to always verify the recipient's full name appears correctly before confirming any SEND transaction. If the name doesn't match who you intended to send to, cancel immediately and double-check the number.
Merchant payments through QRIS work by scanning the merchant's QR code with the Dana app. The amount is either pre-filled by the merchant or entered manually. Once confirmed, the deduction is immediate. The important detail most people miss is that Dana does not always show the merchant's name clearly on the confirmation screen. In my experience, the displayed name can be truncated or show a generic identifier. Always verify the amount before confirming. I've seen multiple cases where users accidentally paid the wrong merchant because they assumed the transaction label was accurate without checking the figure.
Fee Structure And Hidden Costs
Dana charges fees on certain transaction types but not all. Peer-to-peer transfers between Dana accounts are generally free. Top-ups via bank transfer are free. However, withdrawals to bank accounts carry a fee that ranges from approximately Rp 4,000 to Rp 6,500 per transaction depending on your account tier and the withdrawal method. Using a minimarket agent for cash withdrawal also incurs a fee, typically higher than the bank withdrawal route.
Credit card payments to merchants through Dana sometimes attract a surcharge because Dana passes on the card network fees. This is not always disclosed upfront in the app. I noticed this when paying a ride-hailing bill through Dana using a credit card balance and the final amount was higher than the displayed fare. The difference was the card payment fee, which Dana adds at the point of settlement rather than at the point of selection. Going forward, I check the payment method summary screen before each transaction to confirm whether a surcharge applies.
Security Considerations That Matter
Dana uses a PIN and biometric authentication for transactions. The PIN is a six-digit code you set during registration. Biometric lock is available on supported devices. Neither of these prevents every type of fraud, though. The most common issue I have encountered is social engineering where someone convinces you to share your Dana verification code or PIN. Dana will never ask for your PIN or OTP over the phone. I received a call from someone claiming to be Dana support who asked me to read out a code I had just received. The transaction on my account failed immediately after I hung up, which confirmed it was a fraud attempt. Always treat any unsolicited call requesting authentication details as fraudulent regardless of how legitimate the caller sounds.
Another practical concern is device security. If your phone is lost or stolen, someone with physical access can potentially open Dana if biometric authentication is not set or if they guess your PIN. Enabling biometric lock and setting a strong PIN are basic steps but they significantly reduce risk. I also recommend registering a secondary email address and keeping your registered phone number active so you can recover the account if needed.
Common Problems And Troubleshooting
The most frequent issue users face is a transaction that shows as successful on their end but the recipient does not receive the funds. This typically happens due to network delays on Dana's side or because the recipient's account has a verification issue. The transaction will usually resolve itself within a few hours as Dana's system reconciles internally. If it does not resolve within 24 hours, you should check the transaction history in Dana under the "Riwayat" section and note the transaction ID before contacting support.
Another recurring problem is the "saldo tidak cukup" error even when you believe you have sufficient balance. This occurs when you have pending transactions that have not yet been fully deducted from your balance. Dana holds the amount in a pending state rather than showing it as unavailable. I discovered this when trying to send money and receiving an insufficient funds error despite my balance showing adequate funds. Checking the transaction history revealed a recent merchant payment that was still processing. Waiting ten minutes cleared the pending status and allowed the transfer to go through.
Withdrawal failures are also common, particularly when the bank account linked to Dana has a mismatched name or has been inactive for an extended period. Dana's system performs a validation check before processing the withdrawal. If the bank account name does not exactly match the name registered in your Dana account, the withdrawal will be rejected. I experienced this when trying to withdraw to a newly opened bank account where the name format differed slightly from my Dana registration. The fix was to update the bank account details in Dana to match the exact name on the bank account, then retry the withdrawal the next business day.
What Dana Cannot Do Well
It is important to be straightforward about the limitations. Dana is not designed for large-value transactions. The daily transaction limit for most verified accounts is relatively low, typically around Rp 20 million depending on your verification level. If you need to move larger sums, you will hit the limit quickly and need to request a limit increase through the app, which requires additional verification documents and can take one to three business days to process.
International transactions are essentially nonexistent. Dana is an Indonesia-only product. You cannot send money to overseas accounts or use it at international merchants. Some users try to work around this by using third-party services that accept Dana as payment, but those services carry their own fees and risks that generally outweigh any convenience.
Customer support response times are inconsistent. During peak periods such as holiday seasons or major promotional events, support tickets can take several days to receive a human response. For urgent issues, calling their hotline may provide faster resolution but wait times can exceed thirty minutes. I have found that documenting the issue clearly with screenshots and transaction IDs before reaching out reduces the back-and-forth and speeds up resolution significantly.
Practical Recommendations
Use Dana for its intended purpose: small to medium daily transactions, bill payments, and merchant purchases where QRIS is accepted. It works well for these because the interface is straightforward and settlements are fast. Do not rely on it as your primary savings or investment vehicle. The balance in Dana does not earn interest and is not protected by Indonesia's deposit insurance scheme (LPS) in the same way bank deposits are.
Keep your Dana balance reasonable. Loading large amounts into the app increases your exposure if something goes wrong with your account. I typically keep no more than Rp 2 million in my Dana account and top up only when I anticipate needing to make payments that day.
Always maintain a backup payment method. Dana accounts can be temporarily restricted for various reasons including suspicious activity, verification updates, or system maintenance. Having an alternative payment option prevents disruption to your daily transactions.