
Why Your Net Worth Numbers Are Probably Wrong
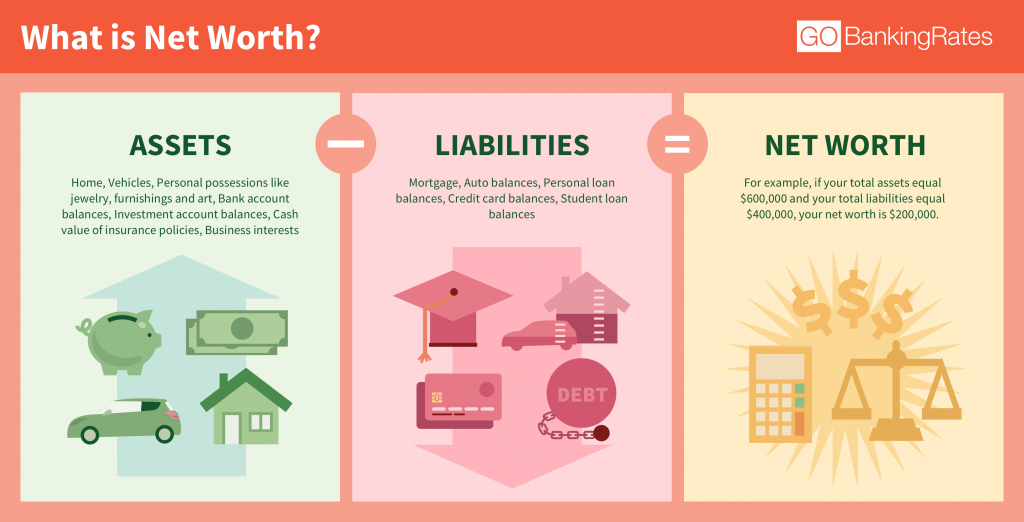
I spent a few years doing financial modeling for mid-market companies, and the single most common mistake I saw was people treating net worth calculation like a simple asset minus liability problem. It is not. The second you get beyond a basic checking account and a mortgage, the edges get fuzzy fast. A friend of mine once tried to calculate his family's net worth for a loan application and came in $40,000 short because he undervalued his retirement accounts by using year-end balances instead of the actual average daily balance across the quarter. The lender rejected the numbers anyway because they didn't match the official 1099-R forms he eventually produced. That story came up enough times that it became a running joke in my office. The core formula is still assets minus liabilities, but the devil lives in the valuation details. You need a snapshot date and you stick to it religiously. Pick a day, say December 31st, and value everything as of that single point in time. Do not average things unless you have a reason to. Most professional valuations use a closing balance sheet approach, which means you are capturing the state of affairs on one specific date, not some rolling approximation. List every asset at fair market value, not what you paid for it and not some optimistic guess. A house bought for $320,000 in 2018 that now appraises at $410,000 is worth $410,000 on your net worth sheet, not $320,000. Same goes for stocks, bonds, mutual funds, crypto, collectibles, and business interests. For liquid assets, pull the exact closing balance from each institution. For illiquid assets, get a recent appraisal or use a published index if you are valuing things like fine art or vintage vehicles. When I worked on a deal involving a privately held consulting firm, the owner had listed his practice at book value. We revalued it using a multiples approach based on comparable transactions and found the business was actually worth roughly three times what he had written down. He had no idea.
Liabilities are simpler but still tripped people up regularly. Every debt goes on the list at its current payoff amount, not the original loan amount. Credit card balances, auto loans, student loans, mortgages, personal loans, anything with a remaining balance belongs there. Some people forget small obligations like medical bills or a forgotten line of credit and then wonder why their debt-to-income ratio looks oddly high to a lender. One thing beginners consistently miss is how to handle nested or shared assets. If you and your spouse own a home together, the full value goes on your combined net worth sheet, but so does the full mortgage balance. You do not split the mortgage in half and only count half of it against one person's liability unless you are doing separate individual calculations. Same with joint investment accounts, joint tax obligations, or co-signed loans. Track who is legally responsible for each debt and assign it accordingly. I once had a client who owned a small rental property through an LLC. He had valued the property at his original purchase price and ignored the outstanding commercial loan that the LLC had taken out to refinance it. The result was a net worth that looked inflated by about $180,000. When we corrected it by pulling the actual outstanding loan balance from the lender and subtracting it from the current appraised value of the property, the net worth dropped sharply. He went from thinking he was in a strong position to realizing he needed a different strategy entirely.
The Practical Workflow
Here is how I actually do it when someone asks me to walk through a real calculation. Start with a spreadsheet, a simple one, not something fancy. Columns for asset type, description, institution or source, valuation date, current value, and notes. Rows for liabilities with the same structure. Sum each column at the bottom. Subtract total liabilities from total assets and you have your net worth. That is it. Nothing complicated about the arithmetic. The hard part is gathering accurate numbers. Most people keep their financial documents scattered across email inboxes, phone apps, and physical mail. I recommend pulling everything into one place at least once a year. Download statements from every bank, brokerage, retirement account, and loan servicer. Use a password manager to track which institutions hold your accounts. If you have multiple 401(k) accounts from old jobs, you will not remember them all without a systematic check. I use a simple checklist: checking, savings, money market, certificate of deposit, brokerage, employer retirement accounts, real estate, vehicles, personal property over a certain threshold, business interests, and then every loan or credit line. If it has a value or a balance, it goes on the list. For valuation, liquid assets are easy. Open the account portal, grab the closing balance on your snapshot date, and record it. For real estate, use either a recent comparative market analysis from a local agent or an official appraisal if you have one. If you do not have a current appraisal, a Zillow estimate is better than nothing but is often off by five to ten percent. In markets with high volatility, that gap matters. When I was valuing properties in Texas during the 2022 correction, estimated values swung wildly month to month. Relying on an automated estimate led to net worth figures that changed by tens of thousands between January and March, which made tracking progress nearly impossible.
Get the Full Details
Vehicles are another area where people get sloppy. KBB or Edmunds guides give you a rough idea, but those are retail values, not what you would actually get if you sold the car today. If you need precision, get a private-party quote or look at recent listings for similar vehicles in your area. The difference between a wholesale trade-in value and a private sale value can be several thousand dollars on a mid-range car. Business interests require the most care. If you own a stake in a privately held company, you cannot just look up a stock price. You need either a formal business appraisal, a recent 409A valuation if it is a corporation, or a negotiated price from a recent transaction. Book value is a starting point, but it rarely reflects true economic value. Goodwill, brand equity, recurring revenue contracts, and intangible assets all add value that book value misses. I once valued a small manufacturing business using a discounted cash flow model and found that its net worth was closer to six times its book value. The owner had been underestimating the business for years and nearly undervalued it when negotiating a buyout.
Common Pitfalls That Derail Accuracy
Double counting is the most frequent error. People include a home equity line of credit as an asset when it is actually a liability. They also count the same investment account twice if it appears on more than one statement. Check every entry against its source to make sure it is unique. Outdated valuations creep in slowly. That mutual fund you bought three years ago is not still worth what it was worth when you bought it. Update everything at least quarterly. Annual updates are acceptable for stable portfolios, but if you are managing active positions, quarterly is the minimum. Ignoring debts that are not in your name. If you co-signed a loan for a child or a business partner, that debt is legally yours until it is paid off. Lenders do not care about internal agreements. Include it. It matters for net worth and it matters for any future borrowing you might need.
Miscalculating taxes owed on unrealized gains. Some people try to net out capital gains taxes from their investment values. This is not standard practice for a net worth statement. Taxes on unrealized gains are not yet owed and may never be owed if the asset appreciates further and is passed through step-up in basis at death. Include the full market value and let the tax question sit for later.
When Net Worth Calculation Breaks Down
No method works perfectly for every situation. Net worth statements struggle with highly illiquid assets, complex ownership structures, and international holdings. If you own property in a foreign country, currency fluctuations and differing valuation standards can distort your numbers. If you have a complex partnership or trust arrangement, determining your actual economic interest requires legal and accounting expertise that goes beyond a spreadsheet. Crypto assets introduce another layer of difficulty. Exchanges report differently, wallets are hard to track, and staking rewards complicate valuation. I have seen people miss entire wallets because they used a different exchange or forgot about a hardware wallet. The best approach is to maintain a personal ledger that records every transaction and periodically reconcile it against exchange statements. Automate this with a tool like Koinly or CoinTracker if you have a high volume of trades, otherwise do it manually and review it monthly. Even with careful work, net worth is a snapshot. It tells you where you stand on a given day, not your trajectory. Two people with identical net worth can be in very different financial positions depending on income stability, debt structure, and asset composition. A person with $500,000 in a fully paid home and $50,000 in investments is in a stronger position than someone with $500,000 in a home but $200,000 in high-interest consumer debt. Net worth alone does not capture risk. Pair it with a cash flow analysis and a liability maturity schedule for a fuller picture.
I usually recommend that anyone serious about tracking net worth build a simple five-year history. One data point is useless. Five years shows trends, reveals whether your asset growth is outpacing debt accumulation, and highlights seasonal or cyclical patterns. If your net worth has been flat for three years while your income grew, something is wrong with your allocation or your spending habits. The numbers do not lie even if they are uncomfortable.


