How Zillow Actually Calculates Home Values
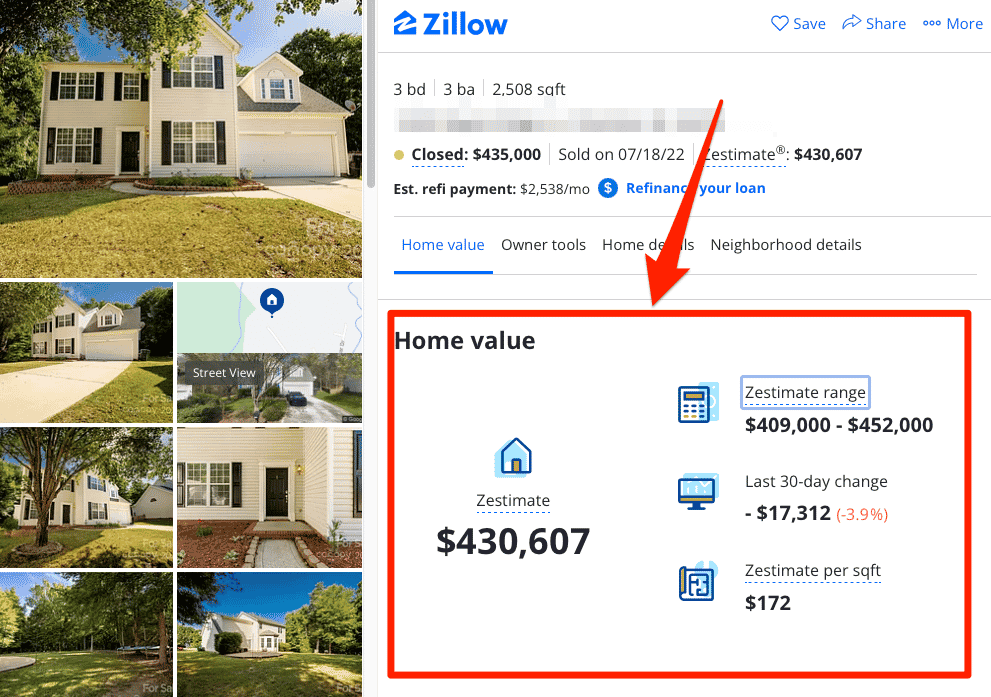
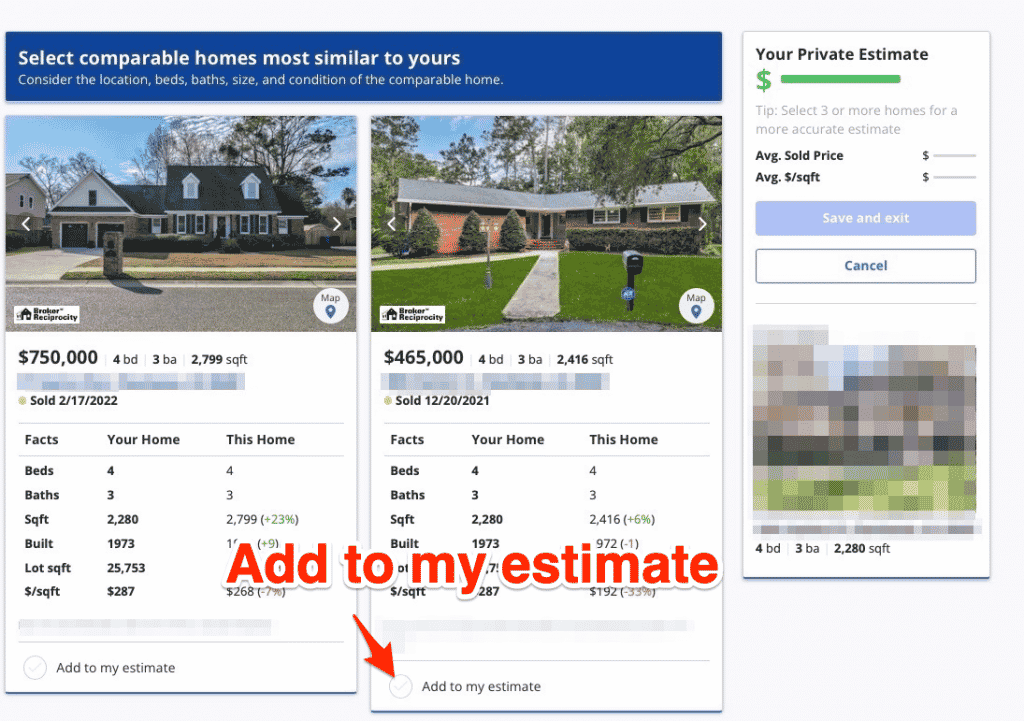
Zillow calls it the Zestimate, and it shows up on every listing you've ever scrolled past. It's not a guess thrown together by a random algorithm. There's real data behind it, but the way it arrives at that number is messier than most people realize. I spent years working with residential appraisal data before moving into a role where I audited automated valuation models for a regional bank. That's how I learned what actually happens under the hood. The core of the system is a combination of public records, user-submitted data, and comparable sales analysis. Zillow pulls property tax assessments, last sale prices, square footage, lot size, bedroom count, and year built from county recorder offices across the country. It also crawls MLS listings and lets homeowners update their own home details. Those updates feed back into the model. The comparable sales engine looks at recently sold properties within a half-mile radius, weighted by how similar they are to the subject property. But here's what most people miss. Zillow doesn't visit houses. It can't see that the kitchen was remodeled in 2023 or that the basement has water damage. The Zestimate runs on what's recorded, not what's visible. I worked on a project where a homeowner had put in a $120,000 addition that was permitted and updated in the county records. The Zestimate reflected the new square footage, but it didn't account for the quality of the build. The property was appraised at roughly $40,000 above the Zestimate because the addition was high-end custom work, not contractor-grade flip material. The algorithm treated a $50-per-square-foot addition the same as a $200-per-square-foot addition.
What Goes Into The Number
Three data layers feed the Zestimate. The first is the property characteristics layer: size, age, rooms, stories, garage spaces, heating and cooling type, and lot dimensions. Zillow gets most of this from public records, which are often incomplete or outdated. County assessors don't always update when a renovation happens, and some jurisdictions are worse than others about maintaining accurate records. The second layer is the transactional data layer, which includes closed sale prices, list prices, and price reductions. This is the most heavily weighted component because actual money changing hands tells you more than any attribute ever could. The third layer is the neighborhood comparables layer. Zillow identifies similar properties that have sold recently and adjusts the estimate based on differences between those properties and the one you're looking at. The model Zillow uses is proprietary, but it's generally understood to be a hedonic pricing model with elements of machine learning. That means it assigns value to individual characteristics rather than treating a house as a single unit. A finished basement adds a certain dollar amount. A pool adds another. Location adds a multiplier. The system has been trained on millions of sales data points across the United States. I once pulled Zestimate reports for a cluster of twelve identical tract homes in suburban Texas that had all been renovated at different levels. Five had been flipped with cheap materials. Seven had been owner-occupied and updated slowly over twenty years. The Zestimate spread across those twelve homes was around eight percent, which should have been closer to three percent given that the baseline attributes were identical. The algorithm couldn't distinguish between a homeowner who replaced the floors with laminate and one who replaced them with hardwood. Both showed up in the data as "updated kitchen" and "new flooring." The model has no way to grade quality.
Where The Zestimate Falls Apart
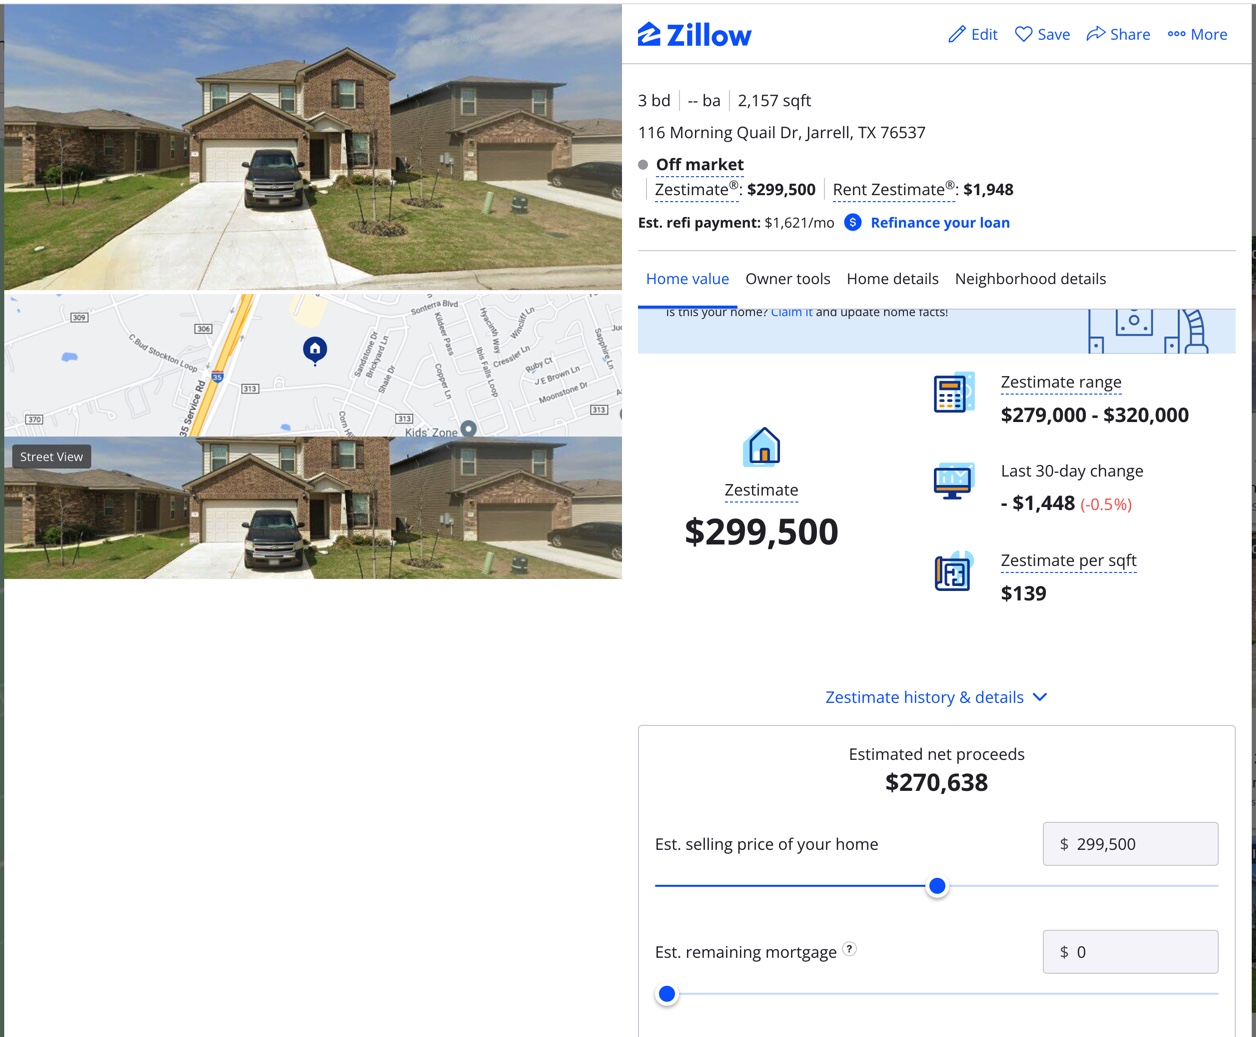
The median error rate for Zestimates on publicly listed listings is around six to seven percent according to Zillow's own published data. For off-market properties, the median error rate climbs to roughly eleven percent. Those numbers sound reasonable until you remember that eleven percent on a $400,000 home is a forty-four thousand dollar gap. In markets with thin transaction volume, like rural counties or newly developed subdivisions, the error rate can push past twenty percent because there simply aren't enough comparable sales to anchor the model. I ran into a specific case in central Ohio where the Zestimate on a custom-built home came in at $295,000. The property sat on three acres, had a commercial-grade HVAC system, and was built with materials that typically command a premium. The prior sale in 2018 had been at $310,000. There were no other comparable sales within a two-mile radius because the area was mostly agricultural land with scattered large lots. The Zestimate dropped the value because the model saw the surrounding comparable sales as lower-priced modest homes on smaller parcels, and it adjusted downward for lot size differences instead of upward for customization. A traditional appraisal using the sales comparison approach with proper adjustments came in at $365,000. That's a seventy-thousand-dollar difference driven by a model that was starved for relevant comparables and defaulted to a broad geographic adjustment instead of a fine-grained one. The workaround I used was straightforward but time-consuming. I pulled the county GIS parcel data, which showed the actual square footage and construction details that Zillow was missing. Then I manually identified twelve arms-length sales within a one-mile radius that shared the custom construction attribute. I fed those into a separate comparative market analysis spreadsheet with explicit adjustment matrices for lot size, square footage, age, and quality tier. The resulting value range sat between $355,000 and $380,000. That's still not a formal appraisal, but it's closer to reality than the Zestimate would have been.
Get the Full Details
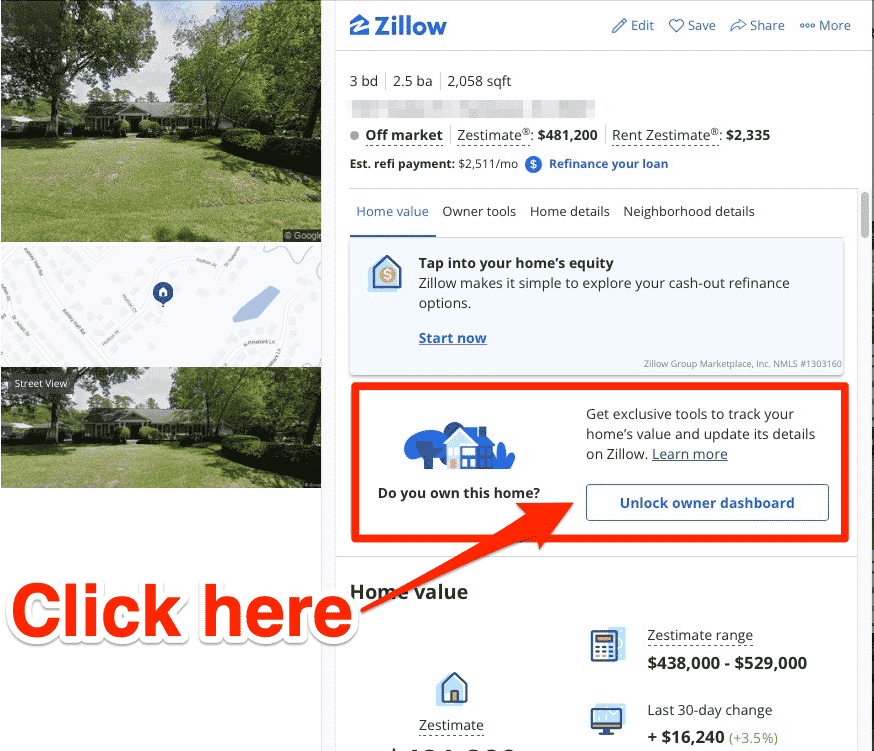
How To Use The Zestimate Without Getting Fooled
Treat it as a starting point, not an answer. The most useful application is relative comparison. If you're looking at five homes in the same neighborhood and their Zestimates move up or down in tandem with market shifts, the directional signal is probably reliable even if the absolute number is off. If one home's Zestimate spikes while the others stay flat, that's usually a data anomaly rather than a market move. Check the property record card on the county assessor's website and verify that the square footage, bedroom count, and improvement history match what Zillow is showing. I find about one in eight listings has a material error in the public data that propagates directly into the estimate. If you need a number you can actually rely on for a purchase decision or a refinance, get a real appraisal. Zillow offers a product called Zillow Offers, but they pulled out of the iBuying space in 2021, so that's not an option anymore. What they do offer now is a Zestimate tied to their mortgage and title services, which is still just the same algorithm with a different wrapper. For genuine accuracy, a licensed appraiser who visits the property and makes qualified adjustments to comparable sales is the only real alternative. A phone appraisal or desktop appraisal using local MLS data will cost you between two hundred and four hundred dollars and typically lands within three to five percent of the final sales price in balanced markets. One thing I've learned from watching this system evolve is that Zillow updates the Zestimate daily, but the updates are largely mechanical. They incorporate new public records filings and recent sales as those data points flow in from aggregators. The model doesn't "learn" in the way people imagine. It's not getting smarter about your neighborhood because someone sold a house on your block. It's just ingesting the new data point and letting the algorithm rebalance its weights across the entire dataset. That means a single high or low sale in a small market can skew the Zestimate for dozens of nearby homes for weeks until enough new transactions accumulate to dilute the outlier effect.
I watched this happen in a Nashville suburb in early 2024 when a distressed sale went through at forty percent below market value. The Zestimate on that property dropped sharply, and the adjacent homes' Zestimates drifted down by two to four percent over the following thirty days as the model continued to weight that transaction in its regression analysis. Once additional normal sales came in, the drift reversed. But in the meantime, anyone using those Zestimates for negotiation had a misleading reference point. The lesson is to check the sales history tab and look for any red-flag transactions that might be pulling the number in the wrong direction.