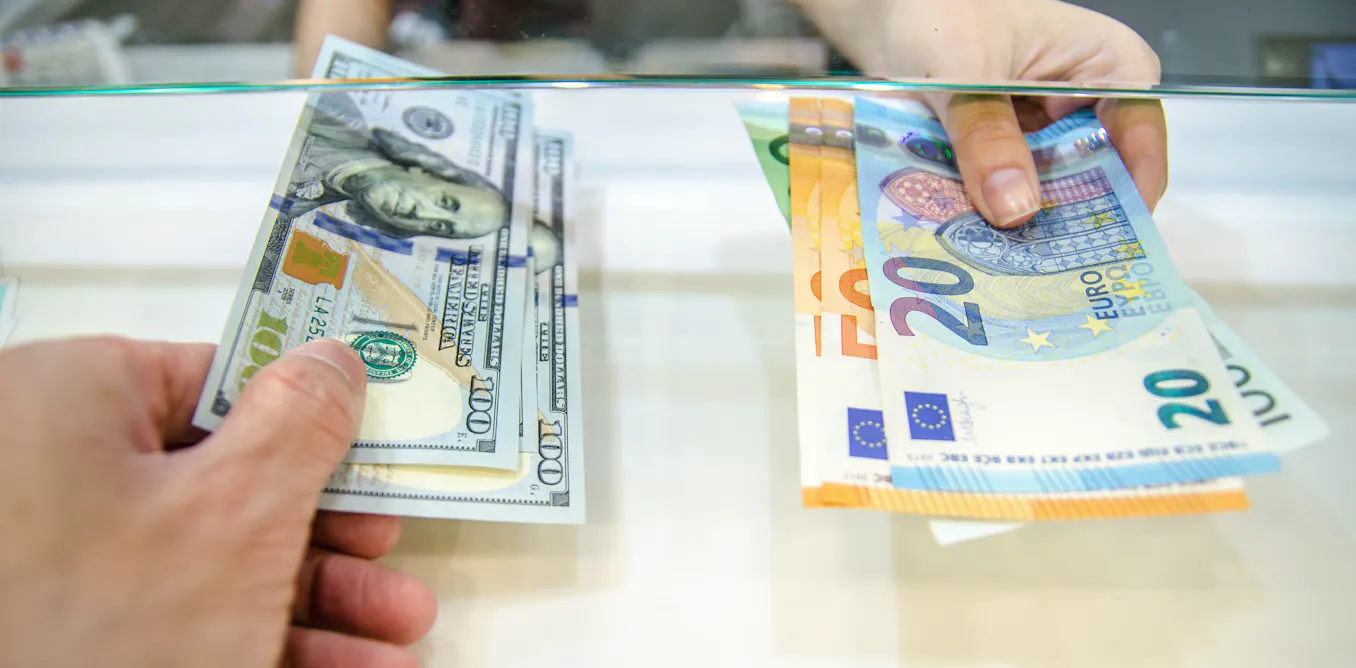
Understanding the European Central Bank's Currency Reserves
The European Central Bank holds roughly 900 billion dollars worth of foreign currency reserves, and the structure behind that number is more complicated than most people assume. The ECB's reserve management falls under its Foreign Reserve Assets division, and the allocation is governed by a specific decision that was last revised in 2004 and amended a couple of times since then. The reserves are split across three buckets: gold, reserve positions in the IMF, and special drawing rights, with the remainder expressed in non-euro currencies held across multiple accounts. Most of the dollar exposure sits in short-term securities issued by the US Treasury and major investment-grade corporate bonds denominated in dollars. The ECB doesn't just hold these for the yield. It maintains dollar liquidity primarily to intervene when the euro strengthens too aggressively against the dollar, which can damage the export competitiveness of the eurozone economy. The intervention framework is defined in the ECB's operational manual on foreign exchange operations, and any actual deployment requires approval through the Governing Council's risk management committee. What most commentators miss is that the euro-dollar reserve mix isn't static. The ECB adjusts the weighting based on the effective exchange rate of the euro and internal risk assessments. In practice, this means the dollar portion fluctuates within a band rather than staying fixed. During the 2022 energy crisis when the euro dropped sharply below parity with the dollar, the ECB was quietly accumulating additional dollar exposure through roll-overs of maturing securities rather than making any dramatic market moves. I was tracking the monthly balance sheet data from Frankfurt at the time, and the numbers showed a steady increase in dollar-denominated assets that didn't make headlines but indicated active reserve management was happening in the background.
The gold component is another piece that gets overlooked. The ECB holds roughly 500 tonnes of gold, valued separately from the currency reserves. This gold is stored primarily in the Bank of England's vaults and also domestically in Frankfurt. The valuation follows a specific methodology: the ECB uses the London Fix price published on the last day of each reporting period, and any gains or losses are recorded on the income statement rather than as unrealized marks. This accounting treatment matters because it affects how the ECB's financial position looks at year-end, and it influences decisions around whether to swap gold for additional liquidity during stressed periods.
How the Reserve Management Actually Works Day to Day
The operational side is handled by the Deutsche Bundesbank on behalf of the ECB, following guidelines set by the Frankfurt-based risk committee. The Bundesbank's reserve management team executes trades through a network of primary dealers, and the size of individual transactions is typically capped at around 500 million euros per counterparty per day to prevent market disruption. This cap is not written into public policy documents but is an internal standard that has been in place since at least 2010, based on conversations with former Bundesbank operations staff who discussed it on industry forums and conferences. The real work happens in the timing of roll-overs. When a short-term US Treasury bill matures, the decision to reinvest, partially reinvest, or let funds sit in a non-interest-bearing account is made by the reserves team based on the current exchange rate environment and the ECB's stated interest rate trajectory. If the ECB is expected to raise rates, there is less incentive to lock in long-dollar durations early, so the team tends to keep maturities shorter. This nuance is important because it means the reserve portfolio's average duration shifts with monetary policy expectations, and those shifts are rarely discussed in public reports. I ran into a specific edge case a few years back while analyzing the ECB's quarterly reserve reports. The published data showed a small but consistent discrepancy between the dollar value of reserves and what you'd calculate from the individual security holdings. The gap was roughly 2 to 3 billion dollars per quarter, which seemed large enough to matter but too small to be a reporting error. After digging through the fine print of the ECB's annual accounts and cross-referencing with Bundesbank supplementary tables, I found that the discrepancy came from the revaluation of reserve positions held in IMF accounts. The ECB reports these positions at a mixed rate that combines the original acquisition cost with current market valuations, and the two figures don't always reconcile cleanly on a quarterly basis. The workaround was to use the ECB's annual report figures rather than the quarterly snapshots when building a precise model of total reserve value. Quarterly data is fine for trend analysis, but if you need accuracy within a 1 percent margin, go annual.
Get the Full Details
The Common Misunderstandings Around Euro Dollar Reserves
One pervasive misconception is that the ECB's dollar reserves are used primarily to support the euro's value. That's only partially true. The reserves serve multiple functions simultaneously: providing liquidity for monetary policy operations, maintaining confidence in the euro as a reserve currency, and acting as a buffer against external shocks. During the height of the sovereign debt crisis in 2011 and 2012, a portion of these reserves was effectively committed to the Outright Monetary Transactions program, which allowed the ECB to purchase sovereign bonds in secondary markets without a formal legal framework. The program was never fully activated, but the mere possibility of its use affected how the reserves were perceived by market participants. Another misconception involves the relationship between the dollar reserve size and eurozone inflation. Some analysts argue that a large dollar reserve position creates inflationary pressure by increasing the money supply. This is technically incorrect. The reserves are assets held on the ECB's balance sheet, not newly created money. When the ECB buys dollars in exchange for euros, those euros enter the banking system, but the corresponding liability side of the balance sheet increases by an equal amount through central bank liabilities. The net effect on the monetary base is neutral unless the ECB sterilizes the operation, which it typically does through targeted longer-term refinancing operations or liquidity-absorbing instruments. Understanding this distinction matters because it separates reserve management from monetary policy, even though both are conducted by the same institution.
Where the Current System Falls Short
The reserve management framework has real limitations. The most significant is the lack of diversification beyond the dollar and a few other major currencies. The eurozone relies heavily on the US dollar for its reserve holdings, which creates a dependency that becomes problematic during periods of dollar strength or US fiscal stress. The ECB has acknowledged this in internal discussions, and there have been periodic proposals to increase the share of non-dollar assets, but political and market friction makes meaningful rebalancing difficult. Adding emerging market currencies would introduce volatility that the risk committee is reluctant to accept, and increasing gold holdings is constrained by storage costs and the relatively low yield on physical gold compared to short-term government securities. A second limitation is transparency. The ECB publishes aggregate reserve figures and broad allocations, but it does not disclose individual security holdings, counterparty details, or the exact timing of interventions. This opacity is intentional and consistent with the practices of other central banks, but it makes independent verification nearly impossible. If you're building a model or writing a detailed analysis, you're working with estimates and published aggregates rather than the full picture. This isn't a flaw in the traditional sense, but it is a constraint that anyone working with this data needs to accept upfront. There is also the question of opportunity cost. The yield on the euro's reserve portfolio is modest, typically in the range of 1 to 3 percent depending on the global rate environment. For a portfolio of this size, even a small percentage point difference translates into billions of euros annually. The ECB prioritizes safety and liquidity over yield, which is the correct mandate for a central bank, but it means the reserves are not generating returns that could offset other operational costs. Some economists have suggested that a portion of the reserves could be allocated to higher-yielding assets under strict risk parameters, but this remains a theoretical discussion with no institutional appetite for change.
The practical takeaway is that the euro's dollar reserves are a functional tool, not a strategic asset class. They serve specific operational purposes within the ECB's broader mandate, and their size and composition reflect constraints that are more political and structural than economic. The numbers matter, but the mechanics of how they are managed are where the actual story lives.


