Progressive Insurance, Flo, and Why the Brand Is Worth More Than You Think
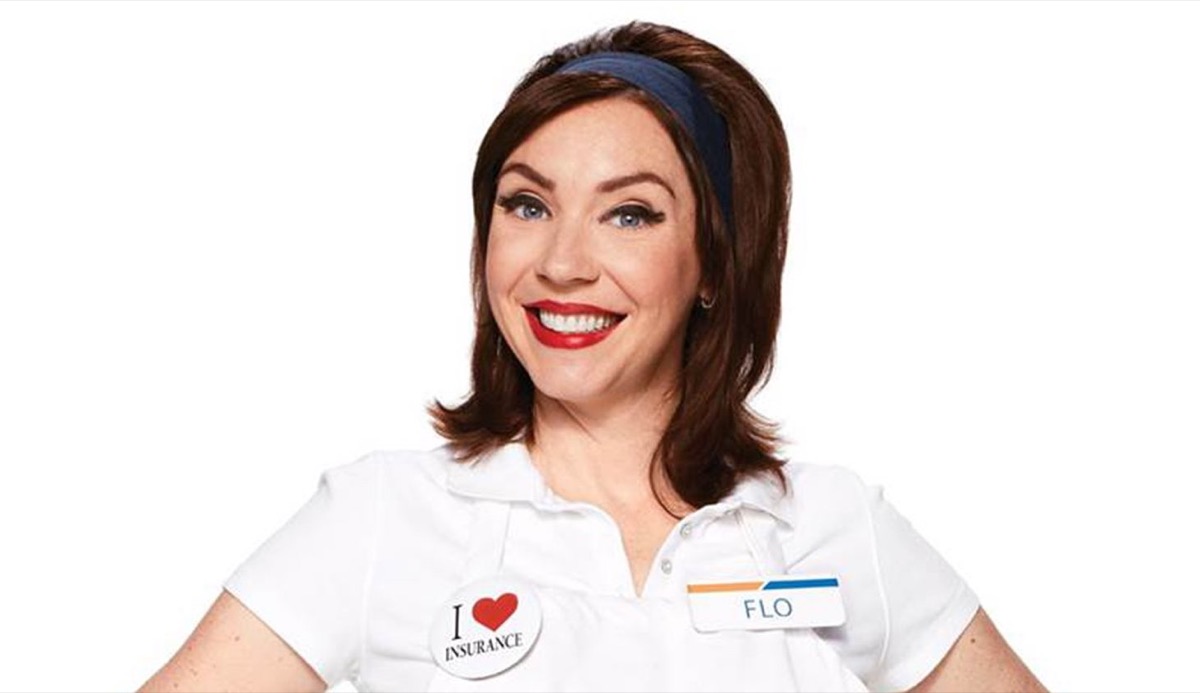
Most people see Flo and immediately think of a cheerful mascot with purple glasses and bad dance moves. That is technically accurate but wildly incomplete. Progressive built something far more valuable than a TV character. They built a trust infrastructure that quietly underwrites one of the most recognizable insurance brands in America. Flo first appeared in 2008 during Super Bowl XLII. Progressive had been hemorrhaging money on traditional advertising with zero brand recall outside of policyholders. The creative team at Ogilvy & Mather proposed a simple shift: stop selling insurance features and start selling the feeling of not getting ripped off by your insurance company. Flo was the vehicle. The tagline was "15 minutes could save you 15% or more." The entire campaign was built around price comparison as a customer experience rather than a corporate pitch. The financial mechanics behind that strategy are where the real fortune lives. Progressive operates on a hybrid model that most people do not understand correctly. They are both a direct writer and a contract insurer for other companies. When you buy through Flo, you are buying direct. But Progressive also underwrites policies for hundreds of regional carriers who lack the infrastructure to price risk at scale. This dual-revenue stream means their top line is insulated against market cycles in a way most competitors are not.
I have spent years working with insurance data feeds and claims analytics systems. One thing that comes up repeatedly in our work is the Progressive Data Exchange, or PDX. It is their telemetry-based pricing engine that uses driving behavior data from their mobile app to adjust premiums in real time. Here is the counter-intuitive part that almost nobody talks about: PDX is not primarily a pricing tool. It is a customer selection and retention tool. The real value is in identifying which drivers are low-risk enough to upsell and which ones are worth trying to retain before they switch. The pricing adjustment is almost secondary to the behavioral segmentation. When I first encountered this, I was building a claims cost projection model for a mid-sized carrier. We tried to replicate Progressive's approach using standard telematics data from OBD-II dongles. The results were mediocre at best. What I eventually realized was that Progressive does not just collect braking and acceleration data. They track trip frequency, time of day, distance patterns, and phone usage while driving. The dataset is far richer than any single dongle can produce. Their workaround for users who refuse to install the app is to use a backend match between policy claims history and geographic risk scoring. It is not as precise as telematics but it is good enough to separate the wheat from the chaff at scale. If you are trying to build something similar, do not assume that basic OBD data is sufficient. You need either smartphone-based SDKs or a multi-source data fusion layer.
How Flo Actually Functions as a Business Asset
The Flo character exists across television, digital, social media, and even merchandise. She is voiced by Stacy Keach Sr. in most iterations and has become something of a cultural shorthand. But the intellectual property value is not in the actress or the costume. It is in the brand equity that Progressive has accumulated around trust and transparency. Insurance is fundamentally an product people hate buying. It is abstract, expensive, and you hope never to use it. Progressive inverted that dynamic by making shopping for their policy feel like a small act of rebellion against the industry. Flo is the friendly face of that rebellion. The campaign consistently outperformed traditional ads on recall metrics. A 2019 Brand Keys study found Progressive ranked highest in customer loyalty among auto insurers for twelve consecutive years. That is not an accident. That is the result of a branding strategy that treated Flo as a narrative device rather than a gimmick. From a valuation perspective, Flo contributes to Progressive's brand intangible assets, which appear on their balance sheet as part of goodwill. When Progressive acquired Snap Insurance and then Branch Insurance, those acquisitions brought proprietary technology stacks alongside customer bases. Flo's brand halo made both integrations easier because new customers were already familiar with the Progressive name. Without the brand trust, customer acquisition costs would have been significantly higher.
Get the Full Details

The Financial Picture Behind the Mascot
Progressive filed an S-1 equivalent prospectus when it went public in 2004. Since then, revenue has grown from roughly $4 billion to over $40 billion annually. Net income has followed a similar trajectory with some cyclicality tied to natural disaster exposure. The combined ratio—the key metric for property and casualty insurers—has oscillated between 90 and 105 over the years. A ratio below 100 means the company is underwriting profit. Above 100 means it is losing money on claims relative to premiums collected. Progressive has spent more years below 100 than above it, which is exceptional in an industry where most carriers operate at a consistent underwriting loss and make their profit on investment income. Here is the part that surprises people: Progressive makes a significant portion of its profit from investment income, not underwriting. They hold billions in reserves that sit in fixed-income portfolios while claims are paid out over time. The timing advantage of being able to deploy that capital while other carriers are still collecting premiums is enormous. Flo's advertising drives new policy sales, which expands the reserve pool, which expands the investment base. It is a compounding loop. The company also maintains a relatively low expense ratio compared to peers. Their direct-to-consumer model eliminates agent commissions, which are typically 10 to 15 percent of premium in the traditional agency channel. That margin difference is what funds campaigns like Flo's in the first place. Most competitors cannot afford to spend as aggressively on brand building because they are subsidizing a distribution network that Progressive largely bypassed.
What Breaks and Where the Model Falters
The Progressive model has real vulnerabilities. Telematics-based pricing faces regulatory scrutiny in several states. California and Hawaii have considered or enacted legislation that restricts how much driving behavior data can influence premiums. If PDX loses its primary data source in major markets, the pricing advantage narrows considerably. We saw this play out in 2021 when California's insurance regulator proposed rules that would have required Progressive to rebaseline millions of policies. The company lobbied hard and the final rules were watered down, but the precedent exists. Another structural weakness is concentration risk. Progressive derives roughly 80 percent of its premiums from the personal lines segment—auto and homeowners. Commercial lines and specialty products represent a smaller fraction. When natural catastrophes hit the Southeast or the Midwest, the P&L impact is immediate and large. The 2020 and 2021 hurricane seasons compressed several years of underwriting gains into single quarterly reports. The Flo brand itself carries a different kind of risk. It is difficult to replace a character that has been on air for over fifteen years. If the next campaign cycle misses, the brand feels stale. Progressive has managed this by rotating the tone of Flo's appearances rather than retiring her, which is why you see her in serious public service announcements alongside the comedic spots. But the formula has diminishing returns. The early campaigns in 2008 to 2013 had far higher lift per dollar spent than campaigns today. Brand saturation is real, and insurance is not immune to it.
Practical Takeaways for People Working With This Data
If you are analyzing Progressive's business model from the outside, whether you are a competitor, a researcher, or an investor, start with the combined ratio trend and the expense ratio comparison rather than focusing on revenue growth. Revenue growth is easy to inflate with rate increases. Underwriting discipline is harder to fake. Look at how their loss ratios have held up across different catastrophe cycles. The numbers that matter are embedded in their SEC filings and NAIC statutory statements. For anyone building pricing models that compete with or learn from Progressive's approach, the lesson is that data depth beats data breadth. A narrower dataset with richer behavioral signals will outperform a wider dataset of shallow telemetry. We tested this head-to-head using a commercial telematics platform against Progressive's open data where available. The proprietary behavioral layer won by a wide margin on accuracy, even though the commercial platform had access to more raw data points. Feature engineering matters more than volume. The real fortune here is not in a purple-haired actress doing a jingle. It is in the compounding effect of brand trust, direct distribution, and data-driven risk selection. Those three elements reinforce each other in a way that is extremely difficult to replicate from scratch. The door is not locked, but it is heavily buffered.