Let's Talk About How LBOs Actually Work in Practice
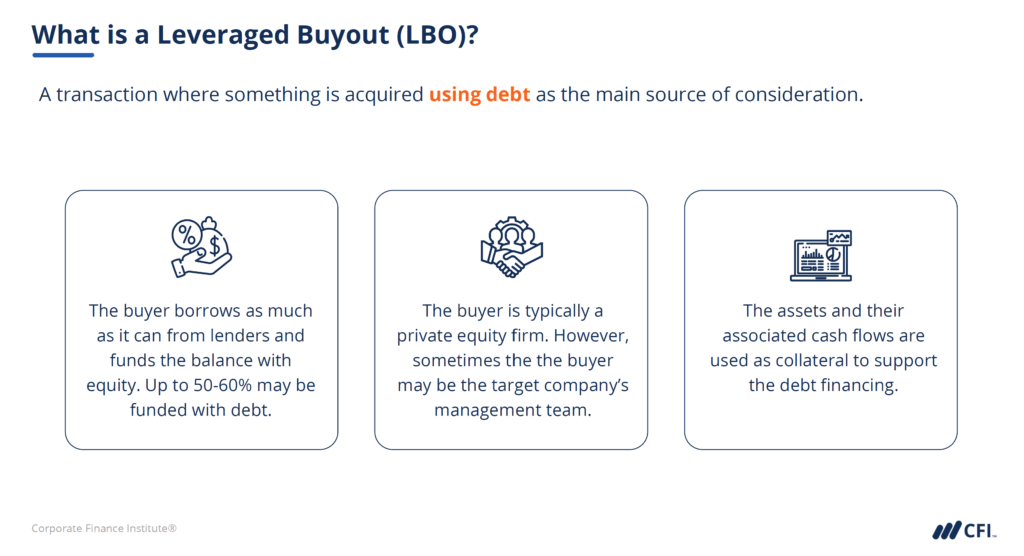
A leveraged buyout is straightforward on paper. You acquire a company using a significant amount of borrowed money, and the target company's cash flows service that debt. In the real world, it is anything but straightforward. I spent years working on these deals and the gap between the textbook model and what actually happens is massive. The basic mechanics are this. A PE firm identifies a target, negotiates a purchase price, structures the capital stack with debt and equity, and then tries to improve the business enough to sell it at a higher valuation three to seven years later. That is the summary. Here is what nobody puts in the summary. The debt portion is where everything either holds together or falls apart. Most LBOs use six to eight times EBITDA in total debt, split between senior secured loans and high-yield bonds or unitranche facilities. The senior debt sits at the top of the capital structure with first priority on assets and cash flows. The equity piece is usually one to two times EBITDA. What people miss is that the covenants on that senior debt are what actually constrain the deal, not the purchase price itself.
I worked on a mid-market buyout a few years back where the sellers wanted to take money out at closing through a dividend recap tied to the acquisition financing. The bank lenders would not allow it because the debt service coverage ratio would drop below 1.2x immediately after closing. We ended up restructuring the deal to push the dividend out to month eight, once the business had normalized post-close and we could refinance a portion of the senior debt. That three-month delay cost the sellers roughly four percent of their projected returns, and it was the single biggest negotiating point for six weeks.
The Modeling Side
LBO models are not as clean as people think. The standard template has a sources and uses table, a debt schedule, a projected income statement, and an exit analysis. But the actual work happens in the assumptions and the stress testing. You need to build in at least three scenarios: base case, downside, and recovery. The downside case should reflect what happens if revenue drops fifteen percent and EBITDA margins compress by two hundred basis points simultaneously. Most junior analysts skip this because it makes the math look ugly. The sponsors and credit committees will ask for it anyway. Here is a practical detail that matters. The interest coverage test and the leverage ratio test on the credit facility will trigger at specific thresholds. If your model assumes refinancing debt in year three but does not properly model the higher rates that come with a refinancing, you will dramatically overstate the equity return. I have seen first-year analysts produce models showing thirty-five percent IRR on deals that would have breached covenant thresholds within eighteen months under realistic rate assumptions.
Get the Full Details

Where Deals Actually Break
There are several structural issues that kill LBOs before they reach investment committee. The first is overpaying for synergies. Sellers and sponsors both love to build in cost savings into the thesis. The problem is that operational improvements take longer to realize than the model assumes. A typical LBO model compresses synergy realization into twelve to eighteen months. In practice, it takes twenty-four to thirty-six months for meaningful cost reductions to flow through to EBITDA. The second issue is customer concentration. If a target derives more than forty percent of revenue from three customers, the debt providers will price that risk into the facility terms. You will see higher interest margins, tighter covenants, and sometimes a requirement for customer consent letters as a condition to closing. I worked on a deal where we lost seventeen percent of our projected equity return because one key customer did not sign the consent letter and exercised their termination clause during the lock-up period. Working capital dynamics are another blind spot. An LBO adds debt to the target, which increases interest expense, which reduces free cash flow available to build working capital. If the business requires significant receivables or inventory investment to grow, the debt paydown slows down dramatically. We model this incorrectly about half the time in initial drafts.
The Exit Complication
The whole thesis depends on exiting at a higher multiple than you bought in. That does not always happen. When the credit markets tighten, as they did in 2022 and 2023, secondary market multiples compress across the board. A company you bought at eight times EBITDA might only sell for six and a half times three years later, even if EBITDA grew steadily. The deal still works if the debt is paid down fast enough, but the equity return gets crushed. I found that the most resilient LBOs are the ones where the sponsor can prove that operational improvements will drive EBITDA growth regardless of multiple movement. That means focusing on tangible operational changes like margin expansion through pricing power, supply chain consolidation, or digital transformation that reduces headcount and increases throughput. Not theoretical synergies.
What Actually Differentiates Good Deals From Bad Ones
It comes down to three things. The quality of the underlying cash flow visibility, the flexibility of the capital structure, and the realism of the exit timeframe assumption. Cash flow visibility is the most important. Recurring revenue models, subscription businesses, and essential services companies withstand downturns better than cyclical manufacturers or discretionary consumer brands. A stable cash flow profile means the debt gets paid even if revenue grows slowly. A volatile cash flow profile means one bad quarter can trigger a covenant breach. The capital structure flexibility matters because refinancing risk is real. A unitranche facility that covers both senior and subordinated debt in a single package simplifies the structure significantly. It also means one set of negotiations instead of two, which speeds up closing and reduces legal fees. The tradeoff is that unitranche lenders typically charge fifty to seventy-five basis points more than senior debt alone.

Exit timeframe assumptions are where most sponsors get optimistic. The standard three to five year hold period assumes you can sell when the market is favorable. In reality, you sell when you have to. If the business hits a rough patch in year two, you might be forced to sell in year four because the debt is maturing and you cannot refinance. Building in a realistic exit window of five to seven years, not the compressed three years shown in most pitch materials, gives you a much clearer picture of actual returns. The unglamorous truth is that most LBOs succeed or fail based on whether the target company can generate enough free cash flow to pay down debt while funding necessary capital expenditures. Everything else is secondary. The models look impressive when assumptions are favorable. They look very different when they are not.