Why Your Net Worth Number Looks Wrong Most of the Time
Most people calculate their net worth once a year, around January, when they're feeling either generous or cruel to themselves. They add up their checking account, throw in the car value from Kelley Blue Book, guess at their retirement balance, and subtract the mortgage. Then they stare at a number that feels both accurate and completely useless. I've been doing this since 2008, and the version that actually works for me looks nothing like a spreadsheet someone downloads from the internet.
Unlocking The Secrets Of Net Worth A Comprehensive Guide To Tracking Your Financial Freedom
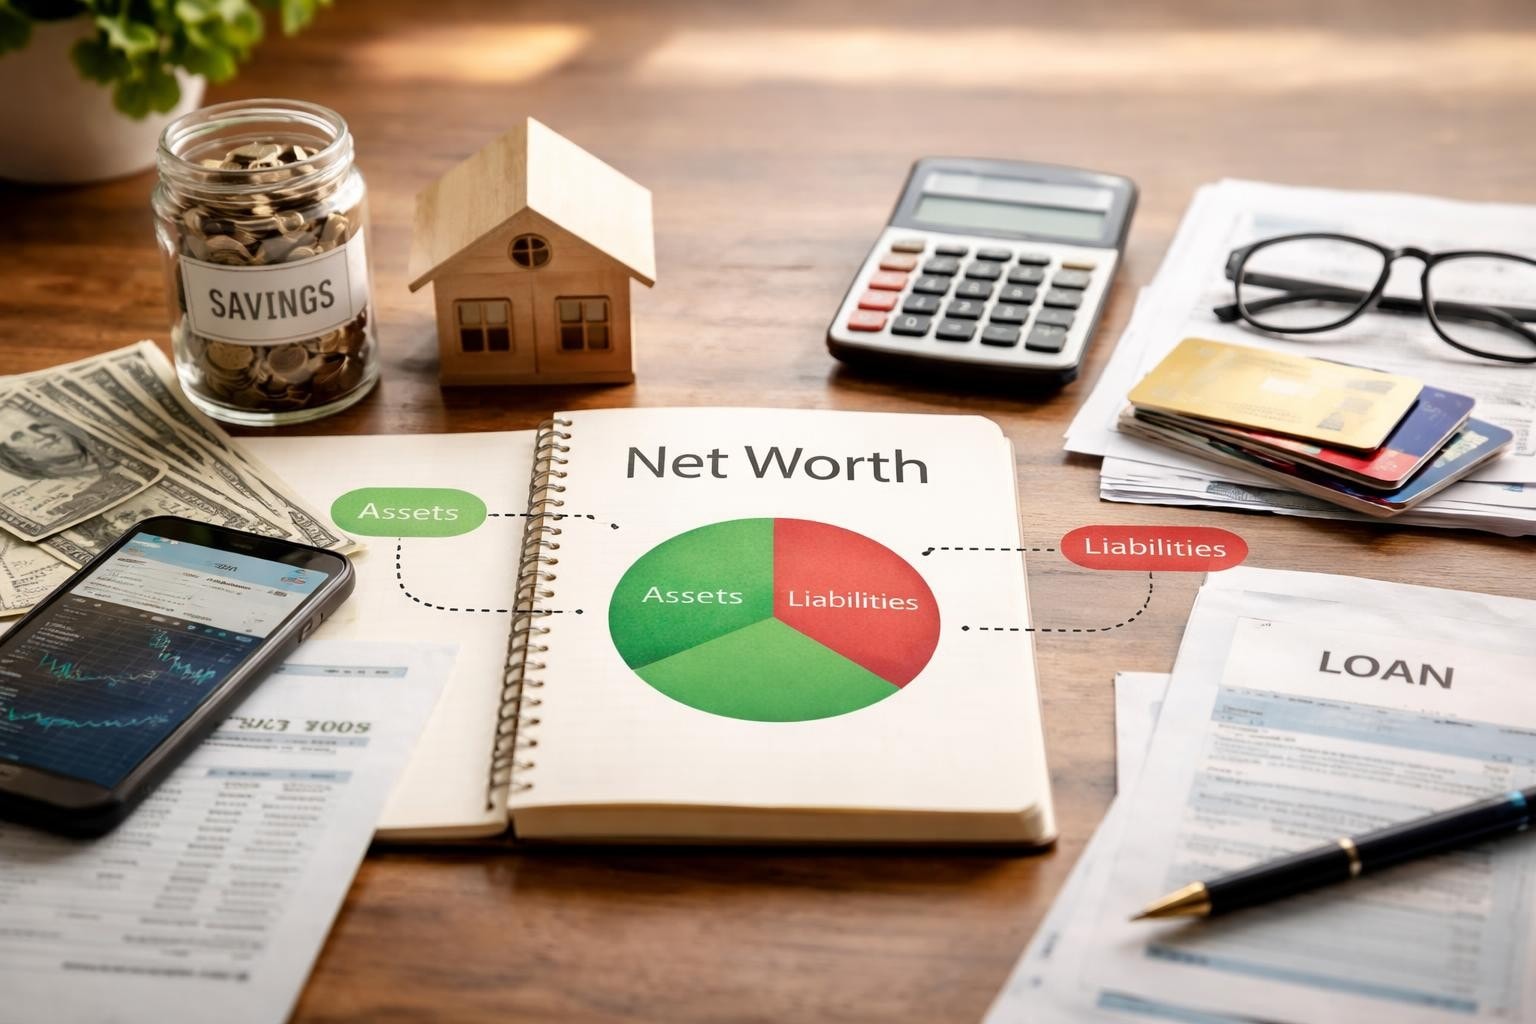
Net worth is just assets minus liabilities. That's the textbook answer and it's technically correct, which means it's also practically useless if you don't know what to include and how to value it. The real work isn't the subtraction. It's the categorization and the valuation frequency. Your primary residence should be tracked at market value, not what you paid for it. Your car should be tracked at replacement cost or current resale value, not the depreciation schedule your lender sent you. This distinction matters more than most people realize because it changes the trajectory of your number by thousands of dollars each year.I learned this the hard way in 2015. My net worth appeared to drop by forty thousand dollars in a single quarter. I panicked, pulled statements, reconciled everything twice, and still couldn't find the error. It turned out I'd been valuing my house at its assessed tax value instead of current market value. The market had shifted, my property assessment hadn't, and my tracker was lying to me. I switched to Zillow's estimate as a baseline and confirmed with a quick comparison of recent comp sales in my neighborhood. That single change made my net worth tracker actually reflect reality instead of generating anxiety.
The Categories That Actually Matter
You need four buckets. Liquid assets, which includes checking, savings, money market, and anything you can access within seventy-two hours without penalty. Investment accounts, which means brokerage, retirement accounts, and any other place where money is working for you but isn't immediately spendable. Real property, your home and any other structures you own. Personal property, which is everything else: vehicles, equipment, jewelry, collectibles. And on the liability side, three categories: consumer debt, which is credit cards and personal loans; secured debt, which is your mortgage and auto loans; and any other obligations you can't easily categorize.The trap most people fall into is tracking personal property too frequently. Your furniture lost half its value the moment you bought it. Tracking it monthly gives you false precision and wastes time. Do it once a year during a proper walkthrough, or skip it entirely if the total isn't going to move the needle on your overall number. I stopped tracking my car contents two years ago. The category is called "personal effects" and the value is essentially zero in any meaningful calculation.
How To Actually Build This Without Losing Your Mind
Start with a simple spreadsheet. Not a fancy app, not a subscription service, just a Google Sheet you control. Set up columns for each asset and liability category, rows for individual accounts, and a formula that sums everything. Use three sheets: one for your current snapshot, one for monthly tracking, and one for historical quarterly comparisons. That's it. You don't need Mint. You don't need a subscription tool that syncs with your bank and then loses the connection every time the institution updates its API.Get the Full Details
I've used three different tracking tools over the years. One was a desktop application that imported directly from my bank. It worked for eleven months before the bank changed its authentication method and the import broke. I spent two weeks rebuilding the connection and then the tool stopped updating entirely. Another was a cloud-based platform that pulled data automatically. It was convenient until it misclassified a $40,000 investment account as a checking account for three months, which made my liquid asset number look completely wrong. The third is the spreadsheet I described above, and it hasn't failed me once because the data entry is manual and I verify it myself. Here's the practical workflow. Every Sunday evening, you'll spend about twelve minutes updating your sheet. Log into each account, note the balance, enter it. That's the entire process. Twelve minutes. If you have more than ten accounts, it might take twenty. If you have fewer than five, it might take eight. The consistency matters far more than the speed. I've seen people build elaborate automated systems that they maintain for three months and then abandon because the setup was too complex. The twelve-minute Sunday ritual beats the twelve-hour setup every time.
The Counter-Intuitive Part Nobody Talks About
Your net worth number will lie to you regularly, and that's not a bug, it's a feature of how markets work. When your retirement accounts drop twenty percent in a bad month, your net worth drops too. This is normal. The mistake people make is reacting to short-term volatility as if it represents a structural problem. In 2022, the S&P 500 dropped roughly nineteen percent. People who checked their net worth weekly during that period reported significant declines in financial well-being, even though their spending habits and employment status hadn't changed at all. The number moved. Their life didn't. Another thing that catches people off guard: paying down debt shows up in your net worth immediately, but investing shows up slowly. When you pay off a $5,000 credit card balance, your net worth goes up $5,000 instantly. When you invest $5,000 in a diversified portfolio, your net worth goes up $5,000 instantly, but the growth component is invisible month to month in a down market. This asymmetry makes debt payoff feel more rewarding than it actually is relative to the long-term math. Both actions improve your net worth by the same dollar amount. The difference is in the return trajectory over decades, not in the immediate number on your screen.
What This System Can't Do For You
A net worth tracker doesn't tell you whether you're on track to retire. It doesn't predict market crashes. It doesn't help you decide between a higher deductible and a lower premium. It tells you one thing: where you stand right now. That's it. The limitation is fundamental. Any system that claims to do more than that is selling you something. If you're carrying high-interest consumer debt, your net worth tracker will show you improving slowly because the interest is eating your assets faster than you're building them. This is accurate information, but it's also demoralizing if you're not paired with a specific debt elimination plan. The tracker shows the problem. It doesn't solve it. For that you need a separate framework: the avalanche method or the snowball method, depending on whether you prioritize mathematical efficiency or psychological momentum. I recommend the snowball method for most people because adherence matters more than optimization. A suboptimal plan you actually follow beats a perfect plan you abandon after six weeks.
The Edge Case That Broke My Spreadsheet
In 2020 I inherited a small rental property from my grandmother. It came with a tenant already in place, a modest mortgage attached, and a property tax assessment that was significantly below market value. I didn't know how to value it in my spreadsheet. Should I use the assessed value? The market estimate? The rent multiplier? I spent an afternoon researching and settled on using a simple cap rate calculation based on local comparable properties. Annual net operating income divided by an appropriate cap rate gave me a reasonable estimate. I recorded it as a line item under real property with a note explaining the methodology. Six months later, I refinanced the property and the appraised value came in at almost exactly what I'd estimated. The workaround wasn't elegant but it was functional. This experience taught me that edge cases exist in every person's financial life. Student loan debt that's in deferment. A business partner you co-own property with. Cryptocurrency held on an exchange that no longer exists. The spreadsheet needs to be flexible enough to handle these without collapsing into complexity. Add a notes column. When something is unusual, document how you valued it and why. Next year when you revisit the same line item, you'll know exactly what you did and can assess whether it still makes sense.
How Often To Track and What To Do With the Data
Track weekly for the first three months. This builds the habit and reveals patterns you wouldn't catch with monthly check-ins. After that, monthly is sufficient. Quarterly review is where the actual analysis happens. Look at your trend line. Is it moving in the right direction? Are there categories that are fluctuating unexpectedly? If your investment accounts are down fifteen percent quarter over quarter, ask yourself whether this is market movement or a structural shift in your allocation. If your consumer debt is growing despite consistent payments, something is wrong with your budget or your income, and the net worth tracker has just handed you the evidence. Use the quarterly review to set one financial decision for the next three months. Not three decisions. One. Pay down a specific balance. Transfer a specific amount to savings. Refinance a specific loan. The tracker gives you the baseline. The decision is where action begins. Without the decision, the tracker is just a mirror. With it, the tracker becomes a steering wheel.