Pay Stubs Are Confusing On Purpose And Also Because Payroll Vendors Don't Care About Clarity
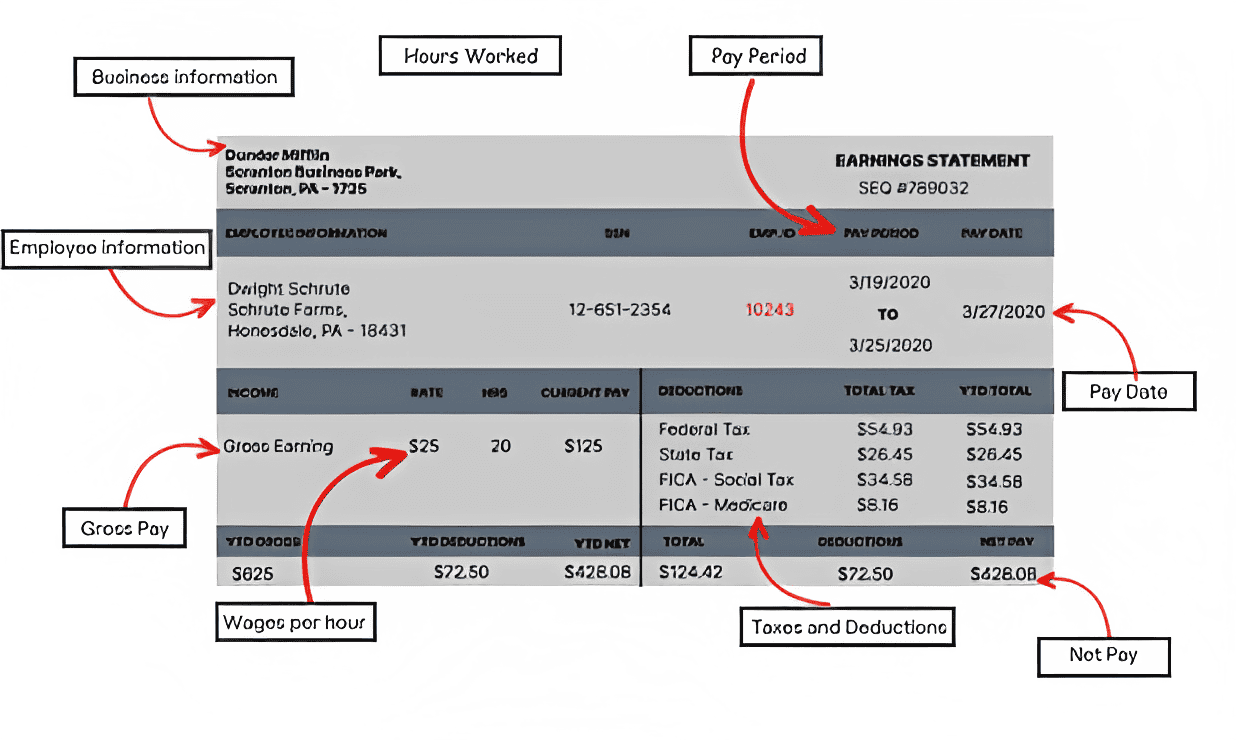
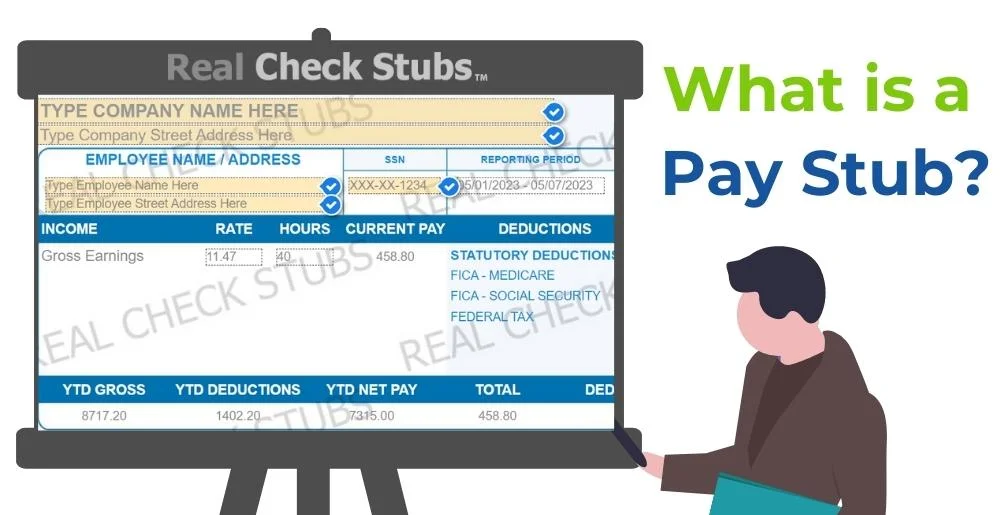
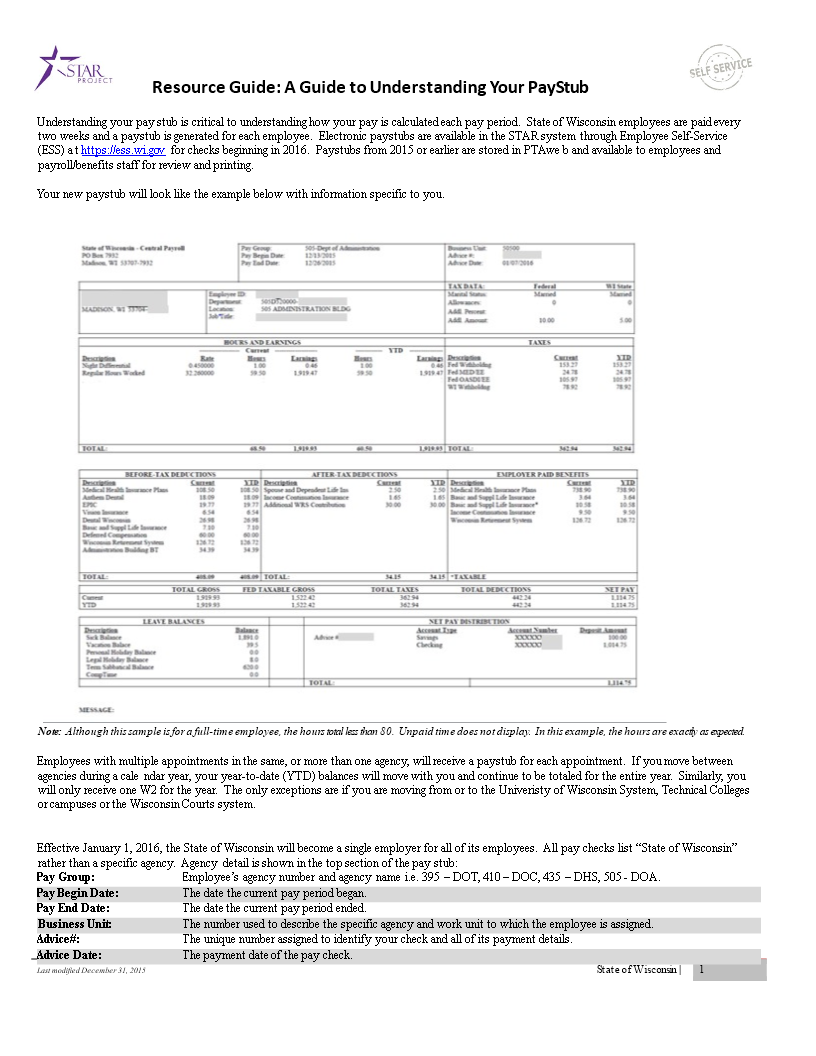
I spent three years troubleshooting payroll errors for small businesses before I just learned to read the damn thing directly from the source report instead of waiting for HR to decode it. Most people look at their paystub and see a wall of numbers that go nowhere. That is not your fault. Payroll systems are designed by software engineers who optimize for tax compliance, not human readability. Here is how you actually break it down without losing your mind. Start with the header section. Ignore everything else for a moment and look at the pay period dates, your gross earnings, and the year-to-date totals. Those three data points tell you whether the stub is even from the right period. I once spent forty-five minutes chasing a missing bonus payment only to realize the stub I was looking at was from two pay cycles earlier. My employer uses ADP and their interface shows the most recent transaction by default, but if you pull a PDF archive, the dates are easy to misread. Always verify the pay period first. It saves time you will never get back. The gross pay line is not your salary divided by the number of pay periods. That assumption breaks immediately when you have overtime, shift differentials, commission draws, or any kind of variable compensation. If you are hourly, gross pay equals your regular hours plus any overtime hours at the correct multiplier plus any other earnings codes. If you are salaried and your gross does not match your expected amount, do not assume the check is wrong yet. Check whether your employer uses a 26-pay cycle or a 24-pay cycle. Some companies round to the nearest biweekly period and that rounding creates a half-period gap that shows up as an unexpectedly high or low gross amount on one stub. This is not an error. It is a scheduling artifact.
Reading The Deductions Section Like A Person Who Has Seen Too Many Errors
Deductions fall into three buckets: mandatory withholdings, voluntary benefits, and wage garnishments. Mandatory withholdings are federal income tax, Social Security, and Medicare. State and local taxes vary by jurisdiction. If you see a deduction labeled something opaque like FICA or RRTA, that is the railroad retirement equivalent of Social Security and Medicare. It shows up if you work for a railroad employer or certain cooperative enterprises. Most people do not encounter this and then panic when they see it on their stub. Voluntary deductions include health insurance premiums, 401k contributions, flexible spending accounts, and dental or vision plans. The tricky part is that some of these are pre-tax and some are post-tax. Pre-tax deductions reduce your taxable income. Post-tax deductions do not. If your health insurance premium is listed as a pre-tax deduction under section 125 or a cafeteria plan, that is normal and it lowers your overall tax burden. If it is listed as post-tax, your employer may be running a different plan structure or you may have opted out of the pre-tax election. I had a contractor once who thought his employer was overcharging him for health insurance because the premium appeared larger on his stub than his spouse's. It turned out he had chosen a single plan while his spouse had family coverage and the system was displaying the full family premium before any employee contribution split was applied. The fix was simply opening the benefits portal and checking the actual enrollment level.
The Net Pay Line Is Not What You Think It Is
Net pay is gross minus all deductions minus any wage advances or reimbursements that were deducted this period. It is the amount that actually hits your bank account or check. People often mistake net pay for their take-home after taxes alone. That is wrong. If you have a 401k contribution, a Roth IRA deduction, a student loan wage repayment, or a union dues line item, all of those come out before net pay. The number at the bottom is your actual cash. Everything above it is either going to the government or being routed into accounts you will see later. Year-to-date columns matter more than people give them credit for. If you are negotiating a raise or applying for a loan, the YTD total on your stub tells the lender exactly how much you earned in the calendar year. Do not send them a single pay stub and expect that to represent your annual income. Lenders typically want at least two consecutive stubs to calculate your average monthly earnings. Some will ask for a W-2 instead if you have been with the same employer for a full year. The stub is useful for new hires or people who change jobs frequently. After that, the W-2 is cleaner.
Get the Full Details
When Your Paystub Shows Something That Makes No Sense
Here is a specific edge case I ran into recently. A client received a stub where the federal tax withholding was roughly double what it should have been based on his W-4 elections. He had submitted a new W-4 with three withholding allowances and a lower exemption range, but his previous year had used the old allowance system. The payroll vendor, which was a smaller provider that my client's employer had switched to two years prior, had not properly converted the W-4 data during the migration. The result was excess withholding that compounded every pay period. I had him pull his direct download from the vendor's portal, cross-reference the W-4 on file against his submitted form, and then escalate through his employer's payroll administrator. The fix took eleven days and required a corrective run in the next pay cycle. If you catch this early, you can request an estimated tax payment adjustment or claim the excess on your return, but correcting it before year end is cheaper than dealing with an overwithholding complaint at tax time. Another common issue is when your paystub shows zero overtime but you worked over forty hours. This happens frequently with commissioned or piece-rate workers whose employers classify them under a different overtime calculation method. Some employers use a fluctuating workweek method where overtime is calculated at half-time rather than time-and-a-half. Your stub may show a lower overtime line than expected because the base rate is already inflated to include a portion of overtime compensation. This is legal under certain conditions but it requires that your regular rate of pay exceeds minimum wage and that overtime is still paid at the correct half-time rate on the additional hours. If your employer cannot produce the calculation, ask for it in writing. Most won't produce it, and that is a red flag worth escalating.
What Paystubs Will Never Tell You
A paystub does not show your true annual compensation. It does not include employer-paid benefits like workers compensation insurance, unemployment insurance, or the employer match on your 401k unless your employer chooses to disclose it separately. It does not show stock option grants or restricted stock units. It does not reflect unearned commission or bonus accruals. If you are trying to understand your full compensation package, the paystub is one piece of a much larger puzzle and relying on it alone will give you an incomplete picture that undersells your actual earnings. Some payroll providers also do not display your tax withholding breakdown by state and locality in sufficient detail. If you live in a city with a municipal wage tax or a school district tax, your stub may lump all local taxes into a single line item. When you file your state return, you may need to pull the detailed breakdown from the payroll vendor's portal or request a printed report that itemizes each jurisdiction. The stub is a summary, not a legal filing document in most cases.