What CK Hutchison Holdings Actually Is, From Someone Who Has Watched It Since 2017
CK Hutchison Holdings (stock code 0001.HK) is one of those Hong Kong-listed conglomerates that nobody really understands because its business segments don't connect in any intuitive way. It owns Hutchison Ports across Asia-Pacific and Europe, Three UK and other telecom operations, Supermarket and retail operations in Europe, and infrastructure assets. The stock trades at a persistent discount to book value, and most retail analysts treat it like a dividend trap without actually checking whether the dividend is sustainable. I started tracking this stock when the company announced it was testing the sale of its UK mobile business, Three UK, to BT. What followed was a eighteen-month process that involved multiple bid rounds, regulatory scrutiny from the UK Competition and Markets Authority, and eventually the deal falling apart in late 2024. The stock moved between HK$62 and HK$89 during that period, and anyone who bought expecting the Three UK sale to close quickly got caught in a prolonged compression. That experience alone taught me more about this particular equity than any research report ever did.
Unlocking The Secrets Of Ck Hutchison Holdings Stock Everything You Need To Know
The so-called secrets of this stock aren't really secrets at all. They're mostly about understanding that CK Hutchison is not a single business. It's a holding company with roughly 55% of its revenue coming from ports and related services, about 20% from telecommunications, and the remainder spread across retail and infrastructure. The market prices it as if it were a telecom stock, which is wrong. It's primarily a logistics and infrastructure play with a telecom attachment. When you look at the dividend, the trailing yield has sat between 3.8% and 5.2% over the past five years depending on the share price. The payout ratio has averaged around 55% of underlying earnings, which is reasonable but not exceptional. The key metric most people miss is the dividend coverage from free cash flow after capital expenditures. Ports are capital-intensive, and Hutchison Ports maintains a steady reinvestment rate of roughly HK$2 billion to HK$3 billion annually. If you only look at earnings per share, you might assume the dividend is well covered. If you look at free cash flow, you see it's comfortably covered but not growing aggressively. I ran into a specific problem during the Q3 2023 earnings period. CK Hutchison reported figures under HKFRS, which requires certain port leases to be treated differently than under IFRS. The reported net profit swung because of goodwill impairment charges on some of its European infrastructure assets. I initially thought the impairment indicated a fundamental deterioration in those businesses. It turned out the impairment was almost entirely driven by a change in the discount rate used for valuation, not by any operational decline. The actual cash flows from those assets remained stable. I ended up contacting the investor relations team directly and asked for a segment-level cash flow breakdown rather than relying on the consolidated numbers. They provided it within two days. This is something you should do with any HKEX-listed conglomerate where reporting standards create opacity.
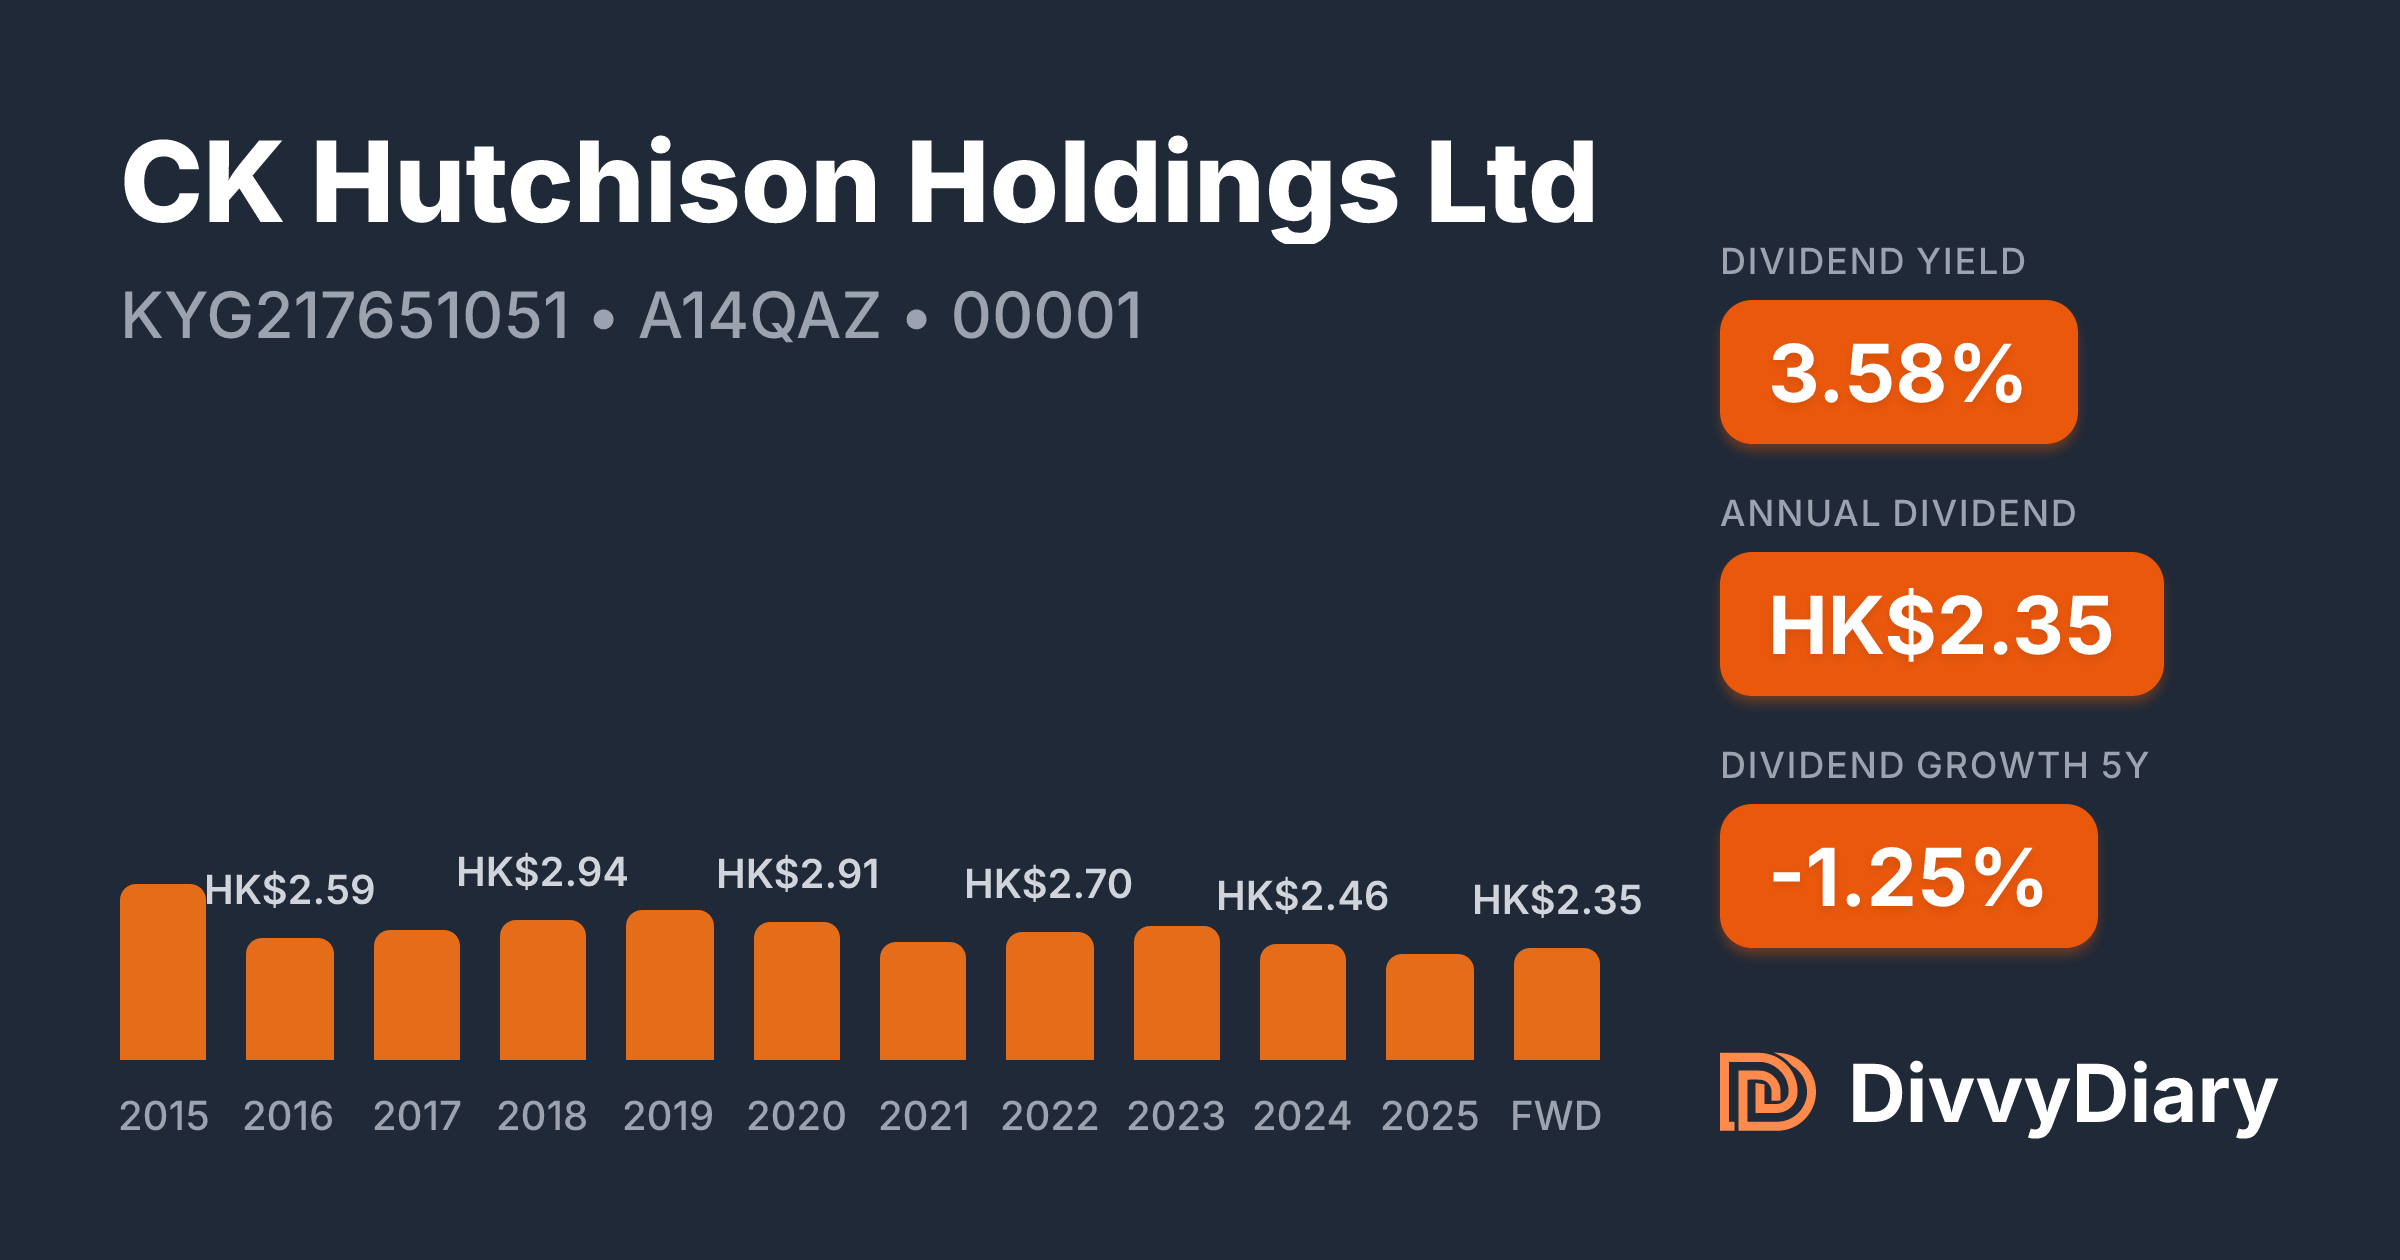
Here is the counter-intuitive part that most beginner investors get wrong. The stock tends to perform best when global trade volumes are under pressure but interest rates are falling. Ports benefit from lower financing costs on their debt, which is significant because CK Hutchison carries approximately HK$180 billion in total debt. When rates drop, the interest expense reduction flows directly to the bottom line. Meanwhile, the telecom division, especially Three UK, becomes more valuable because the discounted cash flow of its subscriber revenue increases. So paradoxically, a slowdown in global shipping doesn't hurt this stock as much as it should, because the financing cost benefit and the telecom revaluation offset the volume decline. The main pitfall is assuming the Li Ka-shing legacy provides any ongoing strategic advantage. The founder stepped back from day-to-day operations years ago, and the current management team, led by Victor Li, runs the company using standard corporate governance practices. There is no special family intervention that protects shareholders during downturns. The stock has dropped below HK$60 on multiple occasions when the market feared a broader recession, and the management did not intervene with buybacks or extraordinary measures during any of those periods. If you are looking at this stock for income, the dividend is reliable but not growing. Over the past decade, the annual dividend per share has moved from approximately HK$1.96 to HK$2.64, which is a compound annual growth rate of roughly 3%. That is barely above inflation. If you need real income growth, this is not the stock. If you want a stable yield with moderate downside protection due to the asset-backed nature of the business, it is one of the better options on the Hong Kong exchange.
Get the Full Details
There is also a structural risk that deserves more attention than it gets. CK Hutchison has significant exposure to mainland China through its port operations in Guangzhou, Shenzhen, and Xiamen. Any tightening of Sino-European trade relations would hit those terminals directly. I monitored this closely during the 2022 to 2023 period when there were rumors of reduced container throughput at Qingdao and Shanghai. The stock fell about 12% on those rumors, but the actual impact on quarterly earnings was less than 2%. The market overreacted because it could not distinguish between sentiment-driven selling and fundamentals-driven selling. This overreaction created a buying opportunity for anyone willing to wait three months for the earnings to confirm the minimal impact. A realistic workaround for analyzing this stock is to build a sum-of-the-parts model rather than relying on a single P/E ratio. Value the port segment at 8 to 10 times EV/EBITDA, the telecom segment at 5 to 7 times, and the infrastructure and retail segments at 10 to 12 times. Add the net debt and subtract a company discount of roughly 15%. What you will usually find is that the intrinsic value per share is somewhere between HK$75 and HK$95, depending on your assumptions. The market price often deviates from this range based on macro sentiment rather than company-specific performance. The only scenario where this analysis completely breaks down is during a liquidity crisis in Hong Kong equities. In March 2020, the Hang Seng Index fell roughly 30%, and CK Hutchison dropped from around HK$95 to HK$52 in six weeks. No amount of sum-of-the-parts valuation matters when everyone is selling regardless of fundamentals. I had to hold through that period without adding to my position because the selling pressure was indiscriminate. If you are new to this stock, avoid using leverage to buy during broad market stress. The dividend will keep paying, but the price may stay depressed longer than any model predicts.