Understanding Yield Premium Strategies In Modern Fixed Income
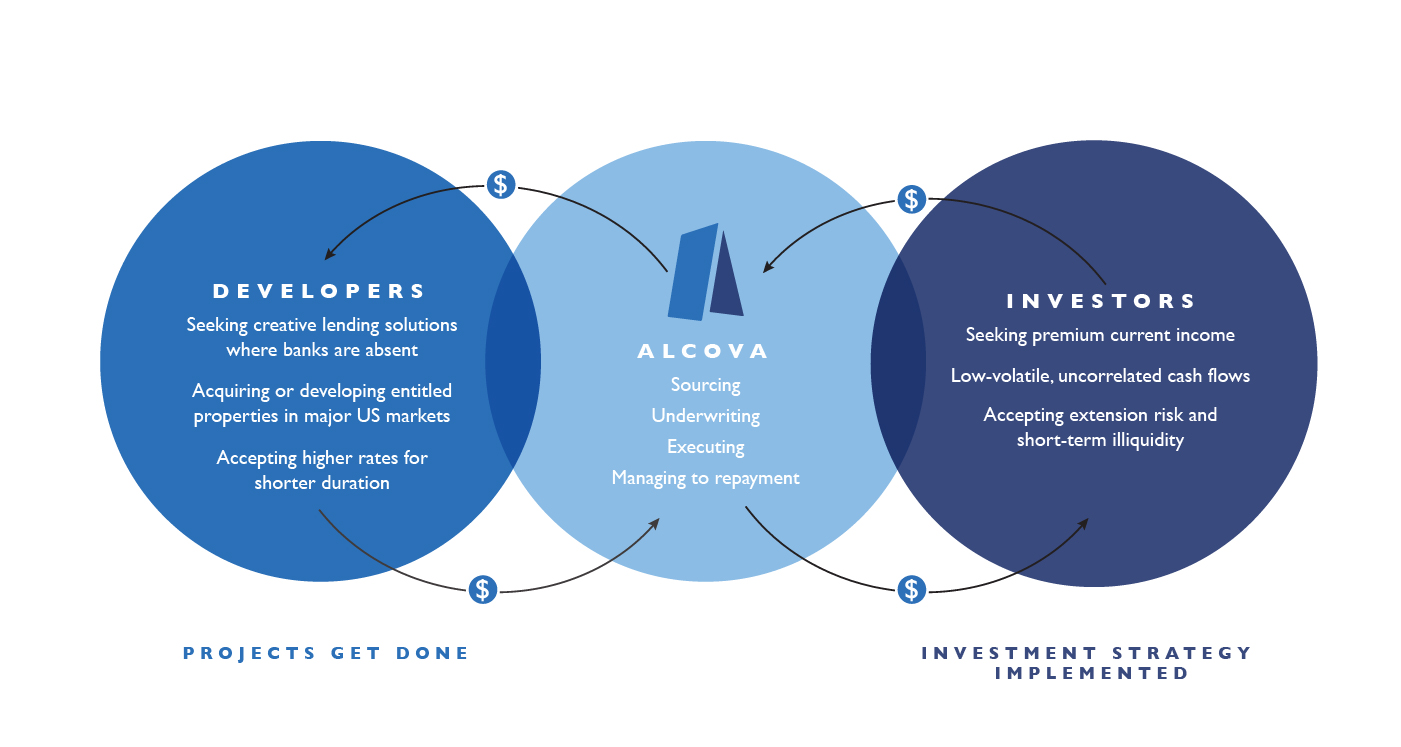
Investors looking for ways to boost income from their bond portfolios often run into the term yield premium, whether they are talking about a specific fund or just a general approach. Alcova Capital has positioned itself in the alternative fixed income space, and their Yield Premium Fund A is one of the products that comes up when people search for higher-yielding strategies. The basic idea is straightforward enough, but the mechanics behind how it actually delivers returns are where most people get confused. When you dig into what a yield premium fund like Alcova Capital Yield Premium Fund A actually does, you are looking at a strategy that targets bonds and other fixed income instruments trading below their intrinsic value or offering above-market coupon rates. This is not the same as buying high-yield junk bonds, which is a common misconception. The yield premium approach focuses on mispriced credit, capital structure arbitrage, and situations where liquidity premiums create attractive entry points. Alcova, like many firms in this space, tends to emphasize private credit and structured products rather than public high-yield. I spent some time analyzing how these funds operate after working with a client who had allocated significant capital to a yield premium strategy and was surprised by the distribution patterns. The monthly or quarterly payouts looked reasonable on paper, but the underlying asset valuation was lagging, which meant the fund was returning more of your own money than generating actual income. That is a real risk with many yield-focused alternatives, and it is something I wish more investors understood before committing. The workaround in that case was shifting to a more transparent fee structure and demanding weekly NAV reporting, which eventually revealed the true performance.
How Yield Premium Funds Actually Work
The core mechanism involves identifying credit instruments that offer yield above comparable public benchmarks. This could mean direct lending to middle-market companies, purchasing distressed debt at a discount, or taking positions in covenant-lite structures that others avoid. Alcova Capital's approach, based on public information, emphasizes direct origination and a hold-to-maturity mindset rather than trading through positions for capital gains. That changes the risk profile significantly compared to a traditional bond fund. One counter-intuitive insight here is that yield premium strategies often underperform in normal market conditions. When credit spreads compress and everything looks fine, the extra yield evaporates because the opportunities become less attractive. The real alpha comes during stress periods when liquidity dries up and mispricings emerge. This means investors need to be comfortable with periods of flat or negative returns while waiting for the opportunities to materialize. Most people do not realize this when they are drawn in by the headline yield number. Another nuance involves the compounding effect of reinvested distributions. Many yield premium funds distribute income that includes a return of capital component, especially in the early years. If you automatically reinvest without checking the breakdown, you might think you are growing your position when you are actually just cycling your own money back in. I learned this the hard way reviewing a portfolio where the reported return was five percent but the actual economic return was closer to two percent once you stripped out the return of capital. Always ask for the distribution composition, not just the yield percentage.
Risks And Limitations To Consider
Yield premium strategies come with real drawbacks that are often minimized in marketing materials. Liquidity is the first issue. Alcova Capital Yield Premium Fund A, like most private credit funds, likely has lock-up periods or redemption gates that limit your ability to exit. I have seen situations where investors needed access to their capital during a personal emergency and were unable to withdraw for months due to suspension clauses. This is not a hypothetical risk, and it is one of the most important factors to evaluate before committing. Credit risk is another concern that deserves more attention. These funds are not avoiding risk by chasing yield, they are taking on different types of risk. Default rates in private credit can be lower than public high-yield on paper, but that is partly because valuations are set by the manager rather than by market trades. When stress hits, the reported net asset value may not reflect the true liquidation value. During the 2020 downturn, several private credit funds had to write down positions significantly, but the timing of those writes was delayed compared to publicly traded bonds. By the time the losses appeared in NAV reports, the damage was already done. Fee structures in this space are also worth scrutinizing. Management fees alone might look reasonable at two percent, but performance fees, spread fees, and transaction costs can eat into returns substantially. A fund advertising a seven percent yield might actually deliver four or five percent after all fees, depending on how the fee calculation works. I recommend modeling the worst-case scenario where the fund barely exceeds its hurdle rate, because that is often what you get in practice.
Get the Full Details
What To Look For Before Investing
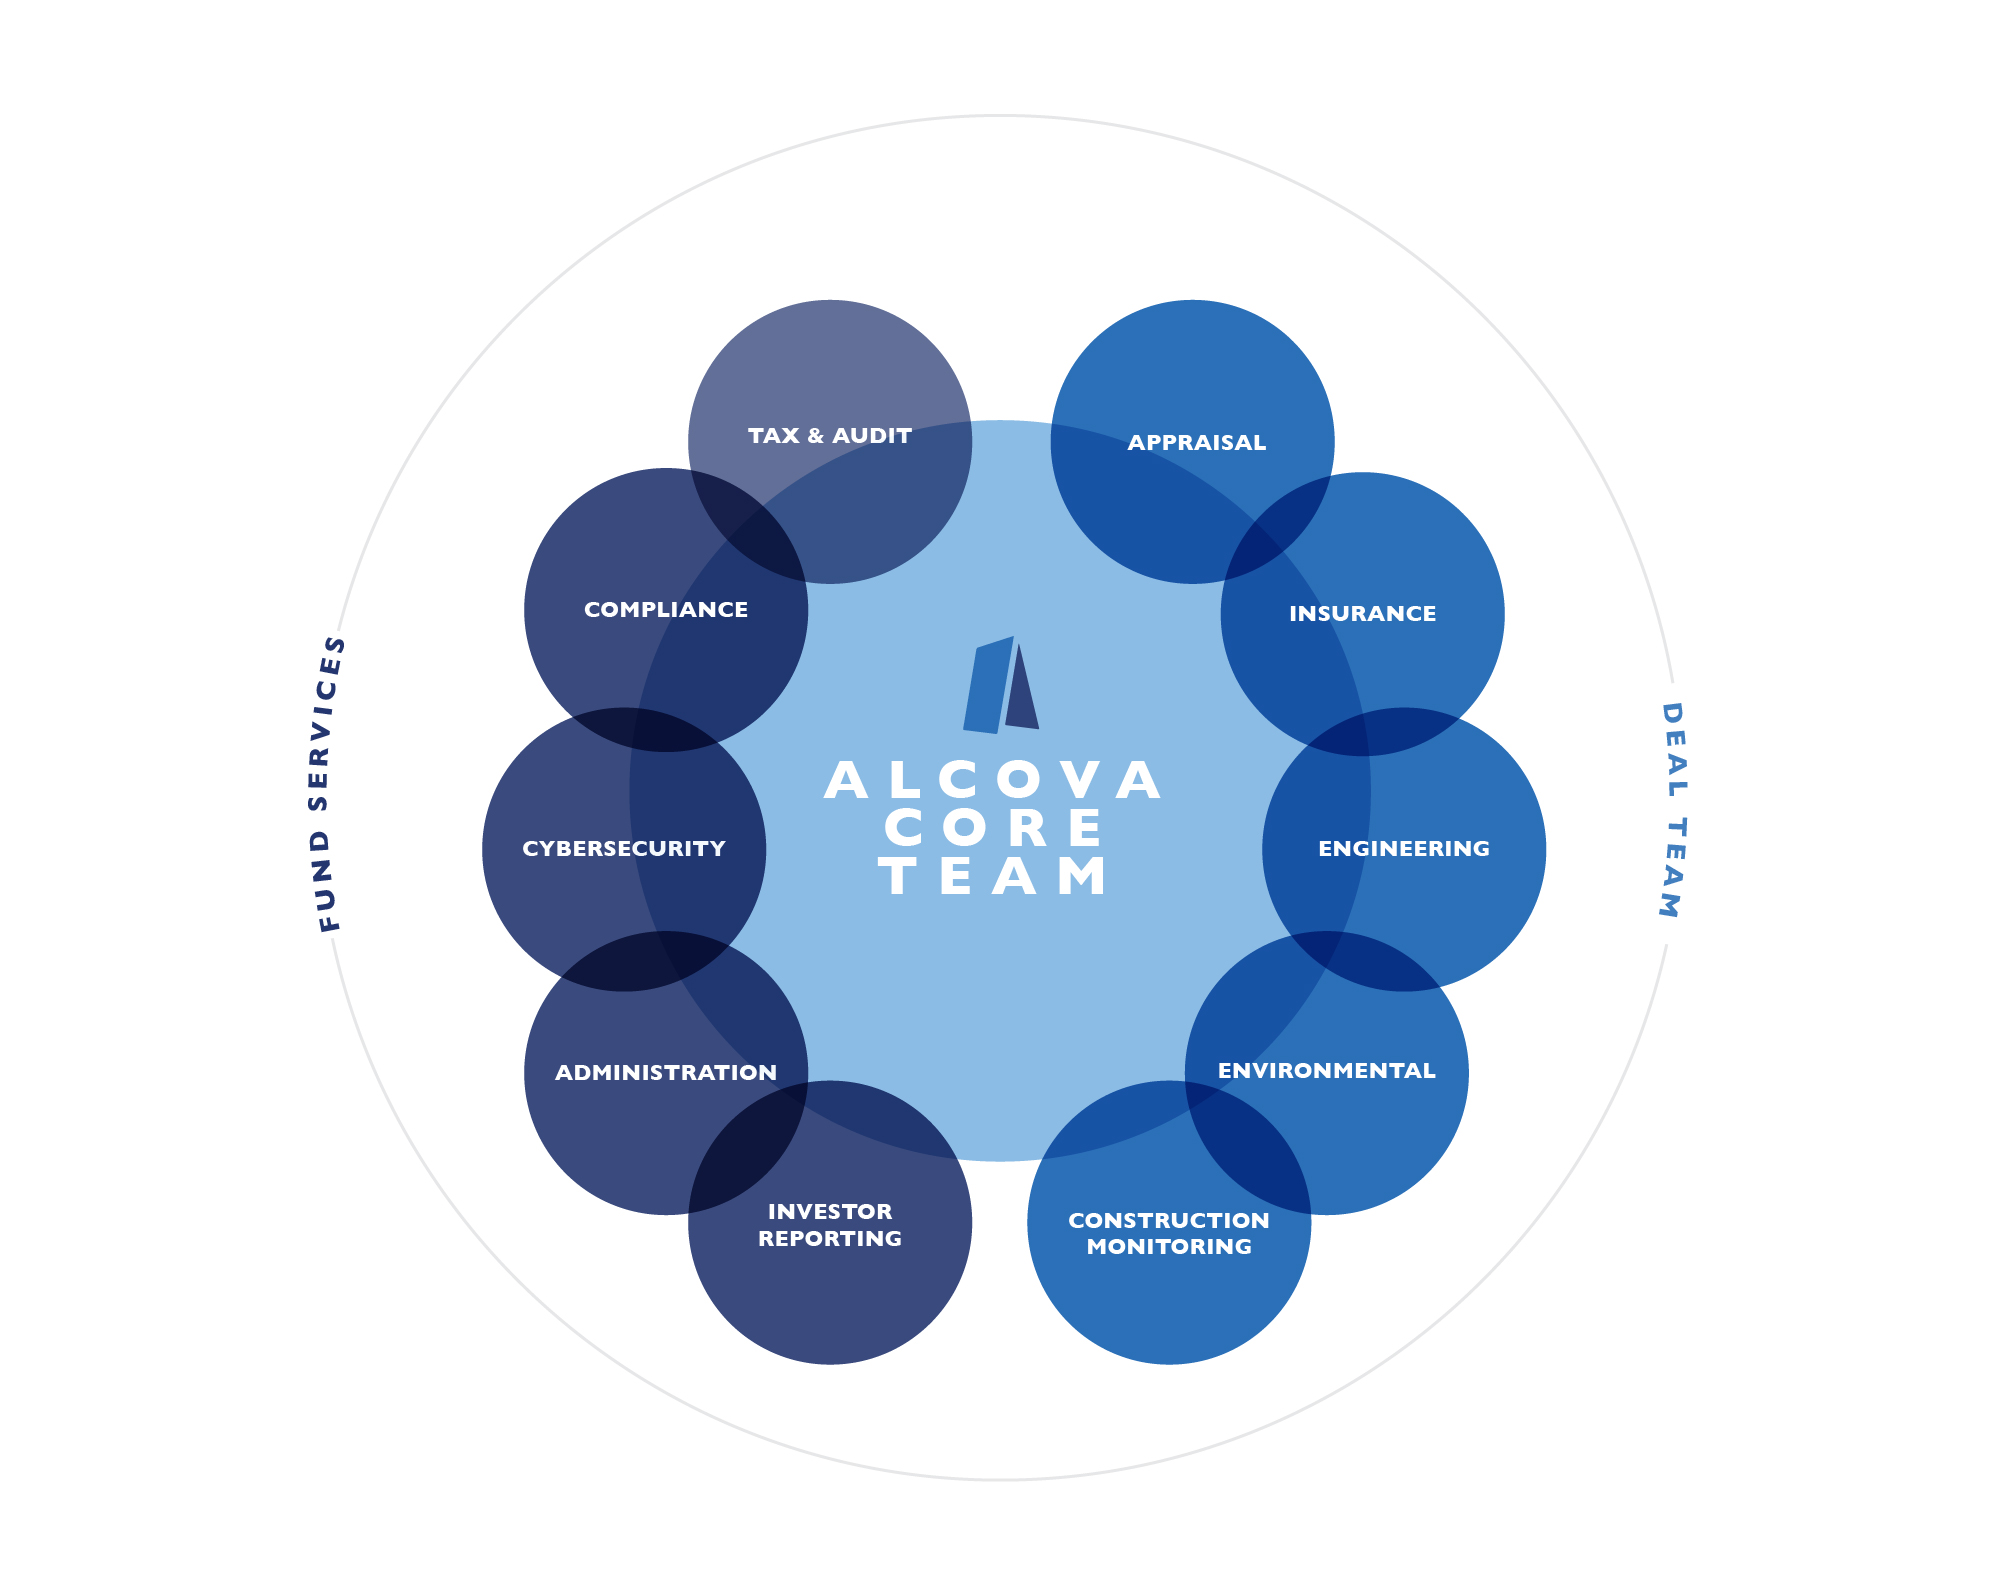
If you are considering a yield premium fund like Alcova Capital Yield Premium Fund A, the due diligence process should focus on a few key areas. First, understand the underlying portfolio composition. You should know what sectors, geographies, and credit ratings are represented. Vague descriptions like diversified credit opportunities do not cut it. Request a detailed portfolio report, even if it is quarterly, because the aggregation level tells you whether there is hidden concentration risk. Second, examine the fund's track record through different market cycles. A strategy that only has performance during calm periods is not demonstrating skill, it is demonstrating that it avoided risk. Look for how the fund behaved during stress events, how quickly positions were written down, and whether distributions were maintained or suspended. The best funds in this space show resilience, not just high yields. Third, verify the custody and valuation independence. Some private credit funds use the same entity to manage and value assets, which creates a conflict of interest. Independent valuation firms reduce this risk, but they are not foolproof. I once reviewed a fund where the independent valuer relied entirely on manager-provided cash flow projections, which defeated the purpose of having an independent party. Make sure the valuation process is transparent and auditable.
Alternatives To Consider
Yield premium funds are not the only way to enhance fixed income returns. Publicly traded BDCs, closed-end funds, and treasury STRIPS can provide yield exposure with more transparency and liquidity. For investors who want simplicity, a laddered portfolio of investment-grade municipal bonds or corporate bonds can deliver stable income without the complexity of private credit. The trade-off is lower yield, but the risk-adjusted returns are often better once you factor in liquidity premiums and fee drag. If you are set on pursuing a yield premium strategy, Alcova Capital is one of several firms operating in this space. The key is to treat it as part of a broader allocation rather than a core holding. Five to ten percent of a fixed income portfolio is a common range for private credit exposure, depending on your overall risk tolerance and liquidity needs. Going heavier than that without full transparency into the underlying positions is where most mistakes happen. I have watched investors lose confidence in these strategies not because the returns were bad, but because the lack of visibility made them nervous during volatile periods. Knowing what you own, even imperfectly, is always better than not knowing at all.


