Getting Started With Your First Premier Credit Card
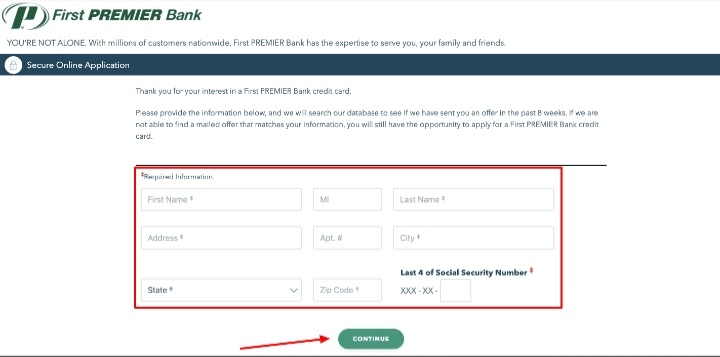
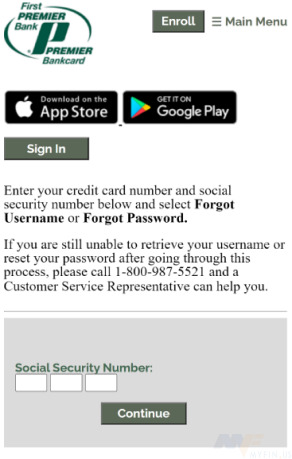
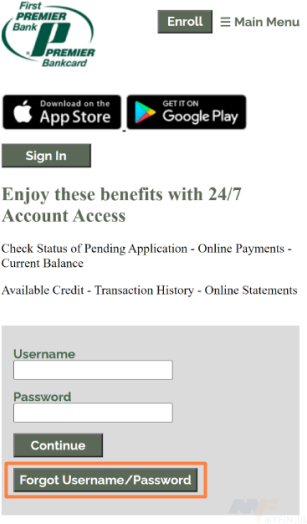
Premier credit cards from major banks like Chase, Citi, or Bank of America sit somewhere between standard rewards cards and the ultra-exclusive Black or Platinum tiers. They typically offer elevated cashback rates, travel insurance, and occasionally lounge access that basic cards don't provide. The main issue I see people run into isn't the card itself it's the account access setup. Most first-time holders spend more time trying to log in than actually using the card. Here's how the actual process works. When your card arrives, you'll get a welcome packet with an activation number and a link to the bank's registration portal. You need your Social Security number, your new card number, and usually a checking or savings account already linked for autopay. The online setup takes about 10 to 15 minutes if your information is straight. Mobile app registration is faster, sometimes under 5 minutes, but the web portal gives you more control over security settings and notifications. One thing banks don't make obvious: you often cannot set up autopay through the mobile app on your first login. The system requires you to establish the autopay arrangement through the full website dashboard first. I learned this the hard way after trying to skip the web step and hitting a dead end that cost me three phone calls and about 40 minutes on hold. Set up autopay through the website before you bother with the app.
Security settings matter more here than they do on basic cards. Premier cards usually trigger fraud alerts on unusual activity more aggressively because the issuing bank knows the card has higher limits and travel perks attached. I'd recommend turning on transaction alerts for anything over $50, enabling travel notifications if you plan to use the card internationally, and setting up your preferred contact method for verification calls. The automated verification calls are real they'll call your registered number to confirm large purchases or international transactions in some cases. Make sure your phone number on file is current, or you'll miss these and your card gets declined at the worst possible moment. The credit limit on these cards typically ranges from $5,000 to $25,000 depending on your credit profile at approval. Don't expect automatic increases quickly. My own card took 14 months before I saw a limit bump, and that was after I'd been paying the full balance every month without a single late payment. Some banks do monthly auto-review programs but they're not guaranteed and the criteria vary by issuer. If you want faster limit growth, request a review after 6 to 8 months of clean usage rather than waiting for the system to catch up on its own schedule. Another thing that catches people off guard: premier cards often come with companion benefits that require separate registration. Travel insurance, purchase protection, extended warranty these features usually exist in the cardmember agreement but activating them for specific trips or purchases sometimes requires a separate online form or a phone call to the benefits line. I found this out when a rental car claim got denied because I never filed the activation paperwork for the collision damage waiver before the trip. The coverage was there, I just didn't turn the key.
If you're traveling, call your card issuer 48 hours before you leave the country. Not because your card will be blocked automaticly it's because some banks still flag international transactions as suspicious even on premier tier accounts. A quick phone call or a logged travel notice through the website takes two minutes and prevents a declined card at a foreign restaurant or hotel. There's also the question of foreign transaction fees. Many premier cards now waive these entirely but not all. Check your cardholder agreement before you fly overseas assuming it's waived and getting hit with a 3% fee on every purchase adds up fast. Customer service access is better on premier cards than on entry-level ones. You usually get a dedicated phone line that bypasses the general IVR maze. The number is typically printed on the back of your card and sometimes labeled as Premier or Priority customer service. Wait times during peak hours can still be 20 to 30 minutes but it's significantly better than the general queue where people wait an hour or more. Keep your account number handy when you call and have any specific transaction details ready. Representatives move faster when you give them the exact merchant name, date, and amount rather than asking them to look it up after you explain the problem. The annual fee on premier cards usually runs between $95 and $250. Whether it's worth it depends on how you use the card. If you're earning 2% cashback on everything and getting the travel benefits without touching them, you're essentially paying for nothing. But if you use the card for travel bookings, dining, and everyday purchases while paying the balance in full each month, the rewards and protections usually offset the fee within the first six months. Calculate your expected annual spend multiplied by the rewards rate, then subtract the annual fee. If the number is positive and comfortable, the card makes financial sense.
Get the Full Details

One final practical note: set up digital wallet integration immediately. Apple Pay, Google Pay, and Samsung Pay all work with premier cards and they're faster than chip insertion at most point-of-sale terminals. More importantly, they add a layer of tokenization that makes your actual card number invisible to merchants. This reduces your exposure to skimming and data breaches at the register. I've seen people lose years dealing with fraudulent charges because they only used physical cards at poorly secured terminals. Digital wallets are a simple fix that most people overlook. The biggest mistake first-time premier cardholders make is treating the card like a status symbol rather than a financial tool. The card itself doesn't build your credit score. How you manage it does. Pay on time, keep utilization below 30%, and avoid carrying a balance. Those three habits matter more than any perk or tier label attached to the account.