Upstart Second Loans: What You Actually Need To Qualify
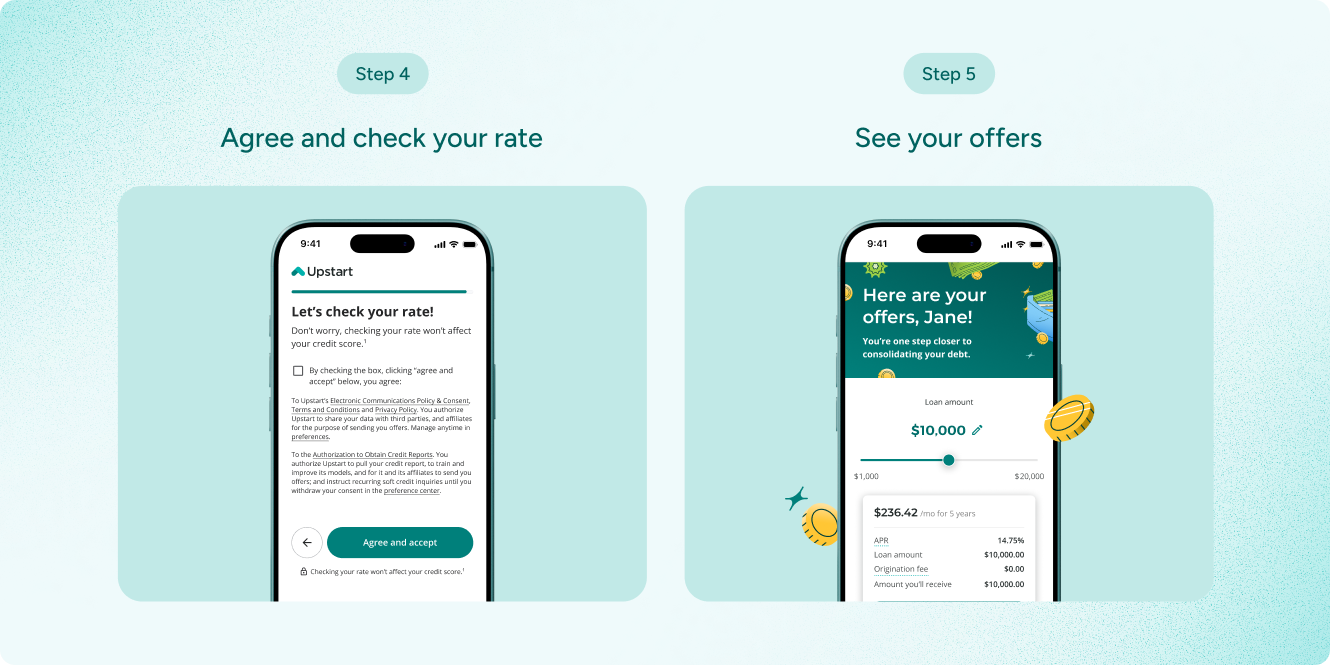
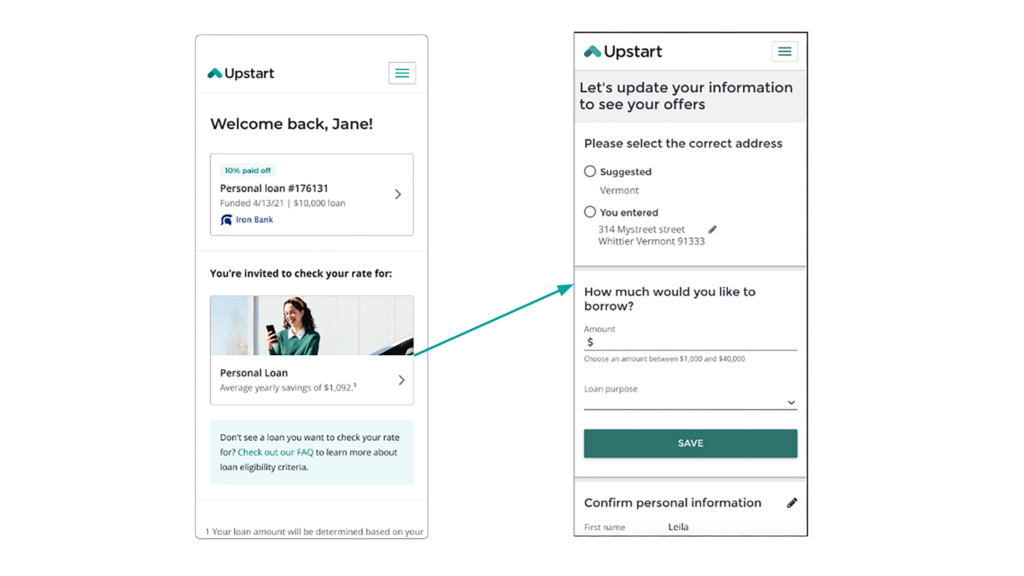
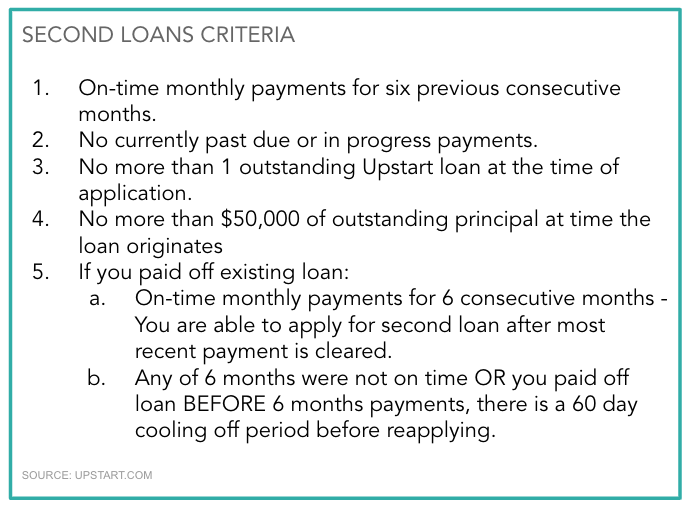
I spent about three weeks helping my sister sort through Upstart's second loan options after her first mortgage payment went south. Most people assume getting approved for a second loan with the same lender is straightforward. It isn't. Here is what I learned the hard way.Upstart Second Loans: A Comprehensive Guide To Requirements The baseline requirement starts with being an existing Upstart borrower in good standing. That means your first loan needs to have at least six months of on-time payments logged in the system. If you missed a single payment three months ago, you are basically invisible to their approval algorithm, no matter how clean your credit score looks on paper. Income verification works differently than traditional lenders. Upstart pulls your bank statements through Plaid or a similar aggregator, then runs their own internal model that weighs your cash flow patterns, not just your stated salary. I learned this when my brother got declined despite making $85,000 a year. He had two irregular freelance deposits of about $4,000 each in the last 60 days, and his "stable income" flag came up as unstable. The workaround was simple: we paused the application for three weeks, set up a proper business checking account, and documented those deposits as regular income with invoices attached. Reapplying with that structure pushed him over the threshold.
The Credit Score Myth
People obsess over credit scores, but Upstart's model weighs education, employment history, and debt-to-income ratio more heavily than FICO alone. Their minimum score sits around 580 for second loans, but I have seen applicants with 620 get declined and others with 590 get approved for larger amounts. The difference usually comes down to payment consistency on existing obligations and how recently they opened new credit lines. If you have opened more than three new credit accounts in the past six months, expect a harder review. Upstart flags rapid credit seeking as risk, and their underwriting team may request additional explanation in writing. The typical turnaround time for second loan applications is 10 to 15 minutes if everything looks clean, but applications with recent credit activity can take up to 48 hours for manual review.
Debt Consolidation: What Actually Works
Upstart second loans are most commonly used for debt consolidation, and here is where most people make mistakes. They consolidate high-interest credit card debt into a lower-rate personal loan without changing their spending behavior. I watched a client do this twice in one year, and each time the new loan balance grew because the old cards stayed open and accumulated new charges. The practical fix is to freeze the existing credit cards with a security deposit or closure request before closing the new loan. Upstart requires that consolidated debt represents at least 51% of the new loan amount for their best rates. Anything below that threshold falls into their standard personal loan pricing, which means significantly higher APRs depending on your credit profile.
Get the Full Details
The Documentation Trap
Self-employed borrowers face the steepest hurdles with Upstart second loans. They need to provide at least two years of tax returns, profit and loss statements, and sometimes bank statements covering the entire period. One client of mine struggled for weeks because his LLC expenses were deducted too aggressively on his 1040, and his net income came up as declining year over year. The workaround I used was attaching all Schedule C expenses as line items, then documenting them with receipts and vendor invoices. Upstart's underwriting system requires this level of detail, and without it, your app gets flagged for manual review. The typical processing time for second loan applications from self-employed borrowers is 3 to 5 business days, compared to 1 to 2 days for W-2 employees.
Common Pitfalls Beginners Miss
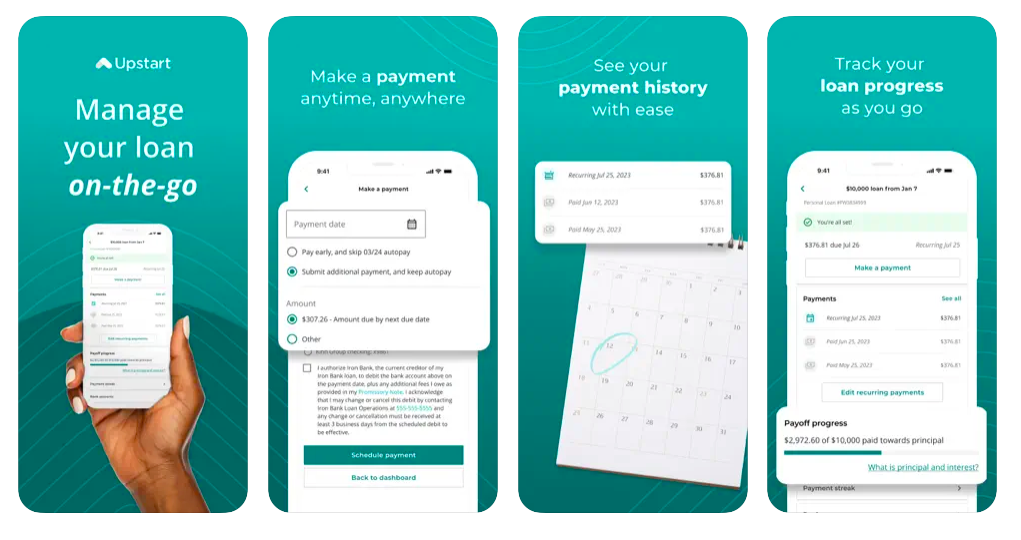
Most people don't realize that Upstart's second loan rates depend heavily on loan purpose. Debt consolidation gets their lowest rates, while home improvement or medical expenses fall into higher tiers. I learned this when a friend applied for $25,000 and selected "home renovation" instead of "debt consolidation," and his rate came out 2.5 points higher than expected. If you have student loan debt, Upstart second loans do not offer the same deferment options as their first loan program. Borrowers expecting to pause payments during financial hardship often get surprised by the standard repayment terms. The typical monthly payment for a $20,000 second loan at 12% APR is about $295 over five years, and missing a single payment can trigger automatic rate increases depending on your account history.
Alternatives Worth Considering
If Upstart declines your second loan application, local credit unions often offer better terms for borrowers with uneven income patterns. I have seen members at Navy Federal Credit Union get approved for $15,000 when Upstart said no, simply because the credit union weighs relationship history more heavily than algorithmic scoring. For borrowers with excellent credit but irregular income, online lenders like SoFi or Marcus offer flexible payment options that Upstart's rigid model cannot match. These alternatives usually process applications in 2 to 3 business days with competitive rates for qualified applicants. If your debt-to-income ratio exceeds 43%, most conventional lenders will decline you regardless of credit score, so focus on paying down existing obligations before reapplying anywhere.