What Triple A Asset Allocation Actually Means In Practice
The AAA framework isn't some new invention. It's a simplified version of strategic asset allocation that broke into retail investment circles around 2019 and got wrapped in enough marketing language to make competent planners roll their eyes. Here's the clean version. The three A's stand for Allocate, Adjust, and Assess. That's it. The rest is ceremony. Allocate means deciding what percentage of your portfolio sits in each asset class before you buy anything. Not after. Not when you feel like it. Before. Most people skip this step and just pick funds they like the names of. That's not a strategy. Adjust is the rebalancing part. When stocks run up and bonds lag, your allocation drifts. You sell the winner, buy the loser, get back to your original targets. This forces the mechanical discipline that emotional investors consistently avoid.
Assess is where most frameworks fall apart. It's the review process where you look at whether your assumptions are still holding. Are your return expectations realistic? Has your time horizon shifted? Did life events change your risk tolerance? This step usually gets compressed into a single annual meeting or ignored entirely. Both choices produce predictable bad outcomes.
Unlocking The Power Of Triple A The Ultimate Guide To Exceptional Asset Allocation
I want to get specific about what this looks like for someone actually building a portfolio instead of reading about it. Start with your time horizon. If you're under ten years out, you're not doing growth allocation. Period. A 70/30 stock-to-bond split doesn't become appropriate just because you're comfortable with volatility. You can handle watching your account drop thirty percent and still sleep at night. That doesn't mean your money needs to be in stocks when you'll need it in four years. I've watched too many people conflate risk tolerance with investment timeline and lose real money because of it. For the Allocate step, pick your core asset classes and assign percentages that add to exactly one hundred. Don't overcomplicate it. Domestic equities, international equities, domestic bonds, international bonds, and a small alternative allocation if you understand what alternatives actually do. I see a lot of people add commodities, REITs, and private equity to a basic portfolio without having read a single prospectus on how those assets behave during stress periods. That's not diversification. That's clutter.
Get the Full Details

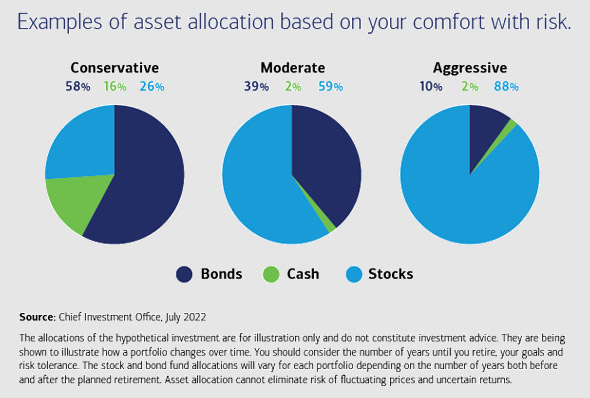
Here's a working example. Someone aged thirty-five with a twenty-year horizon might allocate 60% domestic equities, 20% international equities, 15% domestic bonds, 3% international bonds, and 2% alternatives. A person at sixty with five years until retirement should be looking at something closer to 35% equities, 15% international equities, 40% bonds, and 10% short-term instruments. The difference isn't subtle. The difference is whether you're playing offense or defense. For the Adjust step, I use a band-based rebalancing approach rather than a purely calendar-based one. If any allocation category drifts more than five percentage points from its target, I rebalance. A 60% equity position that has moved to 67% gets trimmed. This typically catches imbalances faster than annual reviews without triggering unnecessary trades during normal market noise. Calendar-only rebalancing on a yearly basis left me with materially drifted portfolios three years running before I switched methods. The tax drag from unnecessary trades in taxable accounts was significant. The Assess step is where I have a specific edge case that might matter to you. Two years ago I was reviewing a client's portfolio that looked perfectly allocated on paper. Sixty percent stocks, forty percent bonds. But the equity portion was heavily concentrated in a handful of sector ETFs that had similar underlying holdings. When tech sold off in a particular quarter, the entire stock allocation dropped nearly twenty-two percent in a single month. The bond allocation barely moved because rates were stable. The client's risk was nowhere near what the allocation percentages suggested. I fixed it by auditing the actual security-level exposure across all holdings and redefining the equity allocation based on correlation-adjusted risk rather than headline percentages. That portfolio would have looked fine to anyone who only looked at the top line numbers.
This is the kind of thing that standard AAA guidance doesn't always address clearly. Your allocation can be mathematically correct and practically wrong if the underlying assets aren't behaving independently. Factor overlap is the technical term for this. You can own twelve different fund ticker symbols and still be heavily exposed to a single risk factor. Checking the prospectus of each fund for its factor exposures takes about twenty minutes per fund and will save you from some uncomfortable conversations later. There's a reasonable alternative worth considering if you don't want to manage this yourself. Target-date funds automate the allocation, adjust, and assess components by embedding them in the fund's glide path. You pick a date and the fund manager handles the rest. The downside is that you surrender control and pay higher expense ratios for that convenience. A well-constructed DIY AAA portfolio using low-cost index funds can run at under fifteen basis points total expense. Target-date funds from major providers typically sit between fifty and eighty basis points. Over a thirty-year period, that difference compounds into a material amount of money you keep or lose. The framework has real limitations. It assumes markets are reasonably efficient, which they aren't always. It assumes your risk tolerance is stable, which it rarely is. It assumes you'll actually follow through on rebalancing when it's emotionally uncomfortable to sell what's going up, which most people won't. The framework itself is sound. Execution is where people fail. I've seen clients stick to their allocation through mild drawdowns and then abandon it entirely during a single sharp correction. The plan didn't break. Their discipline did.
If you're starting from zero, the practical path is this: define your time horizon, choose a simple multi-asset allocation that matches it, pick low-cost index funds for each bucket, set up automatic rebalancing triggers, and review the actual risk exposures annually rather than just the headline percentages. The entire setup process for a basic three-fund portfolio takes about forty-five minutes. The ongoing maintenance, if you use band-based rebalancing with automated alerts, runs at roughly fifteen minutes per quarter. The harder part isn't the mechanics. It's making the rebalancing trade when your best-performing asset class is up forty percent year to date and every instinct tells you to let it run. The framework tells you to sell some of it anyway. That's the whole point. The power isn't in the allocation. It's in the discipline to maintain it when doing so feels completely wrong.