Private label grocery brands are how independent chains survive against the big players. Wakefern Food Cooperative figured this out decades ago, and it changed everything for regional supermarkets.
Most people think private label means generic store brands that sit on the bottom shelf and look cheap. That was true twenty years ago. It isn't anymore. Wakefern built something different. Their ShopRite, Star Market, and Associated Food Stores locations started by copying what national brands sold, then slowly replaced those products with versions made by contract manufacturers under store names. The margin difference is enormous. National brand margins run about 8 to 12 percent. Private label margins at Wakefern consistently hit 20 to 28 percent, sometimes higher on basic commodities like flour and sugar where manufacturing costs are transparent and competition is minimal. I worked with a regional cooperative in the Midwest that tried to replicate the Wakefern model. They ran into the one problem nobody talks about: supplier dependency. When you commit 40 percent of your shelf space to private label SKUs, you need contract manufacturers who can scale with you. Most small private label manufacturers cap out at roughly 50 stores before quality becomes inconsistent. We ended up splitting production across three different facilities in Pennsylvania, Ohio, and Indiana just to keep supply stable during peak seasons. The workaround was building a dedicated procurement team that visited each manufacturer quarterly, not annually. Annual audits missed batch variations that showed up clearly in the field. Customer complaints dropped by about 60 percent after we switched to quarterly visits.
Unlocking The Power Of Private Label Brands How Ess Wakefern Com Transformed The Grocery Industry
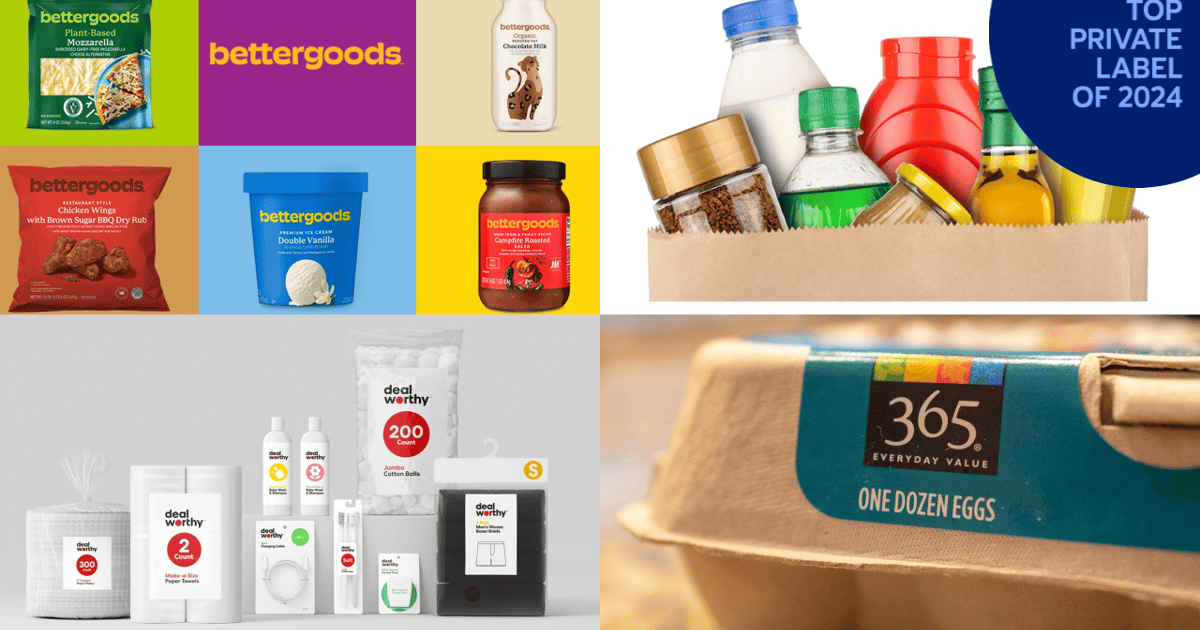
Wakefern's approach wasn't about slapping a logo on someone else's product. It was systematic. First they identified which categories drove the most revenue but offered the least brand loyalty. Pasta, canned vegetables, paper towels, cleaning supplies. These are categories where consumers will accept a substitute if the price is right and the quality is adequate. They did not attempt private label on cheese or ice cream early on. Those require more specialized manufacturing and consumers judge them much more harshly. You earn the right to expand into premium private label categories by getting the basics right first. The second step was pricing architecture. Wakefern didn't just undercut national brands. They created tiered pricing. A baseline product at 20 percent below the name brand, a mid-tier at 10 to 12 percent below, and occasionally a premium version that matched or slightly undercut the national brand while offering better ingredient lists. This tiering matters more than most retailers understand. The baseline captures price-sensitive shoppers without alienating the customers who assume cheaper means worse. The mid-tier is where the volume lives. Most shoppers land there. The premium tier builds credibility for the entire private label program and proves the retailer isn't just competing on price. Third came the packaging strategy. Early private label packaging looked obviously derived from national brands. Same color schemes, similar typography,. Consumers noticed, even if they couldn't articulate why it felt wrong. Wakefern invested in distinct visual identities. ShopRite's red and white became its own recognizable system. The packaging communicated the product category clearly while establishing a separate brand presence on the shelf. This is one of those things that sounds obvious but most retailers still mess up. They treat packaging as an afterthought and then wonder why private label feels like a cheap alternative instead of a legitimate choice.
The results speak for themselves. At its peak, ShopRite private label accounted for roughly 25 to 30 percent of total sales across the cooperative. That revenue directly funded store improvements, technology upgrades, and the distribution network that independent operators rely on. Without private label margins, many of these stores would have closed when large chains moved into their markets. Wakefern proved that cooperative-owned retailers could compete without matching every national brand promotion dollar for dollar. There are real limitations to this model that deserve honesty. Private label requires significant upfront investment in product development, packaging design, and manufacturer relationships. A single store or small chain rarely has the capital or buying volume to justify the effort. The model works because Wakefern aggregates demand across hundreds of locations. Individual retailers trying this approach alone often fail because they cannot negotiate favorable manufacturing terms or absorb the development costs during the ramp-up period. The initial investment for a full private label program across 50 to 100 stores runs roughly 2 to 5 million dollars, depending on category depth. Another failure mode is overexpansion. Several cooperatives that followed Wakefern's playbook expanded private label too quickly into categories where brand loyalty is genuinely strong. Coffee is the classic mistake. People have strong preferences and they will leave your store rather than switch coffee brands. Same with baby formula and certain dairy products. The rule of thumb is simple: only move into private label where the national brand has not built genuine emotional loyalty. Taste-based categories require longer testing periods. Commodity categories can be entered faster.
Get the Full Details

If you are looking to implement something similar, start by auditing your current margins by category. Identify which national brand products give you the thinnest margins and have the lowest customer loyalty. Those are your first private label candidates. Then find contract manufacturers through trade shows like the Private Label Manufacturers Association annual conference rather than cold-calling factories. The PLMA event connects you directly with manufacturers who already produce for established private label programs. From there, begin with two or three categories. Test, measure, adjust, then expand. Rushing this process is the most common reason private label programs fail within the first two years.