What CCpayment Actually Is
CCpayment stands for cross-border cryptocurrency payment infrastructure. It uses stablecoins and sometimes private blockchain networks to move money between countries faster and cheaper than traditional correspondent banking. You don't need a SWIFT MT103, a foreign exchange hedge desk, or seven working days for settlement. Most transactions clear in under ten minutes, usually for less than thirty cents per transfer on the network side. The model has been around since roughly 2020 in earnest, but most people trying to use it today still treat it like a novelty. That's why it's not yet the default path for mid-market trade finance. You can build or buy access to it. The access part is where things get fiddly.
Unlocking The Power Of Ccpayment Revolutionizing Crossborder Transactions
If you want to actually deploy this, you aren't just signing up for a dashboard. You need a stack that covers three areas: fiat on-ramps and off-ramps, a stablecoin settlement path, and a compliance layer that can explain the movement of funds to banks and regulators. Here is the practical breakdown. You have two main paths. Path one is using a licensed payments provider that already bridges fiat and stablecoins. Examples include providers like Stripe Crypto, Circle for Business, or specialized cross-border fintechs such as Azimo, Wise's newer crypto corridors, or region-specific players like Ge idea (Panasonic's cross-border arm). This is the fast track. Your compliance burden is lighter because the provider takes custody of the licensing risk. Path two is building your own bridge. You open a corporate stablecoin treasury, connect to regulated on-ramp exchanges, integrate an API that issues stablecoin payments on a chosen network, and build your own reconciliation engine. This costs real engineering time and real legal counsel fees. It is cheaper at scale but painful until you hit meaningful volume.
For most mid-market companies, Path one is the rational starting point. Start with USD-pegged stablecoins like USDC. Start with a network like Solana, Polygon, or Ethereum Layer 2s where gas fees are low. Arbitrum and Base are reasonable choices today. Avoid mainnet Ethereum for high-volume small transfers. The fee drag kills the economics quickly.
Get the Full Details

The Compliance Reality
This is where people hit walls. Regulators do not care that your transaction settled in six minutes. They care about whether you can trace it. You need AML screening at both ends of the corridor, transaction monitoring, and a clear record of who initiated the payment, who received it, and what the underlying commercial purpose was. The exact mechanisms vary by jurisdiction. In the EU, MiCA provides a framework for stablecoin issuers, but your obligation as a payer or payee depends on national transposition. In the United States, FinCEN guidance and state-money transmitter licenses may apply. If you touch euro stablecoins, you may fall under SBT requirements. If you touch dollar-pegged tokens issued by a US entity, you are in a different regulatory neighborhood. Do not assume one setup covers all corridors. I learned this the hard way on a live migration. A client was routing invoices from a German importer to a supplier in Nigeria through USDC on Polygon. Everything looked clean. Then a downstream bank flagged a payment because the stablecoin wallet on the receiving end had interacted with a mixer-linked address two months prior. The funds were technically clean, but the wallet history triggered an automated AML alert. Settlement held, but the invoice was blocked for review for eleven days and the supplier waited twenty-three days total before the funds released into their local bank account. The workaround was simple but expensive. We moved the Nigerian supplier to a dedicated wallet that never touched mixer-adjacent addresses, implemented a pre-clearance check using a tool like TRM Labs, and accepted a 0.2 percent cost increase for the screening integration. That cut subsequent blocks to zero over the next fourteen months.
Cost and Speed Expectations
Under normal conditions, sending USDC from a European corporate account to an Asian supplier via a regulated bridge can take five to fifteen minutes. The all-in cost including conversion spreads, network fees, and compliance screening is typically between 0.3 percent and 1.2 percent of the transfer amount. Compare that to traditional wire corridors, which often land at 1.5 percent to 4.0 percent and take one to five business days depending on currency pair and intermediary banks. The savings are real on high-frequency corridors. They shrink on large single payments where fixed compliance overhead dominates. A fifty thousand dollar wire through CCpayment might cost you roughly one hundred fifty dollars all in. A traditional correspondent chain could charge two hundred fifty to four hundred dollars including forex spread, but would take longer. A half-million dollar transfer changes the math because the percentage friction of compliance on-ramps becomes more significant relative to the base.
Edge Cases and Pitfalls
Stablecoin de-pegging risk is the headline danger, but it is rarely the problem in practice for regulated issuers. The more common issue is liquidity fragmentation. Some corridors have deep order books for USDC and USDT. Others do not. If you need to convert to NGN, KES, or BRL on the fly, you may face slippage of one to three percent depending on market depth and the time of day. Always pre-fund your corridors during active business hours in the destination time zone. Another pitfall is double-spend fear. It is almost theoretical on modern networks, but internal teams often refuse to mark an invoice as paid until they see a second confirmation or until the receiving wallet broadcasts to a monitored node. Build your ERP or accounting integration to accept first-confirmation status with a small reserve buffer, and reconcile on settlement rather than waiting for twelve confirmations. Waiting twelve confirmations defeats the speed advantage entirely. Perhaps the most underrated issue is corporate tax treatment. Issuing or receiving stablecoins can trigger taxable events in some jurisdictions if the accounting system does not clearly separate the underlying fiat value from the token movement. Make sure your finance team tracks the stablecoin as a cash equivalent, not as a digital asset subject to capital gains, unless local law says otherwise. This varies by country and by how your provider structures the conversion. Talk to your tax advisor before you move real volume. The cost of a bad classification on a cross-border invoice is not the same as the cost of a good one.

Implementation Steps
Start by mapping your top ten payment corridors by volume and frequency. Pick the two with the highest frequency. Integrate a regulated provider for those corridors first. Keep traditional wires for the rest until the new path proves stable. Do not attempt a full migration on day one. Build or buy a reconciliation engine. If you already have a Treasury Management System, check whether it supports stablecoin settlement endpoints. Many older TMS platforms do not. You will likely need a middleware layer that receives webhook confirmations from the blockchain and posts them back into your accounting system. Implement KYC and AML screening on every counterparty wallet address before the first transfer. Use a provider like Chainalysis, Elliptic, or TRM Labs, or rely on your payment provider's built-in screening if they offer it. Screen at onboarding and re-screen periodically, because wallet behavior changes over time.
Set internal controls. Require dual authorization for payments above a threshold. Restrict which wallets can receive funds. Cap daily outflow. Log every step. If an auditor asks for proof, you should be able to produce the original invoice, the screening result, the on-ramp receipt, the transaction hash, and the off-ramp confirmation without digging through three different systems.
When CCpayment Is Not the Right Tool
It does not work well for very small remittances under twenty dollars in emerging markets where local agent networks already offer cheap cash pickup. It does not work in jurisdictions where stablecoin use is restricted or where banks block crypto-linked accounts. It does not replace traditional letters of credit for large trade deals with performance risk. It also struggles when the counterparty lacks a digital bank account and can only receive physical cash or traditional wire. If your suppliers are small manufacturers in countries with weak digital banking, consider a hybrid model. Use CCpayment to move the bulk of the value quickly, then route a smaller fiat disbursement through a local agent network for cash handling. That hybrid approach was necessary for a client in Southeast Asia who needed to pay ten thousand small suppliers across three countries. Pure stablecoin delivery left forty percent of the suppliers unable to access funds without a physical visit.
Where to Get Started
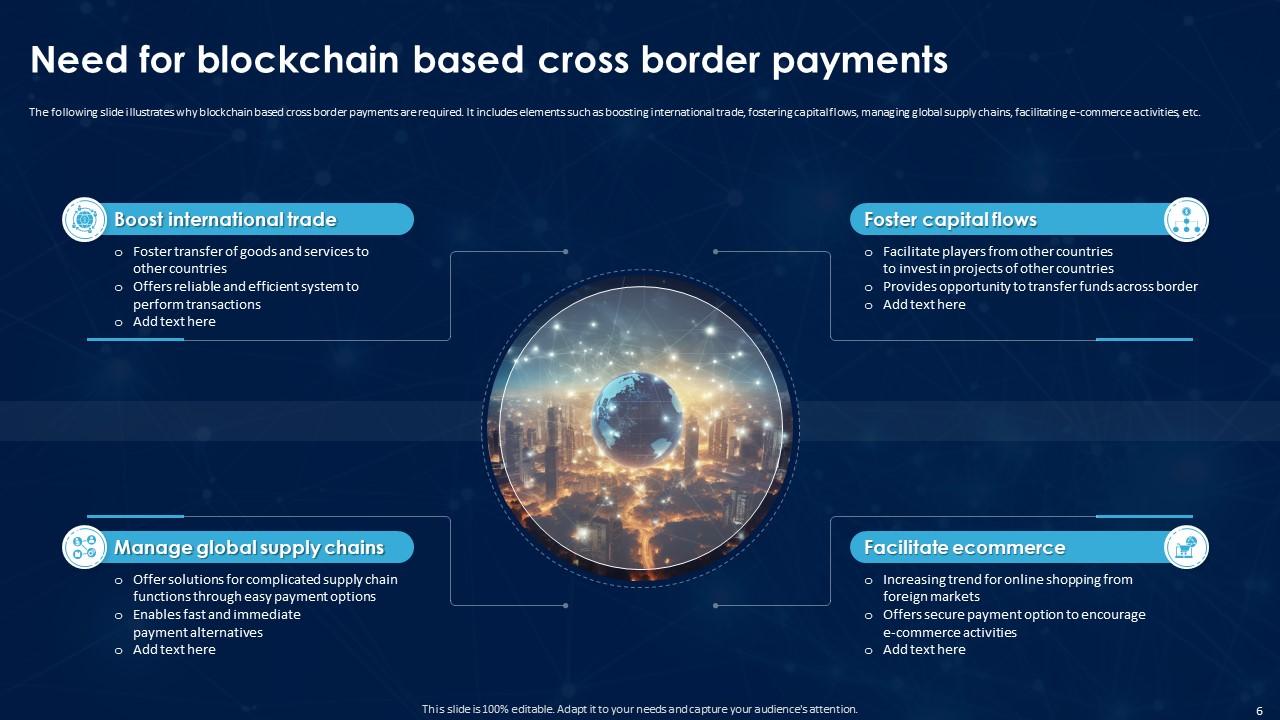
If you want a direct entry point, look at providers that explicitly market cross-border stablecoin payouts. Circle for Business provides USDC corridors with institutional compliance tooling. Stripe's crypto payout products cover select jurisdictions. TransferWise, now Wise, has explored digital asset corridors in certain markets. Payoneer and other merchant acquirers are quietly adding stablecoin settlement options for eligible merchants. For developers, the infrastructure is accessible via APIs. Polygon's enterprise tooling, Solana's Geyser plugins, and Arbitrum's developer grants make it straightforward to build a custom flow. The catch is that building your own flow shifts compliance risk onto you. Decide early whether you want to carry that risk or lease it from a provider. The bottom line is that CCpayment is not magic. It is a different settlement layer with different trade-offs. It is fast, it is cheaper on frequency, and it requires you to think differently about reconciliation and compliance. If you are willing to make those adjustments, it will change how your finance team handles international invoices. If you are not, you will find reasons to fall back to SWIFT within three months.


