Central Bank Independence Actually Works, But Not The Way You Think
Unlocking The Power Of Cbi A Comprehensive Guide To Central Bank Independence
I spent about eight years embedded in monetary policy research before moving to a central bank advisory role. What I learned is that the academic literature on CBI got almost everything right about the theory and almost everything wrong about how it actually plays out in practice. Most guides you'll find online treat this as a simple yes-or-no question. It isn't. Central bank independence refers to the institutional arrangement where a nation's monetary authority operates without direct political control over day-to-day policy decisions. The core mechanism is straightforward. Governments set the mandate, usually price stability with an explicit inflation target. The central bank then decides how to achieve it using interest rates, reserve requirements, and open market operations. Politicians aren't supposed to interfere. In theory this removes the time-inconsistency problem that models have described since Kydland and Prescott wrote about it in 1977. The time-inconsistency problem is worth understanding because it's the entire reason CBI exists as a concept. Without it, governments have an incentive to promise low inflation, then create surprise inflation to boost employment or reduce real debt burdens. Each round of this makes everyone worse off. An independent central bank with a credible commitment device breaks that cycle. Markets believe the inflation target, long-term rates stay anchored, and you avoid the wage-price spiral that follows lost credibility.
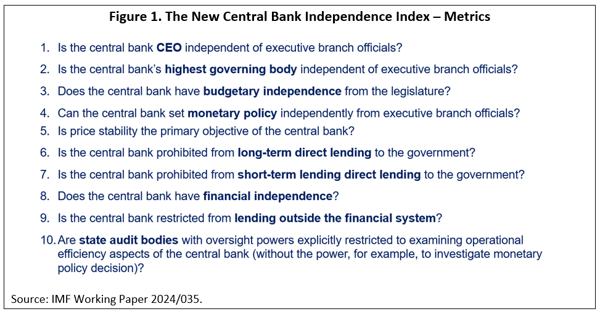
But here is where the standard narrative falls apart. Independence is not binary. There is no on-or-off switch. You have de jure independence written into law and de facto independence that exists in practice. These two measures frequently diverge. I worked through a case study for the Bank of England back in 2016 where the legal framework showed strong independence protections on paper, but the appointment process for the Monetary Policy Committee members was heavily influenced by Treasury preferences. The result was a gap between formal rules and actual behavior that you'd never spot reading the legislation alone. The most useful framework for thinking about this is the independence-accountability tradeoff. Every degree of autonomy you give a central bank is a degree of democratic control you remove. The European Central Bank is the textbook example of maximum independence with relatively weak democratic accountability. Its president addresses the European Parliament but has no direct political removal mechanism. The Federal Reserve sits somewhere in the middle with congressional mandate and presidential appointments subject to Senate confirmation. The Reserve Bank of New Zealand pioneered the compact model where the minister sets the target and the governor is contractually obligated to hit it, with clear dismissal terms for failure. What most people miss about CBI is that the institutional design matters enormously for outcomes. Two countries with identical independence scores on the Cukierman index can have wildly different inflation performance depending on governance structure, communication norms, and the strength of fiscal constraints. Germany's Bundesbank and Canada's central bank both had high formal independence, but Canada's approach of publishing detailed inflation reports and holding press conferences after every rate decision created a different kind of credibility than Germany's more opaque operational style. Both worked. One was far more transparent about how decisions were reached.
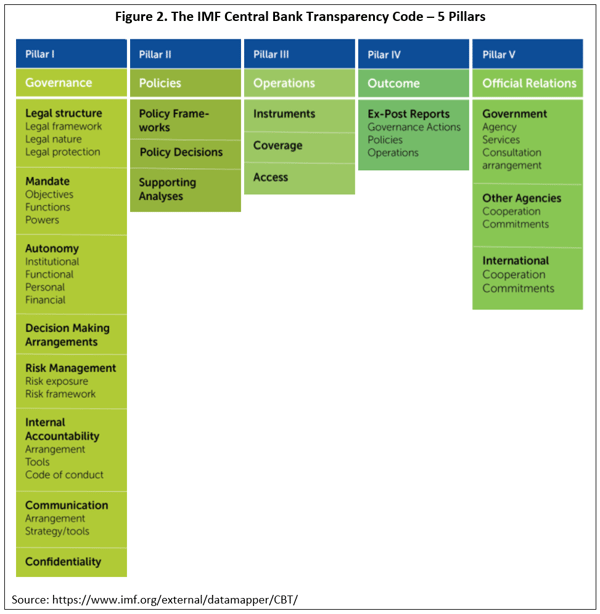
The counter-intuitive part is this: moderate independence with strong accountability mechanisms often produces better outcomes than maximum independence with weak oversight. A central bank that can't be sacked for missing targets has no incentive to listen. The Brazilian case from the early 2000s illustrates this clearly. The central bank gained formal independence in 1999 alongside the floating exchange rate regime, but inflation remained volatile for several more years because the political class found informal ways to pressure the board through budget allocations and public attacks. Credibility took until around 2005 to consolidate, and even then the institutional arrangement was messy. Let me address the implementation side because this is where the rubber meets the road. When you're evaluating or designing a CBI framework, you need to look at six specific institutional components. The appointment process for leadership determines whether governors can survive political cycles. The mandate clarity question asks whether the target is singular or multiple and whether tradeoffs between objectives are defined. Fiscal dominance is the silent killer of independence. If the treasury cannot service its debt and the central bank is legally required to monetize the difference, independence becomes fiction. Communication policy matters more than most policymakers admit. The market's expectation of where rates are going is almost as important as the actual rate setting. Operational autonomy covers the tools and methods. Legal protection from direct political interference is the baseline requirement. Budgetary independence ensures the bank isn't financially coerced. I ran into a specific problem while advising a developing economy's central bank reform in 2019. The draft legislation gave the bank full independence in law but kept the finance ministry's approval requirement for any interest rate change above 50 basis points in a single meeting. On paper this looked like a reasonable safeguard against abrupt moves. In practice it meant the bank had to propose rate changes that would survive political scrutiny rather than changes that the economic data actually required. We spent three weeks modeling the distortion effect and found it was creating an average delay of four to six weeks in monetary responses compared to the bank's internal forecasting timeline. The workaround was straightforward but politically difficult. We restructured the provision to require notification rather than approval, similar to the UK model where the Chancellor receives notice of rate decisions but cannot veto them. The finance ministry still retained oversight through the announcement mechanism without gaining operational blocking power.
Get the Full Details
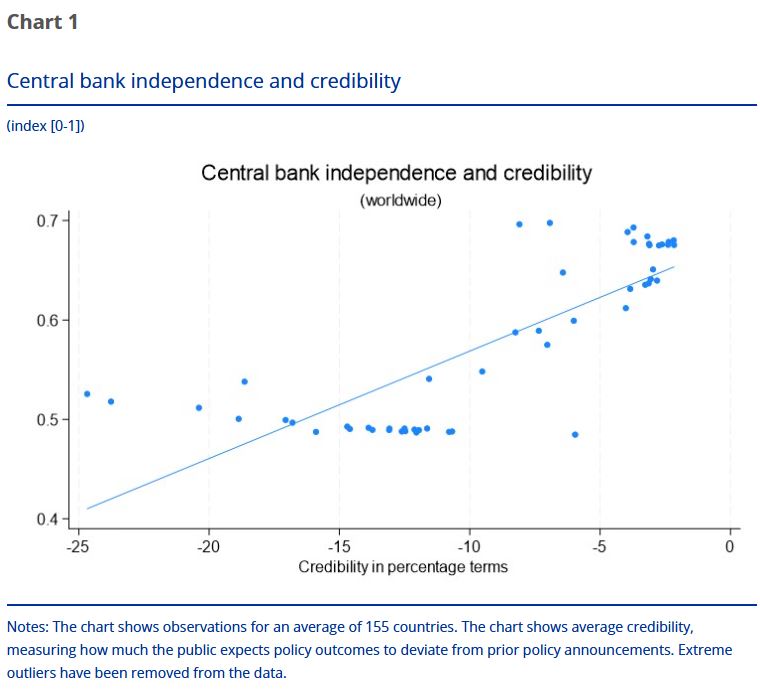
The empirical evidence on CBI outcomes is remarkably consistent across decades of research. Countries with higher independence indices consistently show lower inflation expectations without statistically significant differences in output or unemployment performance. The Ball and Cecchetti study from 1990 remains one of the cleanest demonstrations of this. More recent work by Alesina and Summers found the same pattern across OECD countries. The effect is stronger in democracies than in authoritarian regimes, which should not be surprising. Independent central banks in non-democratic systems tend to serve regime stability rather than price stability, which means they are independent from the public but not from the ruling power structure. Here is something you won't find in the introductory textbooks. The effectiveness of CBI depends heavily on the state of fiscal policy. When fiscal policy is loose and sustained, monetary independence becomes increasingly constrained regardless of what the law says. This is the fiscal theory of the price level in action. A central bank can raise rates all it wants, but if the government is running persistent deficits that require bond market absorption, the rate path becomes endogenous to fiscal necessity rather than inflation dynamics. The Bank of Japan's experience since 2013 is a contemporary example where yield curve control had to accommodate massive fiscal expansion. The Bank of England faced the same constraint during the 2022 gilt crisis when minimal fiscal stance adjustments forced an unwinding of quantitative easing that the MPC had not planned for. The common pitfalls I see people miss when evaluating CBI frameworks. First is assuming that legal independence automatically translates to behavioral independence. It does not. Second is ignoring the appointment process, which is where real control lives. Third is overlooking fiscal dominance as a constraint that operates regardless of the central bank's stated mandate. Fourth is treating inflation targeting as synonymous with independence when some of the most independent central banks in history operated under commodity standards without any explicit target. Fifth is forgetting that communication policy is itself a tool of independence, because markets that understand a bank's reaction function are more likely to coordinate expectations correctly.
There are scenarios where central bank independence simply does not solve the problem you think it will. In economies with shallow financial markets and limited policy transmission mechanisms, an independent central bank cannot effectively control aggregate demand through interest rates. The Zimbabwe case is extreme but instructive. The Reserve Bank gained nominal independence in the 1990s, but hyperinflation was driven by fiscal collapse and institutional breakdown that no amount of monetary autonomy could prevent. Similarly, in currency unions like the Eurozone, individual member states surrender monetary sovereignty entirely, making CBI questions about national central banks somewhat abstract. The real independence debate shifts to the ECB level and the tension between unified monetary policy and fragmented fiscal policy across member states. The alternative to full CBI is what some economists call directed policy with statutory flexibility. This approach gives the central bank operational discretion within a narrowly defined mandate that includes multiple objectives like employment, financial stability, and growth alongside inflation. The US Federal Reserve operates closer to this model than the inflation-targeting regimes in Europe. Whether this is superior depends on your weighting of goals. Proponents argue that multiple mandates provide necessary flexibility during crises. Critics counter that they give central banks an excuse to chase political objectives under the guise of discretion. The truth is probably somewhere in the middle, and the evidence suggests that the specific mandate design matters less than the consistency and credibility with which it is enforced. If you are looking at this from a policy design perspective, the practical takeaway is that institutional arrangements matter more than labels. The words independence and accountability in any constitution or central bank act need to be examined against the actual appointment procedures, the fiscal framework, the communication protocols, and the historical record of political interference. Reading the legal text alone will give you a false sense of certainty. I have reviewed central bank legislation from a dozen countries and the gap between written rules and operational reality was consistently larger than I expected. The most reliable indicator of true independence is not what the law says but how quickly and forcefully the bank responds to inflation pressures without waiting for political signals. When that response is consistent across cycles, the institution has earned credibility. When it is selective or delayed, the formal protections are mostly decorative.