Understanding Brazil's Hydro Baseload: The Reality on the Ground
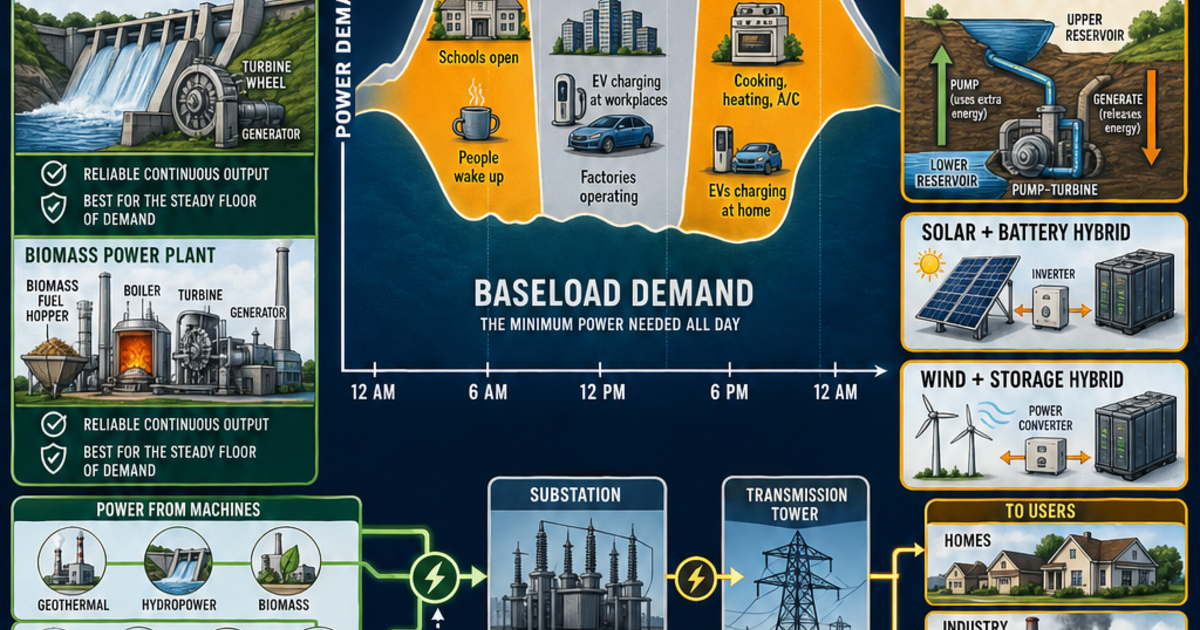
Brazil generates roughly 60% of its electricity from hydroelectric sources, and that number fluctuates yearly depending on rainfall. This isn't a fun fact. This is the structural reality that anyone working in the Brazilian energy sector has to account for. When the reservoirs are full, everything runs cheaply. When they drop below 40%, the math changes fast. I've spent the last eight years looking at dispatch models and basin hydrology for distributed generation clients, and the thing nobody tells you is that "baseload" in Brazil doesn't mean what it means in Texas or Germany. Hydro baseload here is conditional. It's weather-dependent insurance, not a guaranteed floor. The Usina Hidrelétrica projects you hear about in press releases are only half the story. The other half is how they're actually operated within the AIS (Ambiente de Contratação Livre) and ACL markets, and that operational reality is where the money gets made or lost.
Unlocking The Power Of Baseload Generation How Usina Hidrel Is Revolutionizing The Energy Sector In Brazil
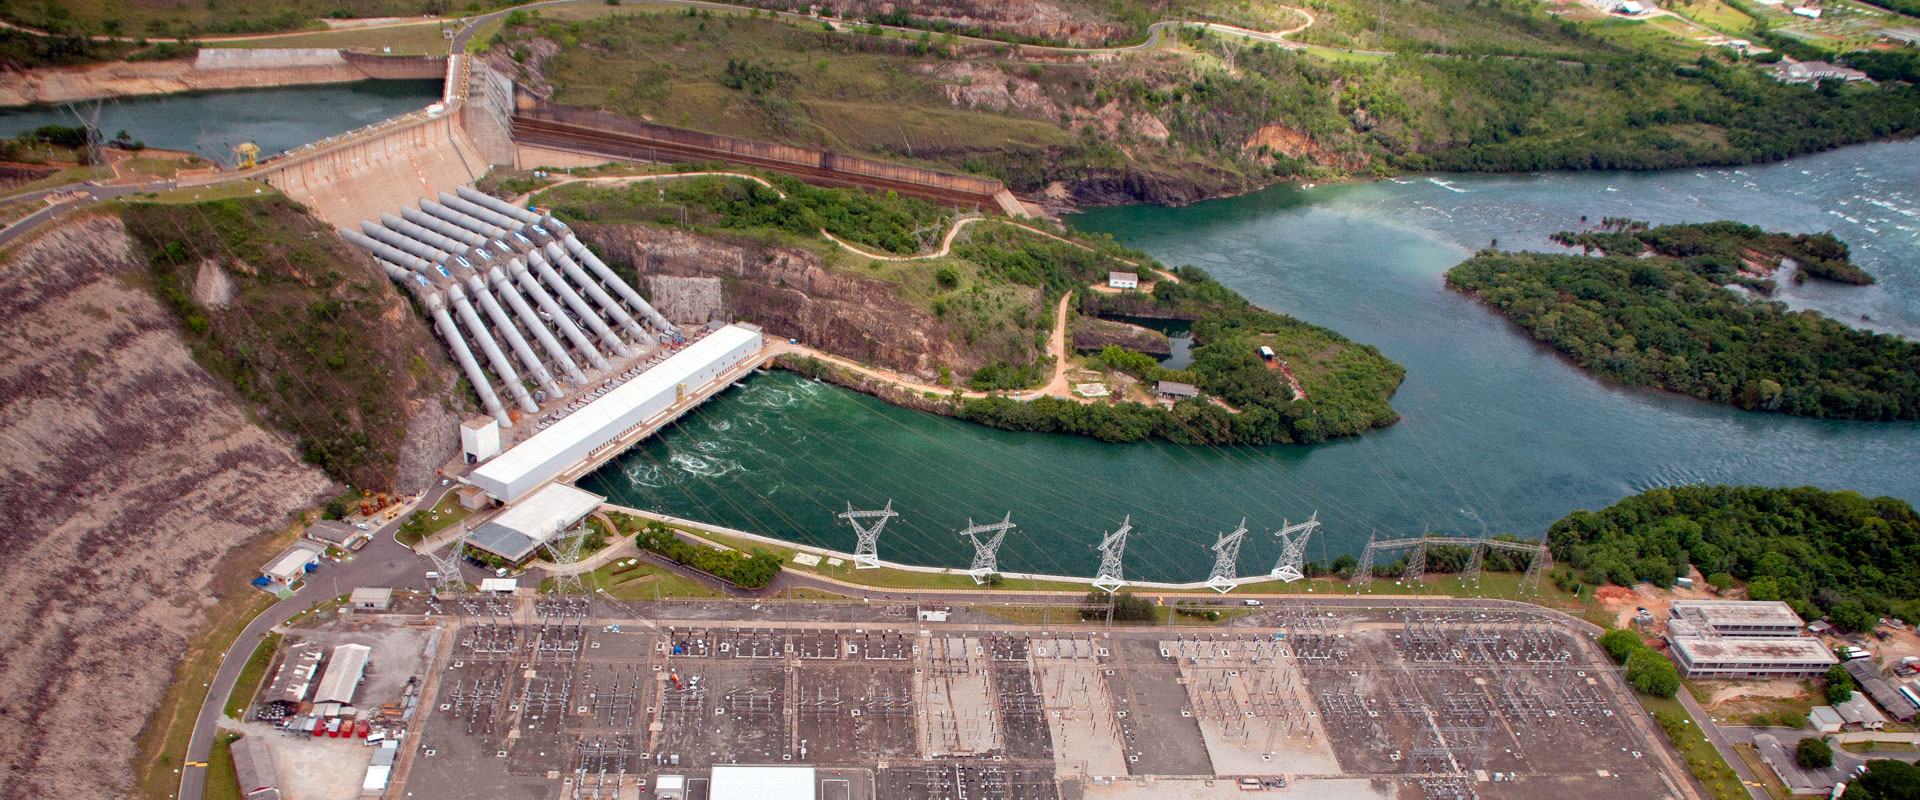
To actually understand what's happening, you need to look past the installed capacity numbers and into the dispatched energy. A plant might have 1000 MW of nameplate capacity, but its annual average dispatch could be 400 MW after accounting for seasonal flow variations, sedimentation, and environmental flow requirements. The gap between those two numbers is where most project financiers get burned. The revolution people are talking about isn't really about building new mega-dams. Brazil has built most of the viable ones already. It's about retrofitting existing infrastructure, adding pumped storage, and integrating hydro with wind and solar in ways that smooth out the generation profile. Plants like São Luiz do Tapajós and the newer units at Jirau and Santo Antônio represent a shift toward smaller, more flexible installations that can respond to grid signals rather than running at fixed output. That flexibility matters more than raw capacity when you're dealing with a grid that's increasingly intermittent. From a practical standpoint, here's what you need to know if you're evaluating hydro assets or considering how they fit into a broader energy strategy:
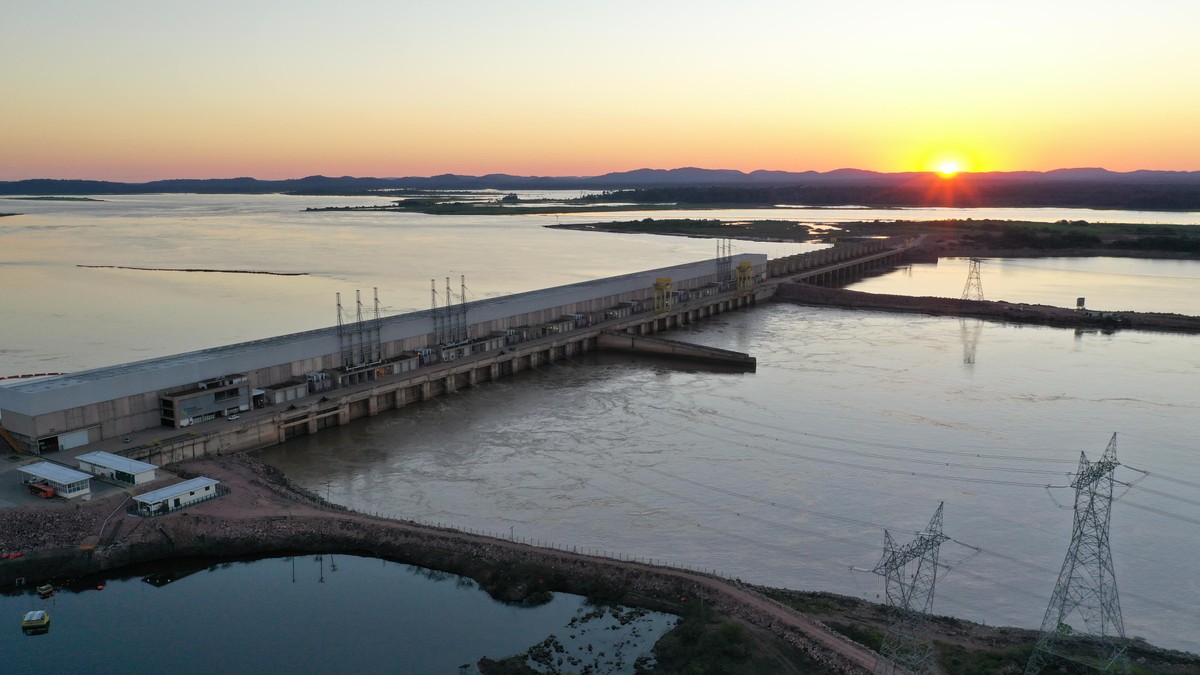
Reservoir classification is everything. Regulated reservoirs (usinas com reservatório de regularização) can store water and dispatch on demand. Run-of-river plants (usinas a fio d'água) generate based on whatever flow is coming through that day. The revenue profiles are completely different. Regulated plants can participate in the CCEE (Camera de Comercializacao de Energia) as dispatchable generators. Run-of-river plants are priced more like intermittent sources even though they're technically hydro. I've seen deals fall apart because the buyer assumed a run-of-river asset had storage capacity it didn't actually have. SEDEN and the hydro risk premium. When reservoir levels drop, Brazil triggers a thermal substitution mechanism where expensive gas and coal plants run instead of hydro. This is managed through the SEDEN (Sistema de Estimulacao a Geracao de Energia Eletrica de Fonte Nao-Convencional) and related regulatory frameworks. For off-takers, this means your energy contract price can swing dramatically between wet and dry years. In the 2021 crisis, some contracts priced at R$50/MWh in a normal year became economically irrelevant because the alternative thermal generation cost was R$300+/MWh. The hedging instruments for this exist but are underutilized. Pumped storage is the missing piece. Brazil has very limited pumped hydro compared to what the grid actually needs. The Mirador project in Roraima and the planned initiatives in Minas Gerais are steps in the right direction, but the pipeline is thin. If you're looking at long-term grid stability, this is the bottleneck. Without adequate storage, hydro baseload remains seasonally constrained regardless of how many turbines you install.
Get the Full Details

Here's the edge case that cost a client of mine about 18 months and roughly 2.3 million reais in legal fees: we were structuring a PPA for a mixed hydro-wind portfolio in the Northeast, and the hydro component was sourced from a regulated concession with an old licensing timeline. The environmental licensing (licenciamento ambiental) had conditional restrictions on downstream flow that weren't reflected in the generation simulations. The model assumed 95% availability. Actual availability during the dry season of year three dropped to 67% because the mandated environmental flow exceeded what the reservoir could sustain without violating downstream community water rights. We caught it too late in the due diligence process. The workaround was restructuring the PPA to treat the hydro portion as a curtailment-risk asset rather than firm capacity, which meant pricing it closer to the wind component and adjusting the contraction factor accordingly. It saved the deal but compressed margins significantly. The key lesson from that was that historical generation data is a poor predictor for hydro in Brazil's current climate trajectory. Recent ANA (Agencia Nacional de Aguas) data shows a discernible trend toward longer dry spells in the Southeast-Central and Northeast basins. Any baseload projection that doesn't incorporate climate-adjusted flow scenarios is going to be wrong, usually on the optimistic side. What this means for market participants:
If you're a generator, the regulated market (ACL) offers volume certainty but price ceiling risk. The free market (CPL/AIS) offers price upside but volume uncertainty, especially for hydro assets during deficit years. The smart play right now is blending both, using the regulated contract as a hedge against wholesale price spikes while capturing margin in the free market during surplus periods. If you're a consumer or trader, don't assume hydro exposure equals stability. It equals weather exposure. The best contracts I've structured include hydro generation from multiple basins (parana, sao francisco, nordeste) to diversify climate risk, combined with wind or solar to balance seasonal patterns. Hydro tends to be stronger in the dry winter months in the southeast, while wind picks up in the spring and early summer in the northeast. That complementarity is real and measurable, but only if you're modeling it correctly. The technology side is advancing too. Modern turbine retrofits at existing plants like Itaipu have pushed efficiency from around 82% to over 91% in some units. That's not a small number. It means you can generate more energy from the same water flow without building anything new. Itaipu alone added roughly 250 MW of effective capacity through modernization without a single cubic meter of additional reservoir volume. That's the kind of baseload expansion that doesn't require new environmental licensing, which in Brazil is the real bottleneck, not engineering or capital.
Looking ahead, the grid operator (ONS) is pushing for more flexibility resources. Hydro plants that can ramp quickly and provide ancillary services like frequency regulation are becoming more valuable than plants that just produce steady MWh. The market is beginning to price that distinction, but the transition is uneven. Some distribution companies still treat all hydro the same on paper. The sector isn't going to keep growing through massive new dam construction. The low-hanging fruit is gone, and the environmental and social licensing barriers for new projects are higher than they've ever been. The real revolution is incremental: modernization, integration, storage, and smarter dispatch. Anyone still pitching greenfield mega-dams as the solution to Brazil's energy needs is either selling something or hasn't been paying attention to the last decade of project cancellations and delays.