Property Transfers Without Title Insurance Problems
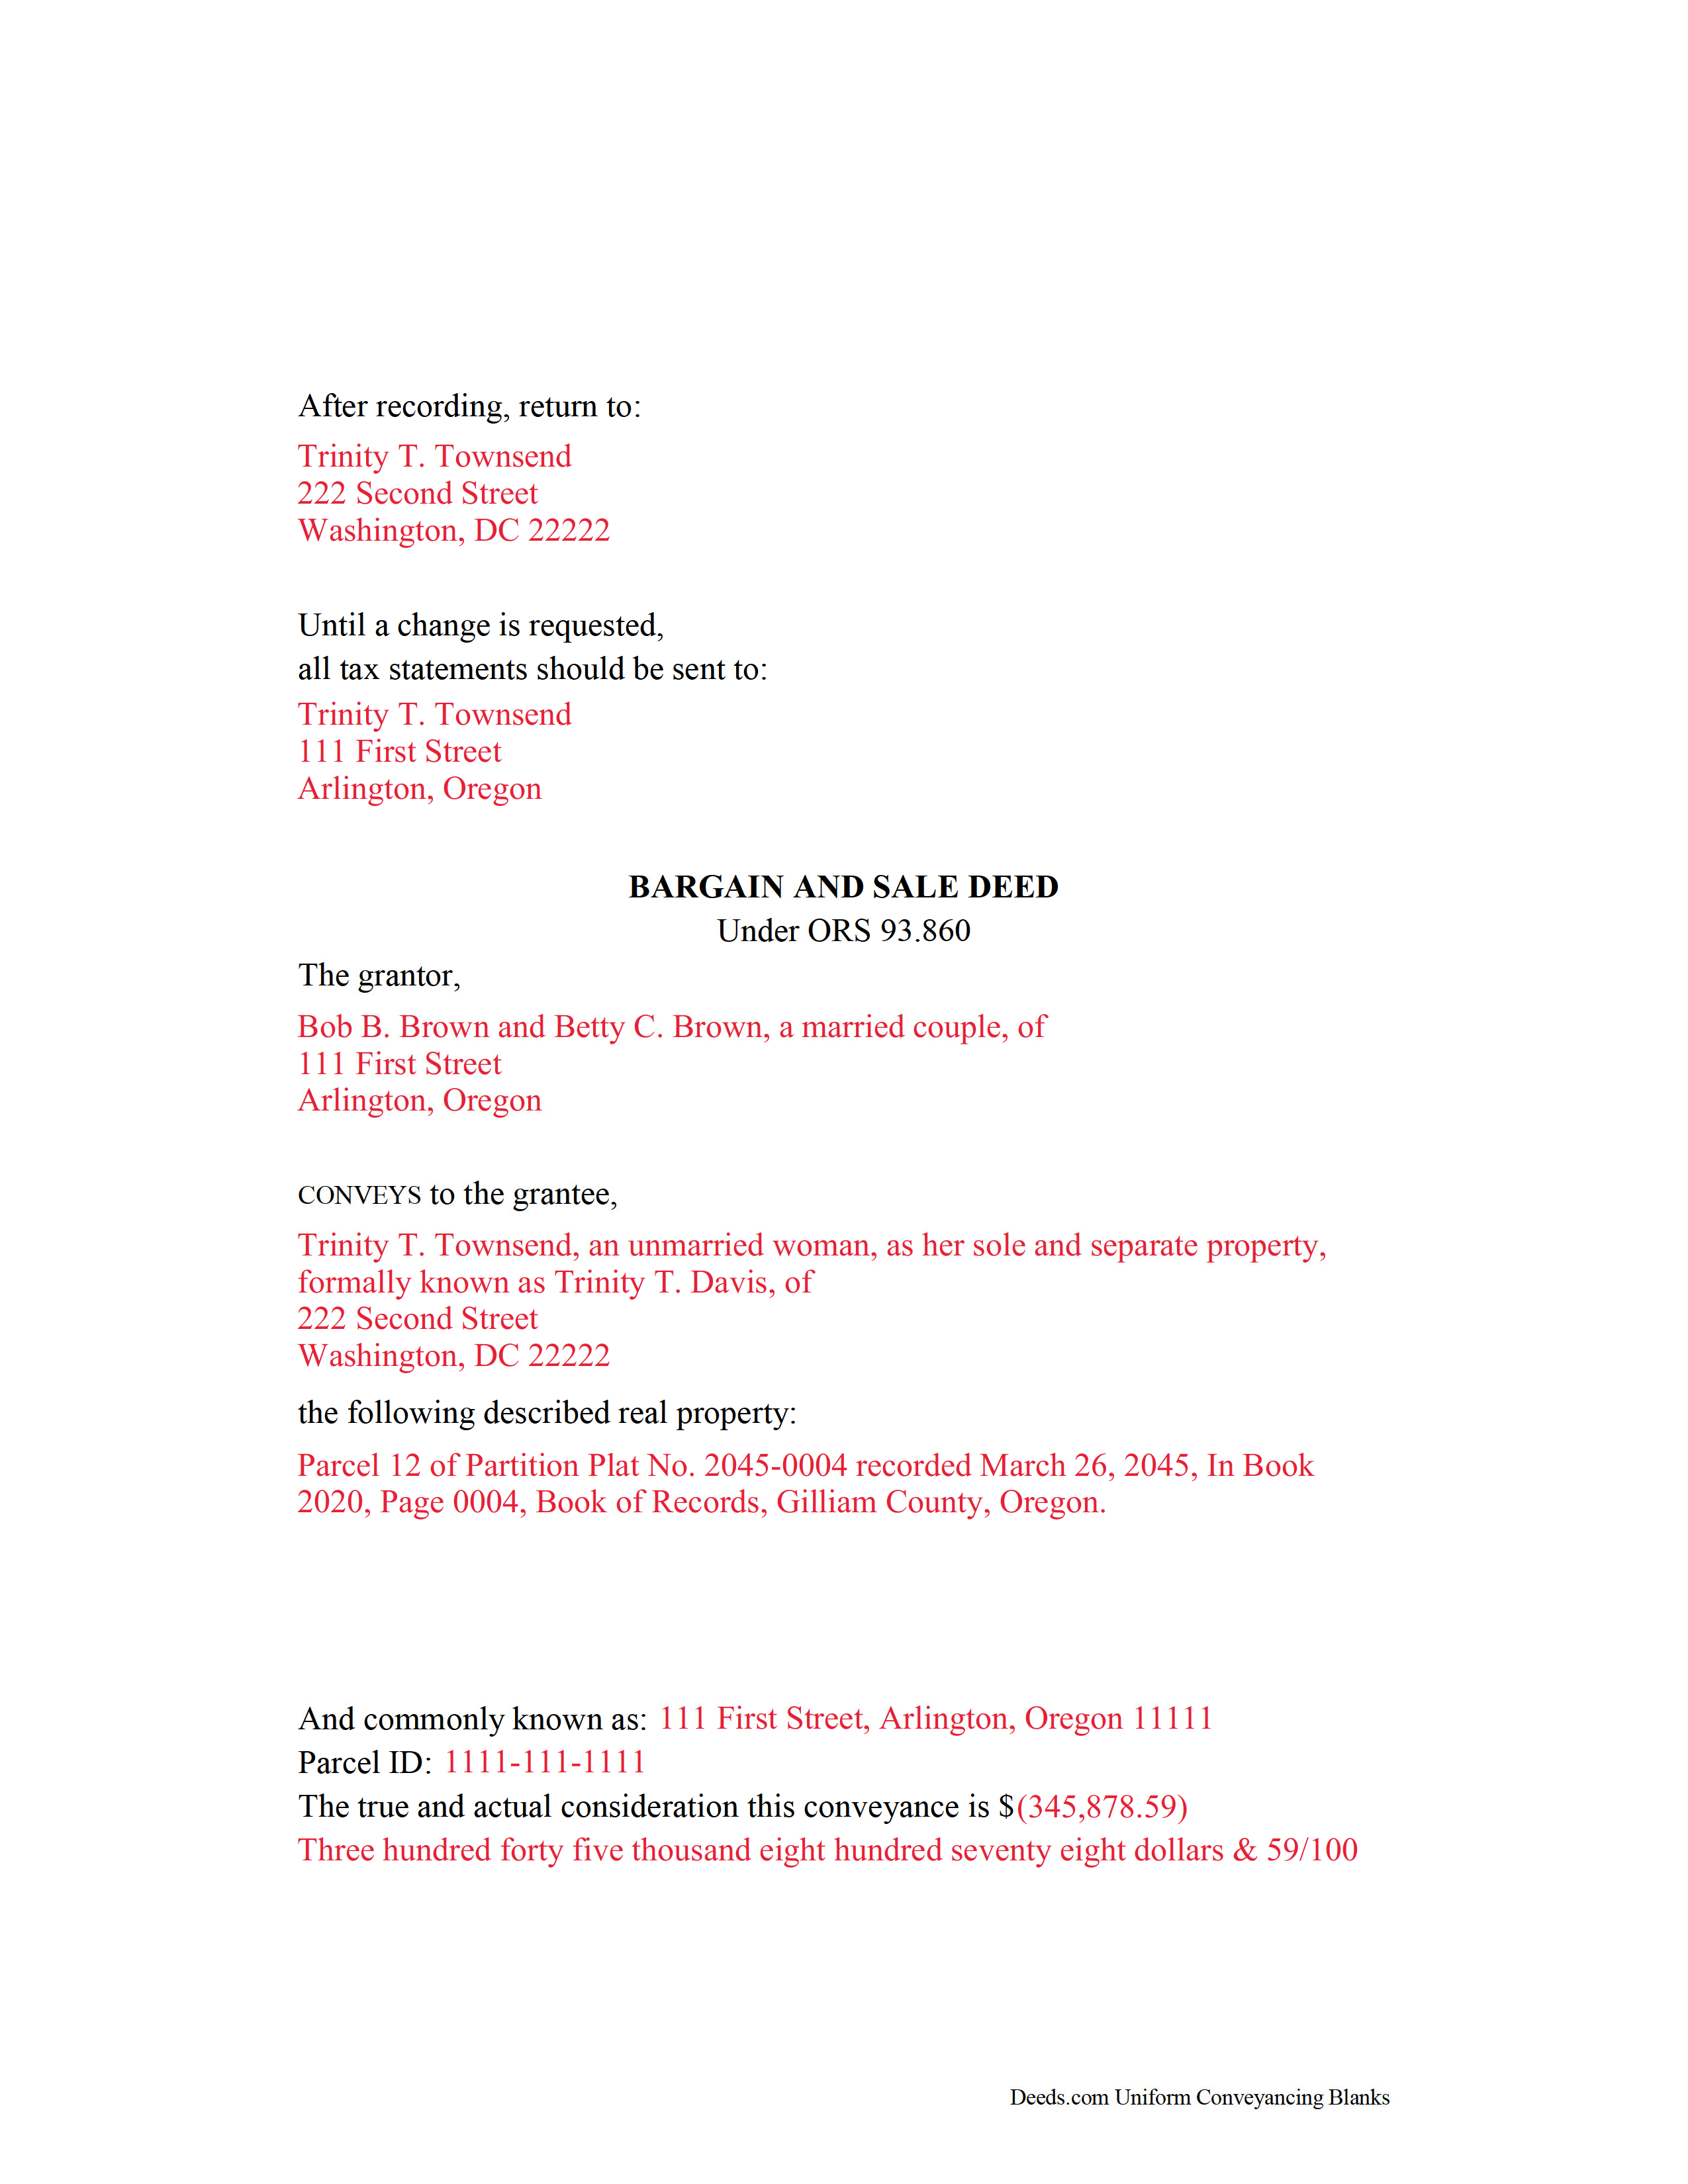
A bargain and sale deed is one of the most misunderstood instruments in real estate law. When you use this type of deed, you are transferring whatever interest you hold in a property, but you are not providing any warranties about the title. The grantor is essentially saying I own this property and I am conveying it, without guaranteeing that the title is clear or that there are no liens or encumbrances. This distinction matters more than most people realize, and getting it wrong can cost you months of legal fees. I have been working with property transfers for over twelve years, and I still encounter people who confuse bargain and sale deeds with warranty deeds without understanding the real consequences. The key difference comes down to what protections the grantee receives. With a general warranty deed, the grantor guarantees against all title defects, even ones that arose before they owned the property. A bargain and sale deed offers zero such protection. It simply conveys the grantor current interest in the property with no promises about what might surface later. The main advantage of a bargain and sale deed is speed and simplicity. In foreclosure situations, tax sales, or estate settlements, the person conveying the property may not have complete knowledge of the title history. They cannot reasonably warrant against problems they do not know exist. This is why foreclosure companies and government entities prefer this form of deed. It protects them from future liability while still allowing the property to transfer efficiently.
When I handle these transactions, I usually recommend that the grantee obtain title insurance regardless of which type of deed is used. A bargain and sale deed does not eliminate the need for insurance, and relying on the deed alone as protection is a mistake I see repeatedly. Title insurance will cover you against defects that were not discovered during the title search, and it remains valid even after the deed has been recorded. The cost of a title insurance policy is typically between 0.5 and 1 percent of the property value, which is negligible compared to the potential loss from an undiscovered lien or ownership dispute. One specific edge case I dealt with involved a client who purchased a commercial property through a bargain and sale deed from a deceased estate. The title search came back clean, and everything appeared straightforward. Six months after closing, a contractor filed a mechanics lien dating back three years, claiming unpaid work on the property. Because the deed provided no warranties, my client had no legal recourse against the estate executor. The only remedy was through the title insurance policy, which covered the full amount of the lien. If my client had skipped the title insurance assuming the deed was sufficient, they would have been personally responsible for a twenty three thousand dollar debt on a property they thought they owned free and clear. Recording a bargain and sale deed follows the same procedural steps as recording any other deed. You need to prepare the document with the correct legal description of the property, ensure all required signatures are present and notarized, and file it with the county recorder's office where the property is located. The recording fee varies by jurisdiction, typically ranging from fifty to two hundred dollars depending on the county and the number of pages in the document. Processing time usually takes between five and fifteen business days, though some counties offer expedited recording for an additional fee.
There are scenarios where a bargain and sale deed is not appropriate or even legally acceptable. Some states restrict the use of this deed type for certain transactions. California, for example, does not recognize bargain and sale deeds with covenants against grantor's acts in residential transactions, and using the wrong form can invalidate the transfer or create complications during future sales. Always verify the specific requirements in your jurisdiction before proceeding.
Get the Full Details

Common Pitfalls and What to Watch For
The biggest mistake buyers make is assuming a bargain and sale deed provides more protection than it actually does. The language in these deeds is often boilerplate and lacks the covenants found in warranty deeds. Some bargain and sale deeds include covenants against the grantor's acts, which provide limited protection by warranting that the grantor has not encumbered the property during their ownership. However, this still does not protect against defects that existed before the grantor acquired the property. Understanding the exact scope of protection is critical before accepting this type of deed in any transaction. Another issue arises when the grantor does not actually hold clear title to the property. A bargain and sale deed only conveys whatever interest the grantor possesses. If the grantor's ownership is disputed, subject to an unresolved probate, or affected by an undisclosed spouse with dower rights, the grantee may receive a deed that is worthless in practice. Running a thorough title search and reviewing the chain of title is essential, and it should never be treated as an optional step. In my experience, the turnaround time for a properly prepared and recorded bargain and sale deed in a straightforward residential transaction is approximately two to three weeks from drafting to recording confirmation. Complications such as unresolved liens, boundary disputes, or missing signatures can extend this timeline significantly, sometimes by several months. Planning for the worst case scenario during the initial negotiation phase prevents surprises later in the process.
A bargain and sale deed is a useful tool in specific situations, particularly when the grantor cannot or will not provide title warranties. It is the standard instrument for many foreclosure and tax sale transactions, and it can be appropriate in arm's length transfers between family members where both parties understand the limited protection. However, it should never be used carelessly or without proper due diligence. The convenience of a simpler deed does not outweigh the risk of inadequate title protection, and combining a bargain and sale deed with a solid title insurance policy is the standard approach that protects all parties involved.