What This Actually Is
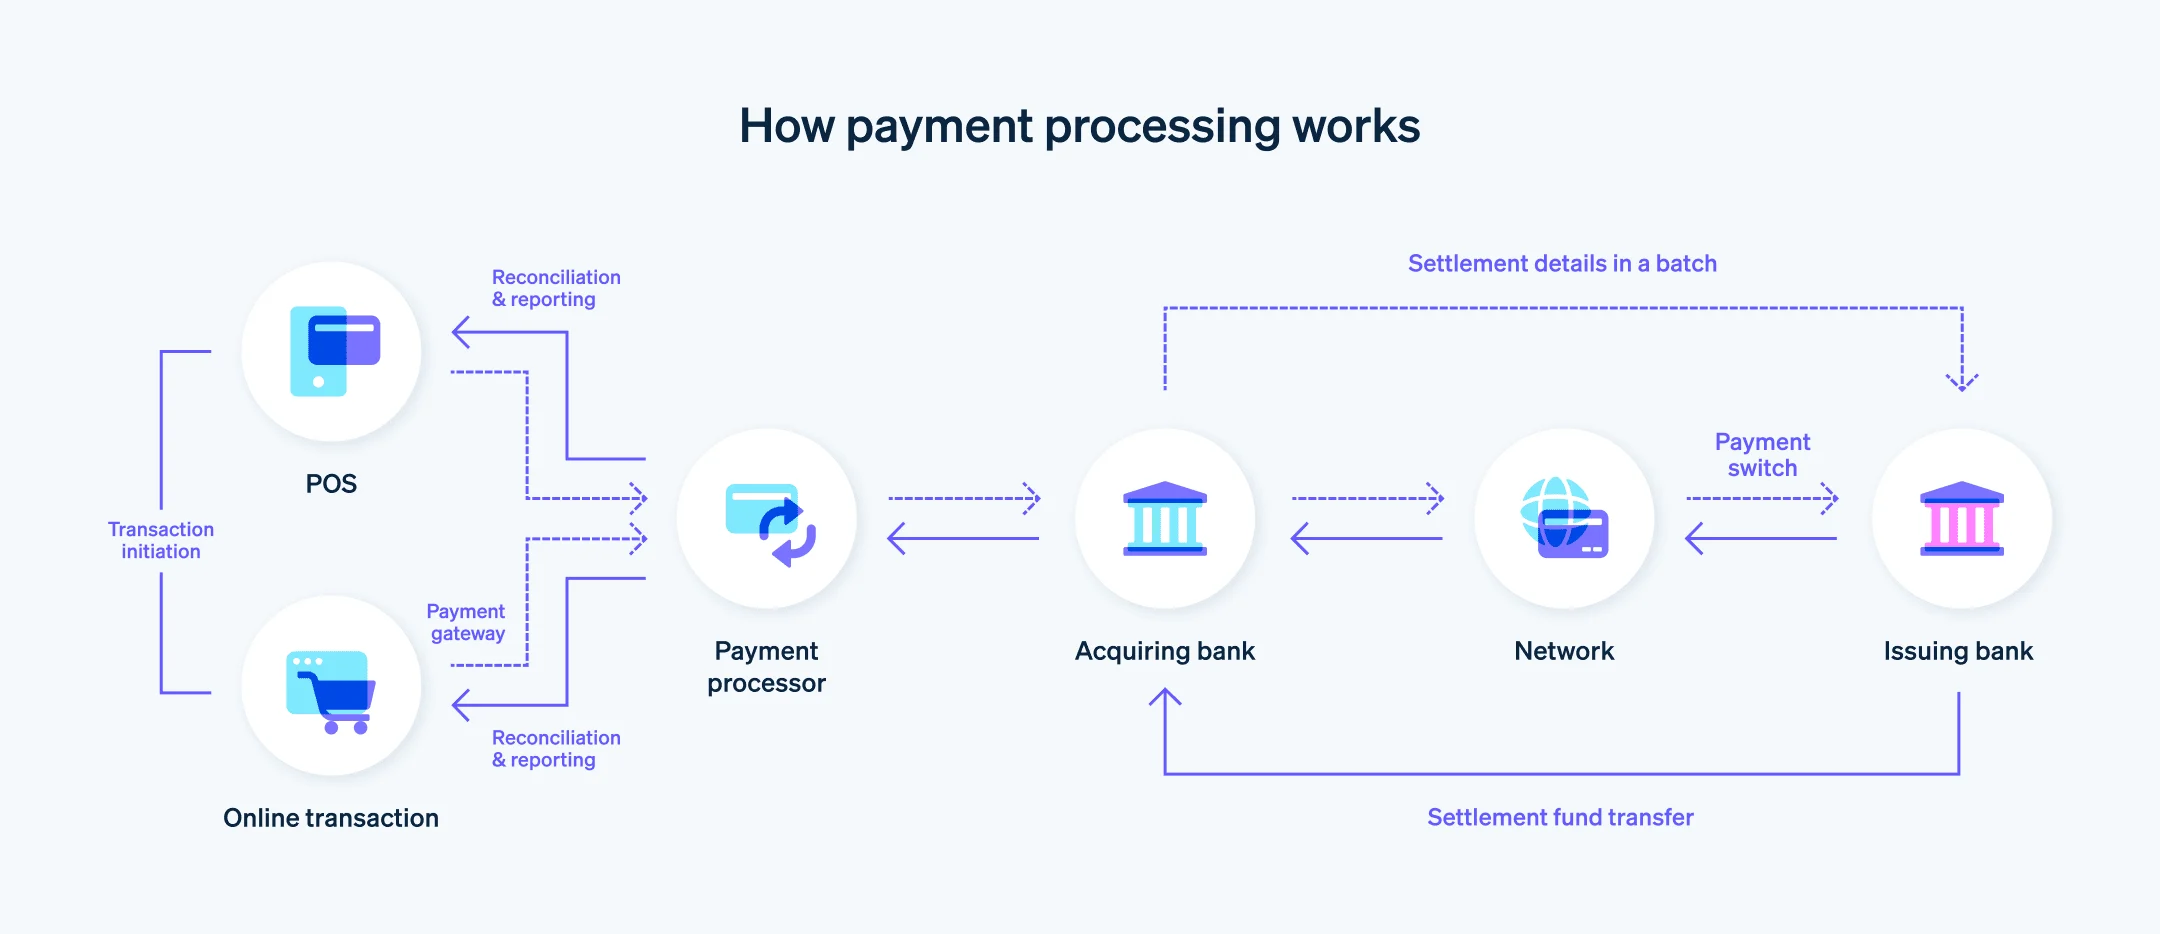
The VSI Ehub platform is a payment orchestration and merchant aggregation layer that sits between acquiring banks and merchants. I first ran into it around 2019 when a mid-market client wanted to consolidate three separate merchant accounts under one reporting dashboard. The old-school way was to write custom middleware, pull APIs from each acquirer, and stitch everything together. VSI Ehub tried to do that for you. It handles routing, settlement, reporting, and sometimes fraud scoring depending on which module you enable. The product has gone through rebrands and ownership changes over the years, so documentation can point you in different directions. The core idea hasn't changed much though.
Unlocking The Potential Of Vsi Ehub The Next Generation Of Payment Processing
Let me walk through how to actually get this running without losing three weeks to configuration issues. First, you need a merchant agreement in place. This isn't a self-serve signup. You'll need your banking correspondent to provision the account, which usually means submitting business registration documents, terminal configurations, and sometimes proof of existing transaction volume. The timeline varies wildly depending on the region and acquirer relationship. Once you have credentials, the integration starts with the API authentication setup. VSI uses OAuth 2.0 for most endpoints, but their older SOAP-based settlement endpoints still require basic auth in some regions. I found this out the hard way when a client in Southeast Asia got their sandbox credentials, built a full REST integration, and then couldn't pull settlement reports because their region had dropped SOAP support only six months earlier. Here's what actually matters for the integration: you'll work with three main endpoint groups. Transaction processing for authorization and capture. Query endpoints for checking status, retrieving receipts, and handling disputes. And settlement endpoints for pulling daily batch files and reconciliation data. Most merchants only use the first two and forget about settlement until they have a T+1 reconciliation mismatch and nobody knows where the money went.
The Setup Process
Get your sandbox access from VSI support. They usually provide test merchant IDs, API keys, and a set of test card numbers that simulate different outcomes: approved, declined, insufficient funds, CVV mismatch. Make sure you test all four. The decline codes matter because your customer support team needs to display the right error message, not just "transaction failed." Then configure your webhook endpoints. VSI Ehub supports async callbacks for transaction events. I always recommend setting these up before you go live because synchronous polling adds latency and puts unnecessary load on both your servers and theirs. Webhooks should be idempotent, meaning you can process the same callback twice without duplicate charges or orders. That happens. I've seen it happen in production when a network timeout causes a retry. For the actual code, I typically start with the auth flow. Use the client credentials grant to get an access token, cache it with a short TTL, and refresh before expiry. Token expiry times differ between sandbox and production. Sandbox tokens sometimes last longer than documented, which gives a false sense of security. Don't rely on it.
Get the Full Details

Here's a practical example of how a basic authorization request looks in production: You POST to the transaction endpoint with merchant ID, amount in the smallest currency unit, card token or PAN, CVV if required, and a unique order reference. The response comes back with a transaction ID, approval code if successful, and a risk score if fraud screening is enabled. Always store the transaction ID locally tied to your order. You'll need it for refunds, chargebacks, and reporting.
Common Problems and What I've Done About Them
The biggest issue I keep encountering is currency handling. VSI Ehub accepts amounts in the smallest unit, but some regions round differently. A client in Brazil was losing 0.03 BRL per transaction because their system passed amounts with cents and VSI was rounding to the nearest real. Over a month, that added up to noticeable revenue leakage. The fix was to switch to integer-only amounts and handle the rounding at the application level before sending requests. Another thing that trips people up is the date format. The API uses ISO 8601, but some SDK wrappers accept epoch timestamps or local date strings. I learned this when a merchant in Mexico City sent timestamps in UTC but their server was running local time, and settlement reports showed transactions appearing on the wrong day. Easy to miss until you're doing month-end reconciliation. Dispute handling is where most integrations fall apart. The VSI portal lets you upload evidence, but the automated dispute response requires specific document formats and metadata. If you're processing more than a few hundred disputes per month, you'll want to automate this with the evidence submission API rather than doing it manually through the web interface. The API endpoint is under-documented, but it works once you figure out the required XML structure.
What This Doesn't Solve
Let me be clear about the limitations. VSI Ehub is an aggregation layer, not a replacement for your acquiring bank relationship. If a card scheme changes its rules, VSI will update their platform eventually, but there's always a lag. You still need your own compliance stack for PCI DSS, your own fraud monitoring, and your own reconciliation process. The reporting module is decent for basic settlement tracking but inadequate for anything requiring custom segmentation or real-time analytics. I've seen merchants run their reports through VSI, export the data, and then reload it into their own BI tools. It's redundant but necessary if you need cohort analysis or customer lifetime value calculations. Customer support is another gap. The platform provides ticket-based support, but response times range from a few hours to a couple of days depending on severity. When you're processing millions per month and a critical bug hits on a Friday evening, that's a problem. Some merchants keep a dedicated line through their banking correspondent for urgent issues. It costs more but it exists.

If your transaction volume is under $50,000 monthly, the complexity of integrating with VSI Ehub may not be worth it. Standard payment gateways like Stripe, Adyen, or even direct acquirer APIs are simpler and faster to implement. VSI Ehub makes sense when you need multi-acquirer routing, cross-border settlement optimization, or custom fraud rule engines that the smaller platforms don't offer. The onboarding process alone takes two to four weeks, and integration testing adds another one to three depending on how many edge cases you need to handle. Factor that into your timeline before you commit to the platform.