What That Charge Actually Is
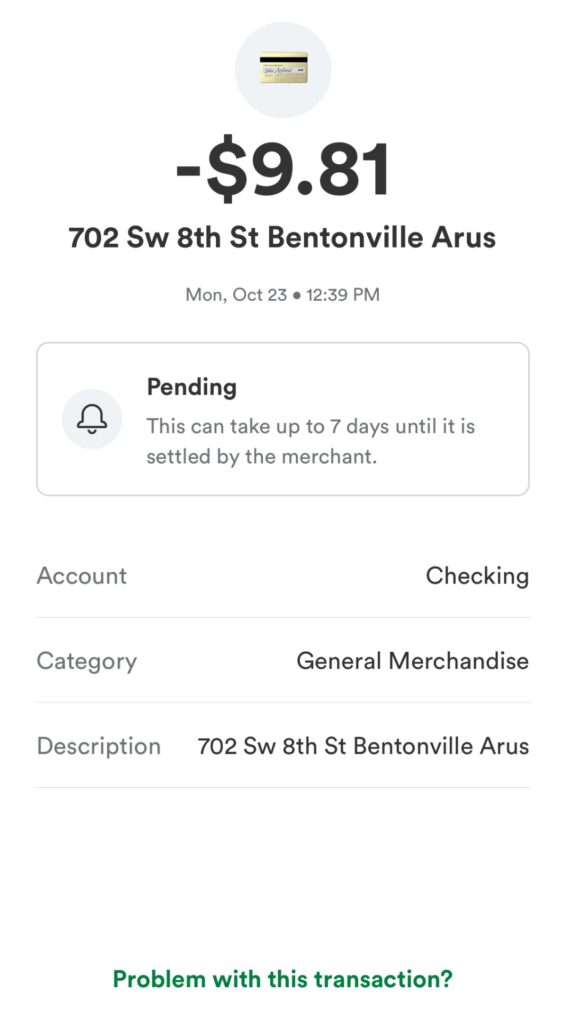
When you see 702 S Bentonville Arus Charge On Chime Card, it means someone used your Chime card to pay a merchant whose legal or billing entity is registered at that address in Bentonville, Arkansas. That address happens to sit in a commercial corridor near the Northgate area. The charge itself is not inherently suspicious. Most of the time, this is a legitimate transaction where the merchant uses a payments processor whose name gets printed on your statement instead of the brand you actually recognize. The word Arus in a charge descriptor is the part that throws people off. In practice, it usually points to one of three things. It could be the actual name of the merchant. It could be a trade name or doing-business-as version of a company. Or it could be the name of the payment gateway or acquiring bank that processed the transaction. Banks and card networks display whatever the merchant submitted, so you often get a descriptor that looks like gibberish even when the purchase was totally normal. The simplest way to narrow this down is to pull the full transaction details from your Chime app first. Go to your Activity tab, find the line item in question, and open it. The details view usually shows the merchant category code, the exact date and time, the amount, and sometimes a slightly more complete merchant name than what appears on the main card feed. If the transaction happened recently, the full name will often be visible in the expanded view. If it was months ago, you may only see the short descriptor, and then the next steps matter more.
I spent some time digging through a similar charge on my own account last year. It showed up as an unfamiliar merchant tied to a local address, and the amount was right for something I had bought, but I could not place it at first. I checked my email for receipts, compared dates, and matched the amount to an online purchase from a smaller retailer. The retailer used a payment processor that happened to bill under that name. Once I found the receipt, the mystery disappeared in about ten minutes. That is usually how these work out. You just need to line up the charge with a purchase you remember making.
Common Sources Of Charges Like This
There are a handful of merchant types that regularly show up with descriptors that look like this. Online subscription services are a big one. Many of them bill through a third-party payments company, and the descriptor on your card reflects the payments company rather than the service you subscribed to. E-commerce sellers on marketplaces do the same thing. Digital goods, software licenses, membership renewals, and streaming services all fall into this bucket. These charges often recur monthly, which makes them easier to track if you set a reminder around when you first signed up for anything. Another common source is a merchant that uses a POS or card-present system where the store name gets routed through a regional or national payment processor. The descriptor then carries the processor's name instead of the local shop. If you shopped at a small retailer, a contractor, or a service provider that took card payments, the charge might not match what you expected because the processing layer inserts its own labeling. That does not mean the charge is wrong. It just means the statement is showing the processing identifier. There is also the possibility that the charge is simply a misread memory. You might have forgotten about a small purchase, a pending authorization, or a hold that finally posted. Pending charges can show up and then drop off without much fanfare. Holds from gas stations, hotels, car rentals, and restaurant tips often land as separate line items before settling into the final amount. If the charge is small and recent, give it a day or two and see whether it converts to a settled transaction with a cleaner descriptor.
Get the Full Details
How To Verify Whether The Charge Is Yours
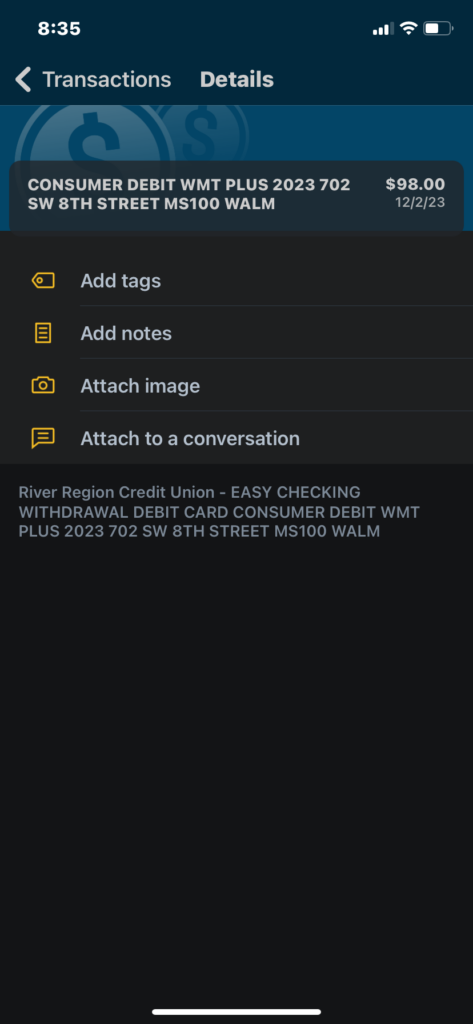
Start with the basics. Pull up your email and search for receipts around the date of the charge. Include the amount and the merchant's approximate name in the search. You can also check your text messages if the merchant sent confirmation there. Most legitimate purchases leave a paper trail, even if it is just an automated receipt. Match the receipt amount to the charge amount exactly. Even a penny difference can point you toward a different transaction or a split payment. Next, check your bank statements outside of Chime. If you linked any other accounts, such as a savings account or a secondary debit card, the charge might appear there too. Sometimes a merchant runs the transaction twice or sends it through a different processing path depending on how you entered your payment info. I once saw a charge appear on two cards because the merchant's system had saved two payment methods and ran both during a single checkout flow. That is unusual but not impossible, and it is worth noting if you spot duplicates. If you still cannot identify the charge, contact the merchant directly. You need the actual business name, not just the descriptor. Look up the address associated with the charge. A quick search for the street address and nearby businesses often surfaces the company name. Call them or send an inquiry with the transaction date, amount, and the last four digits of the card used. Legitimate merchants can look up the charge in their own system and tell you what it was for. This step usually resolves the issue faster than waiting for Chime to investigate on your behalf.
When To Escalate To Chime
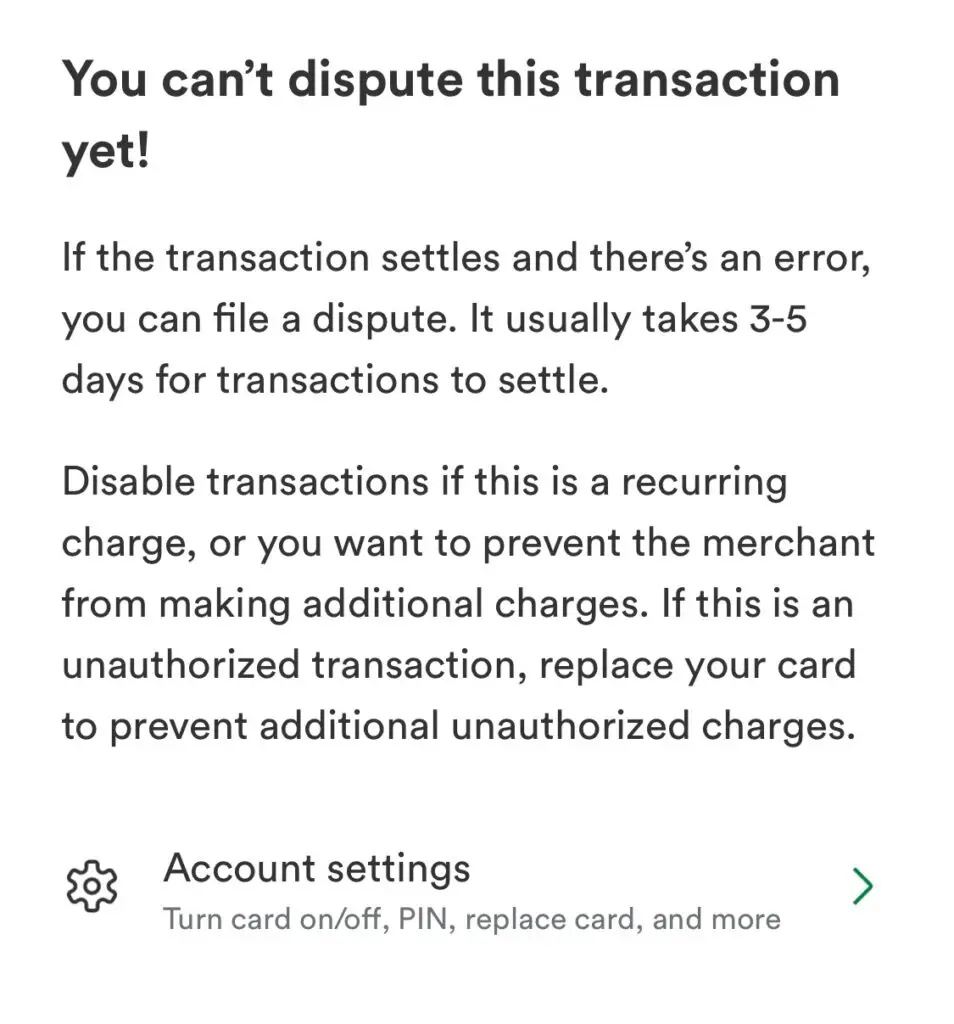
If the merchant cannot help or refuses to provide details, the next step is to dispute the charge through Chime. You can do this inside the app by selecting the transaction and choosing the dispute option. Chime will ask you to confirm that you do not recognize the charge or that the charge is incorrect. They will typically freeze the disputed amount while they investigate. That process usually takes between five and fourteen business days, though it can extend to thirty days in some cases. During that window, you cannot use the frozen funds for other transactions unless the dispute is resolved in your favor. Be aware that filing a dispute is not a shortcut for forgetting what you bought. If the charge turns out to be legitimate after all, the dispute will be reversed and the transaction will post normally. Repeated false disputes can flag your account and make future disputes harder to process. Use the dispute process when you genuinely do not recognize the charge or when the merchant is uncooperative and you suspect fraud. Do not use it as a way to avoid paying for something you simply forgot about. There are cases where a charge is clearly fraudulent. If you see a duplicate charge for the same amount, a charge at a completely unrelated merchant, or a charge that appeared after you reported your card lost or stolen, treat it as fraud and report it immediately. Chime has dedicated fraud support for these situations, and they can move faster than the standard dispute timeline. They may also issue a temporary replacement card and block further activity on the compromised number while they sort out the investigation.
Pitfalls That Make Identification Harder
One frequent problem is that merchants use different descriptors across different transactions. The same company might bill through three different payment processors depending on the product line, the region, or the sales channel. That means you cannot rely on a single known name and expect consistency. If you bought from a retailer once and saw one descriptor, a second purchase from the same retailer might show up under an entirely different name. The amounts and dates still have to line up, but the label can shift. Another issue is that some charges get batched or grouped together. A merchant might process several small transactions into a single daily settlement, and the descriptor then reflects the aggregate rather than each individual sale. If you made multiple purchases over a few hours, you might see one large charge instead of several small ones. This makes it harder to match a single charge to a single purchase. Check your purchase history around the time of the charge to see whether the totals add up. A third pitfall is that some recurring charges are hard to cancel. Subscription services sometimes make it difficult to find the cancellation link or require you to call a support number during business hours. If you stop paying but do not formally cancel, the subscription may keep rolling and the descriptor may keep appearing. Keep records of cancellation confirmations. Screenshots, emails, and reference numbers all help if you ever need to dispute a charge that should have stopped.
Practical Tips For Avoiding Future Confusion
The most effective strategy is to keep a running list of your recurring charges. Write down the service name, the billing amount, the billing date, and the descriptor you expect to see on your statement. Update it whenever you add or cancel a subscription. This takes about five minutes a month and prevents a lot of stress later. When a charge shows up that you do not recognize, you can compare it against your list and quickly spot whether it matches an expected pattern or if something is off. Another useful step is to use virtual card numbers if your bank offers them. Chime does not currently provide virtual card numbers for every transaction, but some other banks do. Virtual cards let you assign a unique card number to each merchant or purchase, so even if a descriptor looks strange, you can trace it back to the specific card you used. This is especially helpful for online shopping where you do not know whether the merchant will resubmit the charge or share it with a third-party processor. You can also set up transaction alerts in your Chime app. Enable notifications for every purchase over a certain amount, or for any transaction that occurs outside your usual spending patterns. Alerts give you immediate visibility into new charges, which makes it easier to catch errors or unauthorized activity before they snowball. The alerts themselves do not prevent fraud, but they do speed up your response time significantly.
What To Do If The Charge Stays Unidentified
If you have checked your receipts, contacted the merchant, reviewed your other accounts, and still cannot figure out what the charge is, the safest path is to treat it as potentially fraudulent until proven otherwise. Dispute the charge with Chime, close the affected card if you suspect a compromise, and monitor your account for additional suspicious activity. Change your Chime password and enable two-factor authentication if you have not already done so. These steps do not guarantee you will recover the money, but they reduce the chance that the problem spreads. Keep a record of every step you take. Save emails from the merchant, screenshots of your dispute submission, and notes from phone calls with support representatives. If the dispute drags on or gets denied, having a clear timeline helps you escalate the issue or file a complaint with the relevant consumer protection agency. Most disputes resolve within the standard window, but having documentation makes the process smoother if you need to push back. At the end of the day, a charge like 702 S Bentonville Arus Charge On Chime Card is rarely a crisis. It is usually a normal merchant transaction that just needs to be matched to a purchase you remember making. The key is to follow a simple sequence: review the details, check your receipts, contact the merchant, and dispute only if something looks wrong. That approach handles the vast majority of these situations without requiring a lot of time or effort.