Buying Property In Germany Is Not Like Anywhere Else
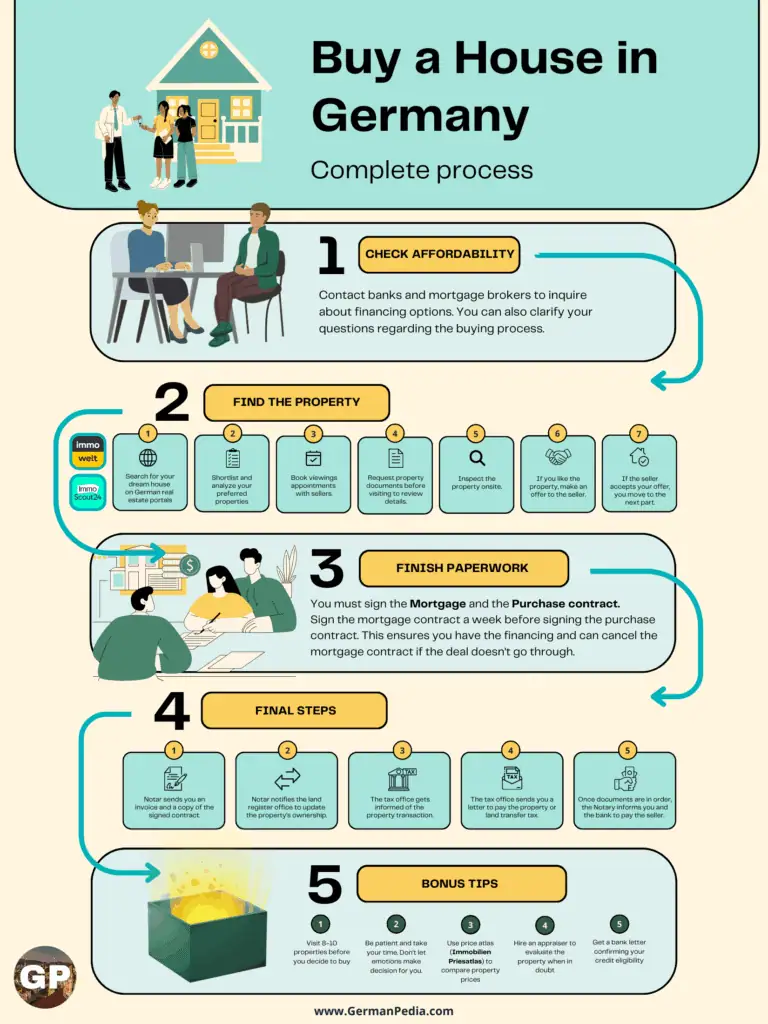
The process is slower, more paperwork-heavy, and considerably less forgiving than most first-time buyers expect. You cannot simply walk into a bank, show your pay stub, and walk out with a mortgage commitment letter. It does not work that way. The German system requires documentation that will make your head spin if you are coming from a market like the US or UK. Before we get into the actual steps, here is the thing nobody tells you upfront: the down payment requirement in Germany is not just about your savings. Banks typically want a minimum of 20 percent of the purchase price covered by your own funds, and they look at where that money came from. If you received a gift from your parents, that needs to be documented in a notarized declaration, and the bank may still apply a higher interest rate because gifted equity counts differently than earned equity. I learned this the hard way in 2019 when I was helping a colleague purchase a property in Munich. Her family had transferred 80,000 euros to her account six months before applying, and the bank initially refused to count it because the source documentation was incomplete. We ended up getting a notary to confirm the gift declaration and providing three months of bank statements showing the money sitting idle before the mortgage application. The whole delay cost roughly six weeks and almost killed the deal. The first step is getting a Vorbescheinigung, a preliminary mortgage confirmation, from your bank. This is not the same as a final commitment. It is a document that tells sellers and real estate agents you are serious and financially qualified. Without it, your offer will likely be ignored in competitive markets. German banks will run a Schufa check, request your last three years of tax returns, your most recent pay slips, and an employment contract that shows you are not on a fixed term that ends within the next twelve months. If you are self-employed, expect them to ask for your business tax assessments for the past three years as well. Some lenders also require proof that you have an emergency reserve fund equal to roughly six months of living expenses separate from your down payment.
Once you have the Vorbescheinigung, you start viewing properties. The German market operates differently here. Most listings go through real estate agents, but there is a strong culture of informal selling, particularly for family homes. You will see "Privatverkauf" in listings, which means the owner is selling directly without an agent. This can save you the provision fee, known as the Maklerprovision, which typically runs between 3.57 and 7.14 percent of the purchase price plus VAT depending on whether the buyer or seller pays it. Since 2020, the law changed so that the buyer and seller split the provision, but in practice the split still varies by negotiation. I once found a property in Stuttgart listed as privatverkauf that turned out to be a inherited apartment where the seller had no idea about the Grundschuld and the existing land charge that needed to be cleared before transfer. That added another month of legal work and about 2,500 euros in notary and land registry fees that would have been caught earlier by a proper due diligence process. When you find a property, you will submit an offer called a Kaufangebot. This is usually done through the agent or directly to the seller if it is a private sale. Your offer should include a proof of funds letter or your Vorbescheinigung attached. The seller has no obligation to accept it, and in hot markets you may face bidding situations. Unlike in some countries, German sellers rarely entertain multiple rounds of public bidding. They usually pick one offer and move forward. Your offer should include a subject to financing clause, or Außerhalb Vorbehalt, which protects you if the bank does not approve the mortgage. Without this clause, you could lose your deposit if financing falls through. The financing stage is where most people hit problems. German mortgage rates are typically offered for a fixed period, commonly ten years, after which the interest rate is renegotiated. This is called a Zinsbindung. A ten-year fix is the standard and it provides stability, but it also means you are locked in. If rates drop significantly during that decade, you are stuck. Some borrowers opt for a shorter five-year lock or even a variable rate, but that introduces risk. I remember working with a client who chose a variable rate in 2021 when rates were near zero. By 2023, her monthly payments had increased by roughly 40 percent, and she was forced to refinance at a higher principal balance because the property value had not kept pace with the rate hike. It was a cautionary example of why the fixed-term structure exists and why you should model your budget at the higher end of what you might pay over the full lock period.
After your offer is accepted, the next phase is the notary appointment. In Germany, you cannot buy property without a notary. The sales contract, the Kaufvertrag, must be executed before a certified notary, and both parties must be present or represented by a proxy with a notarized power of attorney. The notary reads the contract aloud, confirms identities, and ensures both parties understand the terms. This process takes about twenty to forty minutes. The notary fee is regulated by law and depends on the purchase price, typically around 1.5 to 2 percent of the property value. The land registry fee, Grundbuchgebühr, adds another 0.5 percent or so. These costs are non-negotiable and apply regardless of whether you use an agent or buy privately. One counter-intuitive detail that trips up many foreigners: the purchase price you agree on is not always the price that appears in the contract. There is a concept called the Grundsteuerwert, the property tax value, which the tax office uses to calculate ongoing property taxes. If the agreed price is significantly below market value, the tax office can reassess and issue a higher tax bill. This is known as a Steuerhindernis. I encountered this when helping a buyer who wanted to structure the deal with a lower purchase price and a separate side agreement for renovation work. The tax office flagged it, the deal stalled for three months, and the buyer ended up paying a higher Grundsteuer for years because the assessed value was adjusted upward. The workaround was to restructure the contract with a realistic purchase price from the start and document the renovation separately through a standard service contract. Another often-overlooked factor is the Bodenrente, or ground rent. Many older properties in Germany, especially in cities like Berlin and Hamburg, sit on land that is still owned by the state or a municipality. The buyer must pay an annual ground rent to the landowner, which can range from a few hundred euros to several thousand depending on the location and size of the plot. This is not optional. It appears in the Grundbuch and continues indefinitely. I saw a buyer in Dresden who did not check this and was surprised to find he owed 1,800 euros annually to the city after closing. The ground rent reduces the effective return on the property and should be factored into your affordability calculation from day one.
Get the Full Details
Energy efficiency is another area where assumptions can cost you. German buildings are classified under the Energieausweis, an energy certificate that rates the property from H to A plus. If you are buying an older building, the Energieausweis will tell you the estimated annual heating cost. A poorly insulated 1970s apartment block can easily have heating costs above 200 euros per square meter per year. Renovating to modern standards can cut that by half, but the upfront cost is significant. I once reviewed a property in Leipzig with a G-rated Energieausweis. The seller had quoted a modest renovation budget, but the actual cost to bring it to a C rating came to roughly 65,000 euros, including a new heating system, insulation, and window replacements. The buyer walked away, and the property sat on the market for eight more months before being sold to someone willing to take on the renovation. The lesson is simple: read the Energieausweis before you fall in love with a property. It is the single best predictor of hidden future costs. If you are a foreign buyer, there are additional considerations. Non-EU citizens need to obtain approval from the local Bauamt or the relevant state authority before purchasing residential property, though this rule has been relaxed in some states since 2021. Even within the EU, you will need a German tax identification number, a Steueridentifikationsnummer, and a local bank account to complete the transaction. Some German banks will not open an account for non-residents without a residence permit, so this can be a bottleneck. I have seen deals collapse because the buyer could not open an account in time for the notary appointment. The fix is to start the banking process as soon as you know you are serious about purchasing, ideally before you even begin viewing properties. The final step after the notary signs the contract is the Eintragung im Grundbuch, the entry into the land registry. This is where the transfer of ownership becomes legally effective. The notary submits the contract to the Grundbuchamt, and the process usually takes between two and six weeks. During this time, the property is technically still owned by the seller, but you have a binding contract. You should have taken out home insurance before the notary appointment because once the contract is signed, you bear the risk of damage to the property even if you do not yet hold the title. Failure to insure during this gap has caused real losses for buyers who assumed coverage started at signing rather than at the moment of legal transfer.
Total closing costs in Germany typically run between 10 and 15 percent of the purchase price. This includes the notary fee, land registry fee, property transfer tax called Grunderwerbsteuer, and potentially the agent provision. For a 400,000 euro property, you should budget an additional 40,000 to 60,000 euros beyond the purchase price. This is a hard fact that foreign buyers frequently underestimate because their home markets often have closing costs below 3 percent. The German numbers are what they are. There is no workaround for the regulated fees, and the agent provision is still negotiable in many cases, so discussing the split with your agent before signing the purchase agreement can save you several thousand euros. If you are evaluating whether buying makes sense compared to renting, the math changes depending on the city and the length of your stay. In Berlin or Munich, the rental yield on purchased property is often below 3 percent, while monthly rents are high. Buying only makes financial sense if you plan to stay for ten years or more and are comfortable with the illiquidity of the asset. For shorter horizons, renting is usually the more flexible and sometimes cheaper option once you factor in maintenance, property tax, and the opportunity cost of your down payment. I have run these calculations for clients in Frankfurt, Cologne, and Düsseldorf, and the pattern holds consistently. The German housing market rewards long-term holders and penalizes short-term speculators.