.jpg)
International Student Loans In Canada: What Actually Exists
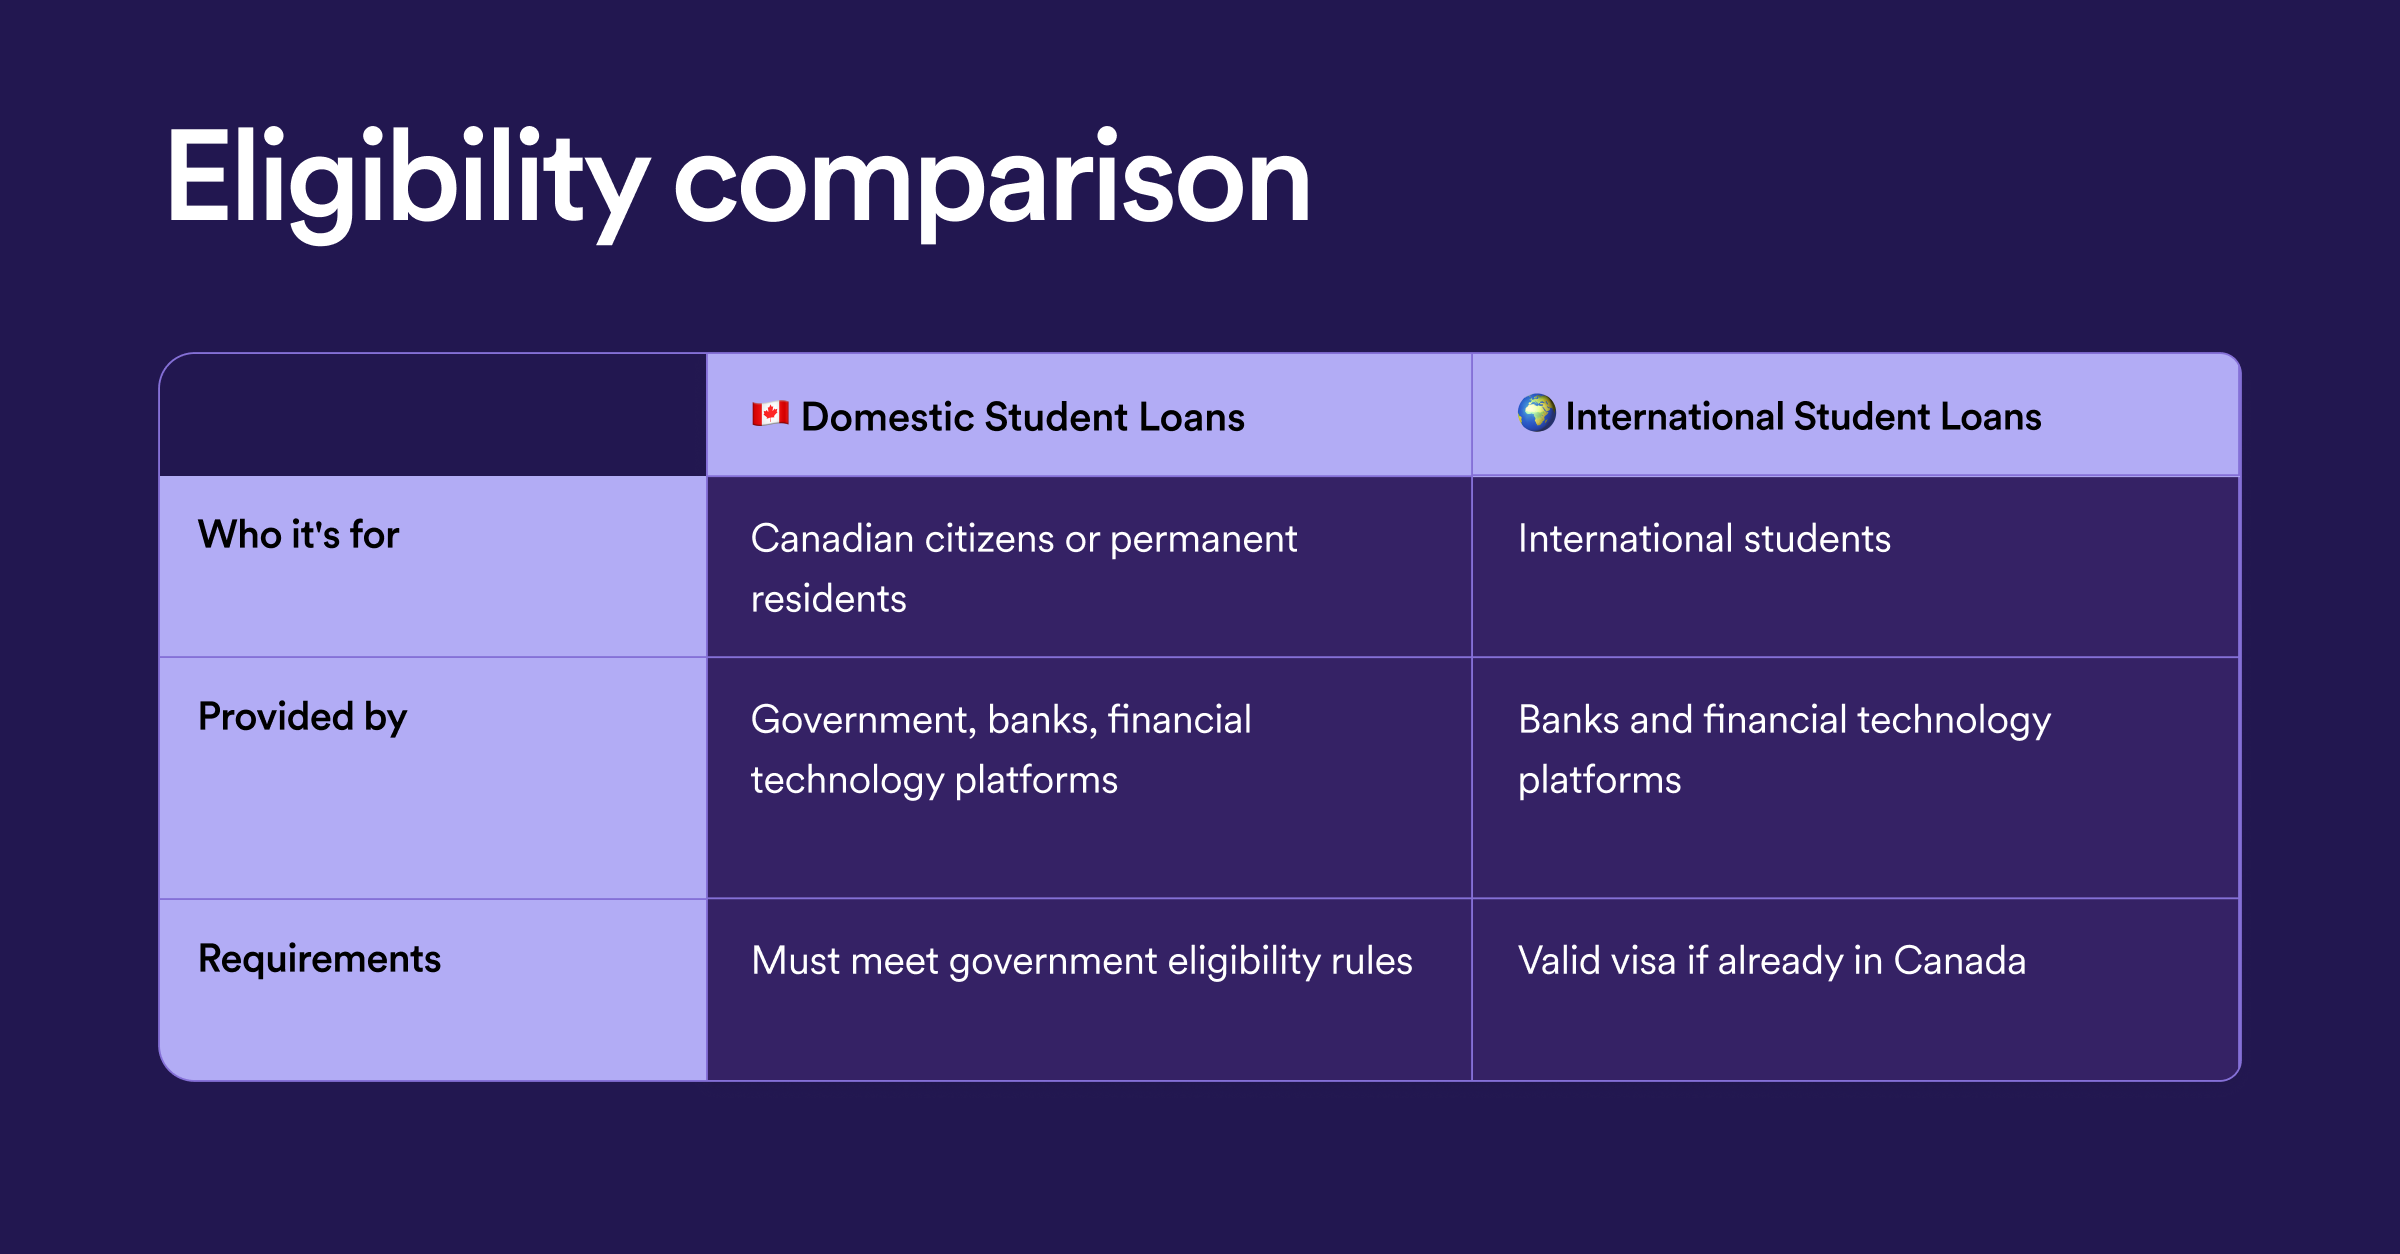
There is no federal government loan program for international students in Canada. That is the first thing to understand before reading anything else on this topic. The Canada Student Loans Program does not cover non-permanent residents. This means anyone applying as an international student has to navigate a much narrower set of options than domestic students, and the process is messier because of it. I spent three years helping people figure this out, and the pattern is always the same: confusion, wasted applications, and then a solution that turns out to be simpler than expected. The reality is that international students have access to two main types of financing. The first is a private loan from a Canadian bank or credit union that requires a Canadian creditworthy co-signer. The second is an international student loan from a specialized lender that does not require a co-signer but charges higher interest rates and has stricter eligibility criteria. Both exist. Both work under certain conditions. Neither is ideal.
Unlocking The Door To Higher Education A Comprehensive Guide To International Student Loans In Canada
The process starts with knowing which schools are eligible. Most Canadian lenders only fund students enrolled at designated learning institutions approved by Immigration, Refugees and Citizenship Canada. That list includes nearly every public university and many private colleges, but it excludes language schools, certificate programs at unapproved institutions, and a number of vocational training centers. Before you apply for anything, confirm your program and school are on the DLI list. It takes five minutes on the IRCC website and saves you from having an application rejected weeks later. I once had a client who was completely turned around because her program was delivered through a partnership between two institutions. One partner was on the DLI list, the other was not. The lender initially flagged the entire enrollment as ineligible. We resolved it by providing the official partnership agreement from both schools, showing that the portion of the program she was actually taking was taught exclusively at the designated institution. The loan went through after an additional two weeks of documentation. Never assume your enrollment is automatically eligible just because the university is well-known.
How The Co-Signer Loan Route Actually Works
A co-signer loan is the most common path. You find a Canadian bank or credit union that offers international student loans, and you bring someone with established Canadian credit who agrees to be equally responsible for repayment. This person is typically a parent, sibling, or close family member who is a Canadian citizen or permanent resident. Without a qualifying co-signer, most major banks will not touch the application. The amounts you can borrow vary by lender. Scotiabank, for example, has historically offered up to CAD 70,000 for international students at partner institutions, covering tuition, books, and living expenses. TD Bank and CIBC have similar products with comparable ranges. The interest rates are usually variable and tied to the lender's prime rate plus a spread. I have seen rates in the 8 to 12 percent range over the past few years, depending on the borrower's profile and the co-signer's credit score. Here is something most guides do not mention clearly: the co-signer's debt-to-income ratio matters more than their credit score alone. A lender will calculate whether the co-signer can already afford the loan alongside their existing obligations. If they have a mortgage, car payments, and credit card balances that push their DTI above 43 percent, the application can be denied even with an excellent credit score. This is a hard limit at most banks. You cannot negotiate around it.
Get the Full Details
Repayment terms are also worth understanding before you sign. Most co-signer loans require interest-only payments while you are still studying, with full repayment beginning six months after you graduate or stop being a full-time student. Some lenders offer a grace period of up to 12 months. If you plan to work in Canada after graduation on a post-graduation work permit, you need to know exactly when payments start and what your monthly obligation will be. An extra CAD 600 per month in payments is not unusual for a CAD 40,000 loan at current rates.
The No-Co-Signer Alternative And Its Hidden Costs
Specialized lenders like MPOWER Financing, Prodigy Finance, and Leap Financial offer loans to international students without requiring a Canadian co-signer. These are real products and they do fund students. The trade-off is cost. Interest rates typically run 10 to 14 percent, sometimes higher. Some lenders charge origination fees between 3 and 5 percent of the loan amount. On a CAD 50,000 loan, a 4 percent fee is CAD 2,000 taken out before you see any of it. Another detail people overlook is the repayment structure. These lenders often require you to begin making payments while you are still enrolled, even if the amount is small. MPOWER, for instance, lets you defer full payments but will expect partial interest payments during study. Prodigy Finance calculates your repayment based on your future earning potential in your home country after graduation, not your Canadian income. This matters because if you cannot return to your home country's job market, the repayment schedule does not adjust. I worked with a student from Nigeria who took a no-co-signer loan for an MBA in Toronto. She assumed she would return to Lagos after graduation and repay based on her expected salary there. The job market shifted, she stayed in Canada on a work permit, and her repayment calculations were based on a income scenario that never materialized. The lender did not accommodate this change. She ended up refinancing through a different product once she had built Canadian credit, but the damage from the higher-rate loan was already done. Two years of payments at a higher rate cost her approximately CAD 4,200 more than she would have paid with a standard co-signer loan.
What Happens When Your Funding Does Not Cover Everything
Most international student loans do not cover the full cost of attendance. Tuition alone at a Canadian university for an international student can range from CAD 20,000 to CAD 55,000 per year depending on the program. Engineering and business tend to be at the higher end. Living costs in cities like Toronto and Vancouver add another CAD 15,000 to CAD 20,000 annually. A loan that covers 80 percent of tuition still leaves a significant gap. Students in this situation often combine a co-signer loan from one bank with a smaller no-co-signer loan from a specialized lender to fill the difference. This is common and perfectly legal. It also means managing two separate repayment schedules, two different interest rates, and two different sets of customer service lines. Before you take this route, write down the exact terms of each loan side by side. The administrative overhead is manageable if you stay organized, but it becomes overwhelming quickly. Another option that rarely gets discussed is a line of credit secured against assets in your home country. Some Canadian banks will extend credit to international students if there is tangible collateral, such as a property or investment account, even without a co-signer. The loan amount is typically capped at 70 to 80 percent of the collateral value. The interest rate is usually lower than a standard unsecured international student loan. This only works if you or your family have significant assets, but it is an underutilized path for students who qualify.
Documents You Will Need And Where People Get Stuck
The document checklist is fairly standard but the execution is where problems arise. You will need your acceptance letter from the designated learning institution, proof of enrollment or registration, a detailed cost breakdown from the school, your passport and study permit or proof of application for one, and financial statements for any co-signer. If you are applying for a no-co-signer loan, you will also need transcripts and sometimes a statement of purpose explaining your academic and career trajectory. The cost breakdown from the school is critical. Lenders want to see exactly how much they can disburse. They will only fund up to the documented cost of attendance, and they disburse directly to the school for tuition and to you for living expenses. If your school's cost estimate is outdated or incomplete, the lender may fund less than you expected. I have seen this happen when a university revised its fee structure mid-year and the lender was still using the previous year's figures. Request an updated cost breakdown in writing before you submit your loan application. One specific problem I dealt with involved a student whose study permit was conditional. The permit was issued but required him to maintain a minimum course load and achieve satisfactory academic standing. The lender considered the permit conditional and refused to fund the loan until he provided a letter from the university confirming that his enrollment was full and unconditional for the duration of the program. The university issued the letter within a week, and the loan proceeded. Always ensure your study permit has no unusual conditions before applying.
Timing And The Application Window
Applications should be submitted at least eight to twelve weeks before your program starts. Banks move slower than you expect when it involves an international applicant, even with a co-signer. The credit check on the co-signer, the verification of enrollment, the assessment of the loan amount against your cost of attendance—each step introduces delays. If you are relying on a specialized no-co-signer lender, the process is faster, usually three to six weeks, but not always. There is also a timing issue with currency. If your family is sending money from abroad to support your studies or to help with loan payments, exchange rate fluctuations can erase a significant portion of your funding. A CAD 5,000 payment might require USD 3,800 in January and USD 4,100 in June due to exchange rate movement. This is not a loan problem but it is a financing problem that affects your ability to meet obligations. Open a foreign currency account if you are receiving funds in a different currency, and time your conversions strategically.
Common Pitfalls And What To Avoid
The biggest mistake I see is applying to multiple lenders simultaneously without understanding the impact on your co-signer's credit. Each hard inquiry lowers the co-signer's credit score slightly. Multiple applications in a short window can compound this effect and push the co-signer's DTI calculation into a less favorable range. Apply to one lender, get a decision, and then move to the next if necessary. Do not cast a wide net across five different banks in the same week. Another pitfall is accepting the first loan offer you receive without comparing the total cost. A loan with a lower interest rate but a higher origination fee can cost more over the life of the loan than a slightly higher-rate loan with no fees. Calculate the total amount you will repay, including all fees, before committing. A simple spreadsheet comparing monthly payments, total interest, and total fees across your options is sufficient. Finally, do not ignore the tax implications. Interest paid on student loans is generally not tax-deductible for international students in Canada, even if you are working part-time. The Canada Revenue Agency allows a student loan interest deduction, but you must be a resident of Canada for tax purposes to claim it. Most international students on study permits are not considered residents for tax purposes in their first year, and even after becoming resident, the rules are complex. Do not assume you can write off your loan interest. Consult a tax professional who understands international student status before making any assumptions.

A Practical Example
Sarah, an international student from India pursuing a master's in data science at the University of Waterloo, needed CAD 62,000 over two years. She had an aunt who was a Canadian permanent resident with good credit. She applied to Scotiabank's international student loan program with her aunt as co-signer. The bank approved CAD 56,000 at 8.45 percent variable interest, with interest-only payments during study and full repayment beginning seven months after graduation. The remaining CAD 6,000 came from a no-co-signer loan with MPOWER at 11.2 percent, covering books and living expenses not included in the bank's funding calculation. Her total monthly payment after graduation, spread over ten years, was approximately CAD 780 for the Scotiabank loan and CAD 145 for the MPOWER loan. Combined, that was CAD 925 per month. She had negotiated a six-month grace period on the MPOWER loan, so her first combined payment did not begin until one year after graduation. Sarah monitored the variable rate closely and refinanced the MPOWER portion into the Scotiabank loan once she had established Canadian credit and her rates dropped. The refinancing saved her approximately CAD 1,800 in interest over the remaining term.
When None Of This Works
Sometimes you cannot get a loan. The co-signer does not qualify. The no-co-signer lenders reject the application due to the country of origin or the field of study. The collateral option is not available. In these cases, the practical alternatives are scholarships, bursaries, and work-permit income. International students on a study permit can work up to 20 hours per week off-campus during regular sessions and full-time during scheduled breaks. Minimum wage in Ontario is CAD 16.55 per hour as of 2025. Twenty hours per week for 30 weeks during the academic year is approximately CAD 9,930 annually. This does not cover tuition, but it reduces the amount you need to borrow. Several universities have emergency funding pools specifically for international students who face unexpected financial shortfalls. These are not well-publicized. Contact your university's international student office and ask directly. Some departments also have research assistant positions that pay above minimum wage and do not count against your off-campus work limit because they are considered on-campus employment. These positions are competitive but they are real and they do not require a work permit amendment. If you ultimately cannot secure adequate funding, deferring your admission for one year is sometimes the most rational choice. Use that year to work, save money, and reapply with a stronger financial profile. A deferred admission is not a failure. It is a strategy that prevents you from taking on debt you cannot sustain. I have seen students who deferred, worked for twelve months, saved CAD 15,000, and then returned with a significantly smaller loan requirement and a much more manageable repayment plan.
Bottom Line
International student loans in Canada are available but fragmented. The co-signer route from a major bank is the most cost-effective option and should be your first attempt. The no-co-signer specialty lenders are a viable backup when a co-signer is not available, but they carry higher costs and less flexible terms. Combine them only when necessary and track every detail. Check your school's DLI status before applying. Verify your study permit has no conditional clauses. Compare total cost, not just interest rates. And if nothing works, defer and rebuild rather than overborrow. The loan you take now will shape your financial trajectory for a decade or more.