A Practical Look at How Home Depot Handles Payments
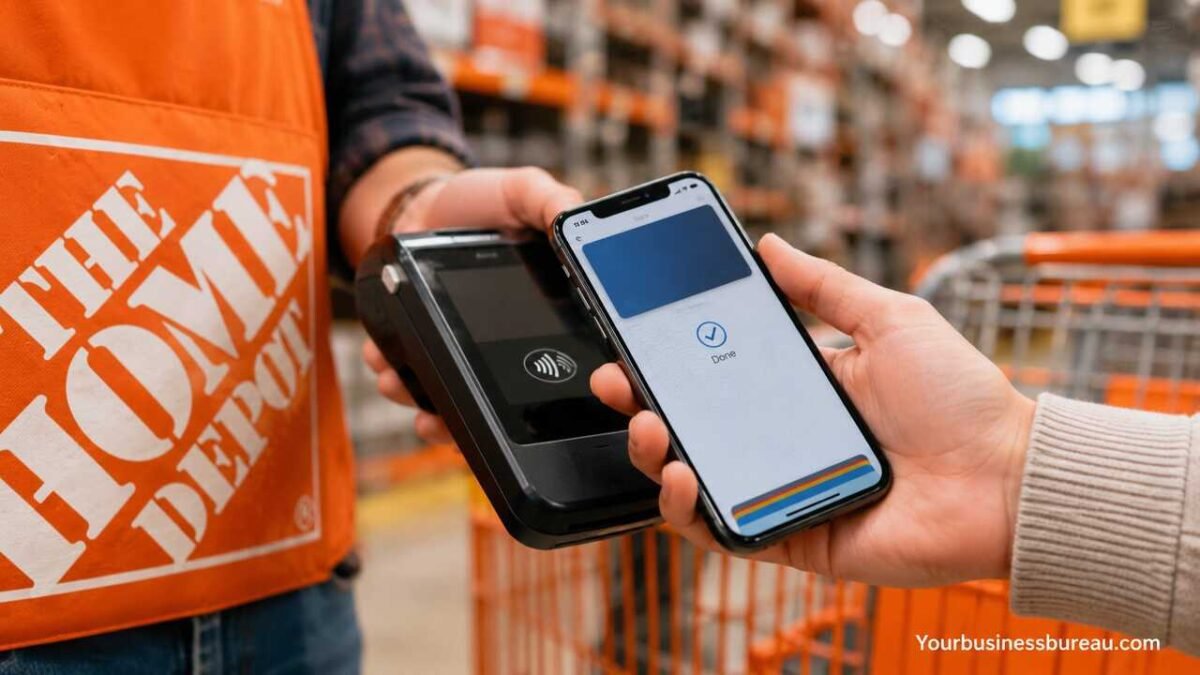
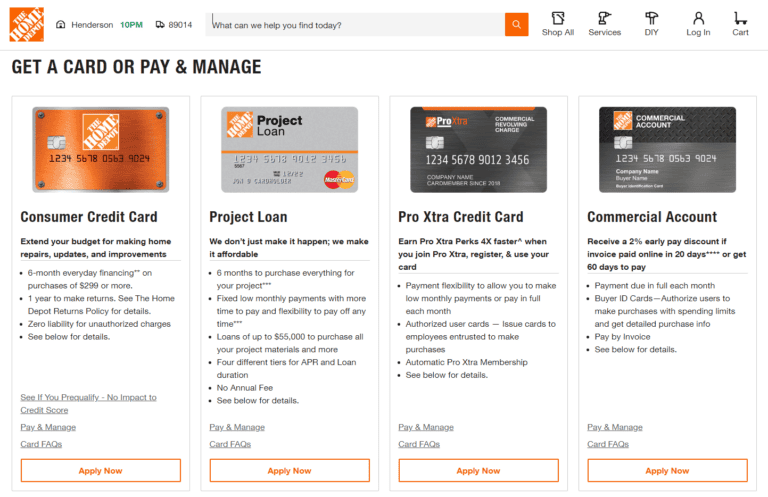
I spent three hours on a Saturday in 2023 standing in line at my local Home Depot while a customer behind me tried to use a mobile wallet that just wouldn't connect. The card reader blinked red every single time. Eventually we paid with a physical card and moved on. That moment showed me something about how payment processing actually works in a retail environment like that. Home Depot offers several payment channels. There is the standard point-of-sale terminal that accepts chip cards, contactless payments via NFC, Apple Pay, Google Pay, and Samsung Pay. They also have their own branded credit cards — the Consumer Card, the Commercial Card, and the Pro Xtra Card — each running through separate underwriting and reward structures. Gift cards exist in both physical and digital form, and the Pro Xtra program includes a business-oriented payment tracking system that integrates with QuickBooks for qualifying accounts. The key distinction most people miss is that Pro Xtra members get a dedicated line of credit, not just loyalty points. That means when you are checking out with a team of laborers and someone forgets their payment method, the Pro account can cover materials up to the assigned credit limit and then reconcile everything weekly through invoice export. It saves you from trying to split twelve transactions across six different cards. That alone makes it worth the two-minute signup at the service desk.
I ran into a real issue once where a commercial account holder tried to use Pro Xtra financing for a purchase over $2,500 at a store location that was not registered under their business entity. The terminal rejected the transaction even though their credit line had ample room. The workaround was to call the Pro support line during off-peak hours — after 10 AM on a weekday usually meant waiting forty minutes on hold — and have them temporarily authorize cross-location purchasing for that specific purchase order number. The representative needed the invoice breakdown and the shipping destination before approving it. Plan ahead if you are dealing with large equipment orders. One thing that is not widely understood: the HD Consumer Card only earns rewards on purchases made directly through Home Depot. If you buy a $400 drill from an independent tool repair shop that accepts Home Depot gift cards as a form of payment, you are not earning anything on that transaction because the merchant of record is the repair shop, not Home Depot. The gift card balance does reduce your out-of-pocket cost, but the rewards calculator will not count it. Contactless payments at Home Depot terminals have a relatively low timeout threshold. If you tap your phone or card and the reader does not respond within three seconds, the terminal resets the session rather than extending the wait. This happens more often in older store locations that have not been upgraded to the latest Verifone hardware. If your tap fails twice, remove the device and try chip insertion instead. It avoids the retry lag that adds up during busy periods.
Gift cards remain one of the most flexible options, but there is a limitation you should be aware of. Home Depot gift cards cannot be used to pay off your Home Depot credit card balance. Some people assume that reloading a gift card with purchase rewards is a way to chip away at debt, and it is not. The rewards are issued as statement credits, which operate on an entirely different ledger than gift card funds. For business buyers, the commercial card and Pro Xtra line serve different purposes. The commercial card handles standard credit terms with monthly statements and late fees that accrue at the standard APR. Pro Xtra financing is structured around project-based billing with optional net-30 or net-60 terms for approved contractors. The qualification bar is higher, and they run a hard credit check during enrollment. If you have a low personal credit score but your business has established trade references, Pro Xtra may still approve you based on business metrics rather than personal credit alone. That is a significant advantage for newer contracting operations. Security-wise, Home Depot uses tokenization for all contactless and mobile wallet transactions. Your actual card number never reaches the terminal. The token is specific to that device, so if someone clones the NFC signal from your phone at a crowded checkout, they receive an expired or deactivated token. This has been in place since the 2019 terminal upgrades across most locations. Older terminals in rural or underfunded stores may not have been updated, which is why chip insertion remains the more reliable fallback in some areas.
Get the Full Details
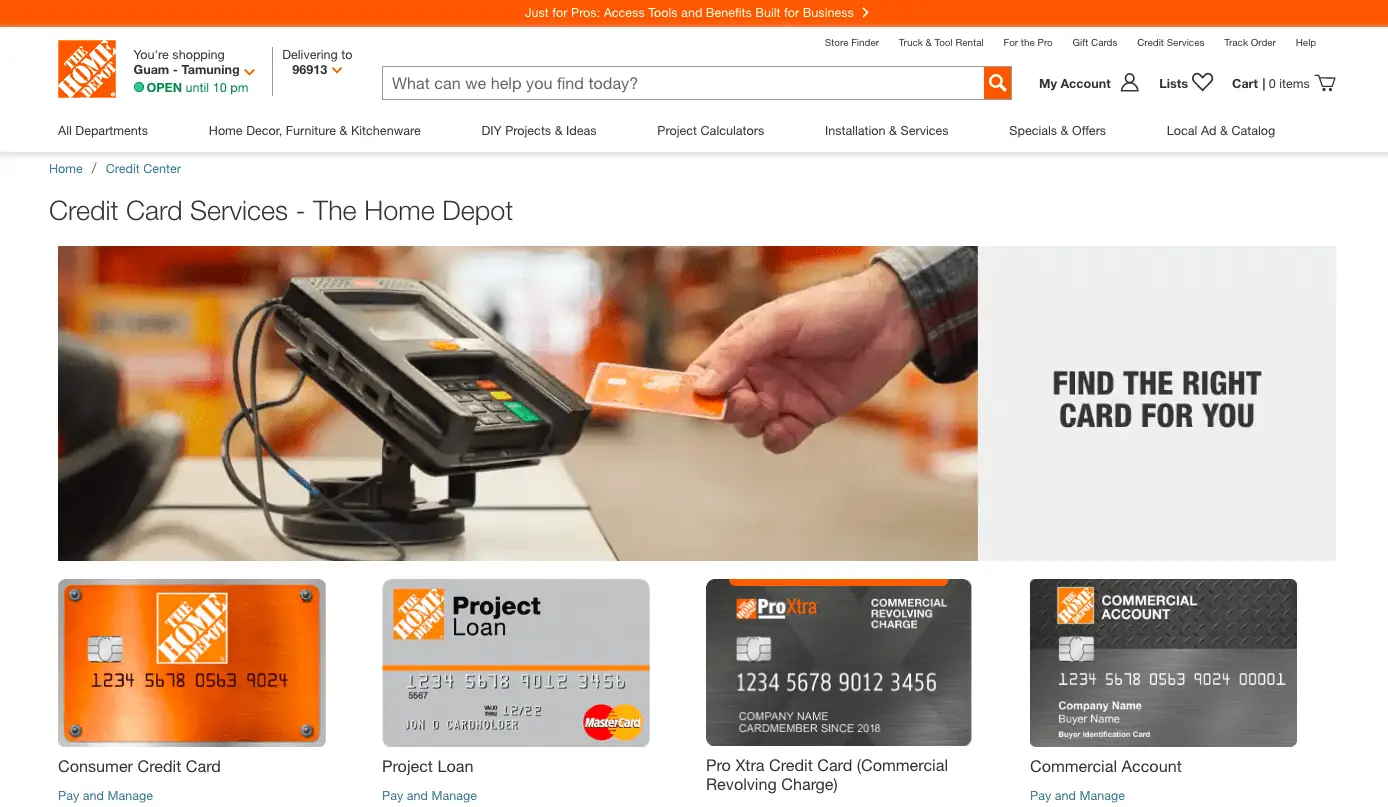
If you are buying materials for a single room renovation and your total stays under $500, the Consumer Card with its 5% discount on everyday purchases usually makes the most financial sense. If you are outfitting a full job site with lumber, fixtures, and power tools regularly, Pro Xtra pays for itself through the credit tracking and bulk invoicing. The app does handle receipt storage and project budgeting, which cuts down on end-of-month expense reconciliation from roughly an hour to maybe fifteen minutes. The one scenario where none of this helps is when you need to pay with cash and the register is short on bills. This sounds trivial, but it happens frequently during peak weekend hours. Home Depot registers do not dispense change from an automated drawer in the same way supermarkets do. If you hand over a $100 bill for a $73 purchase, the associate needs physical $20s and $5s in the till. When those run out, they may ask if you can provide exact change or complete the transaction with a card instead. Keeping smaller bills on hand during big trips eliminates that friction entirely. Home Depot also allows you to load multiple payment methods onto a single transaction through their website and in-store kiosk system. You can apply a gift card first, then charge the remainder to a credit card, and still earn rewards on the funded portion. The system processes gift card deductions before card charges automatically. This layered approach works for both online and in-person purchases, though the in-store process requires the associate to manually adjust the tender sequence if the system does not default correctly.

 "e-Procurement Options - The Home Depot Pro")