What Amazon Payments Europe SCA Actually Requires From Your Checkout Flow
Strong Customer Authentication is just two-factor authentication applied to payments, but the way it's implemented across Europe creates more friction than people expect. Amazon Payments handles this on behalf of merchants in most cases, but your integration still needs to account for the redirects, the challenge flows, and the failure states that come with it. I spent three weeks debugging a production issue where Scandinavian customers were hitting a wall at checkout. The problem wasn't SCA itself. It was that our fallback logic was incorrectly marking 3D Secure challenges as failed instead of allowing the customer to complete the identity verification step. Amazon's documentation doesn't spell this out clearly because it's really a merchant-side implementation problem. Once I traced the response codes back through the webhook notifications, the fix took about twenty minutes.
Unlocking Seamless Transactions What You Need To Know About Amazon Payments Europe Sca
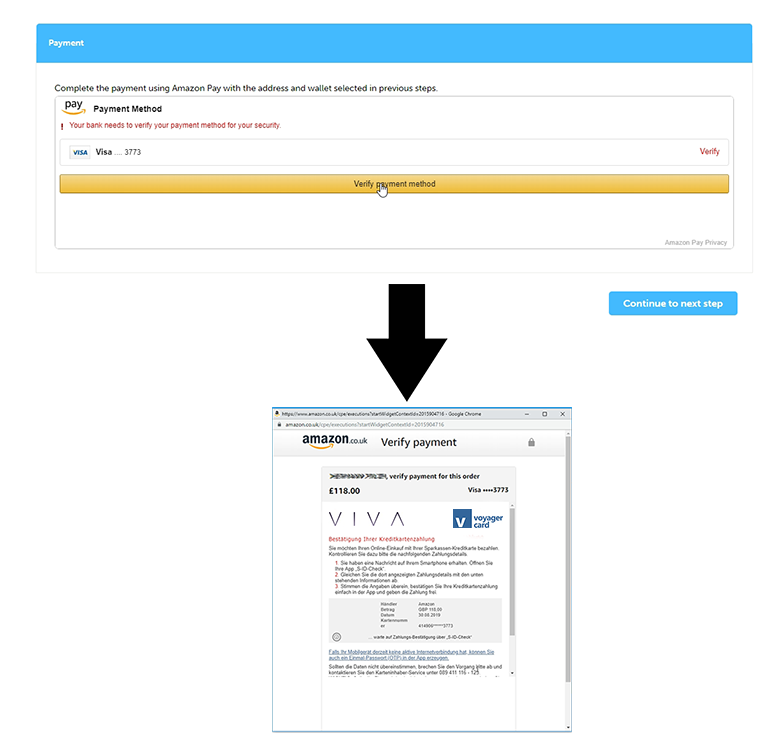
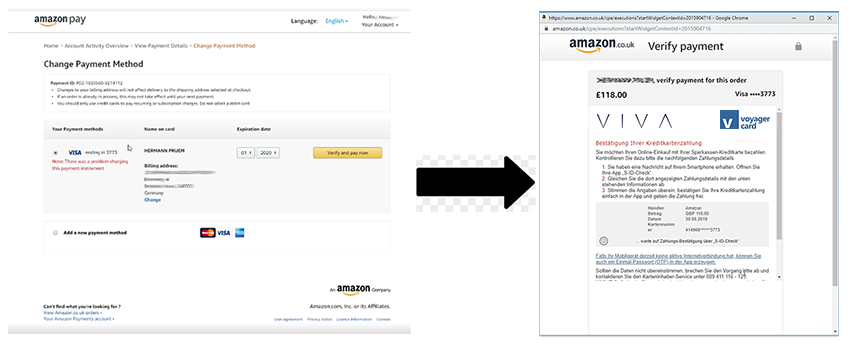
When you integrate Amazon Payments for European transactions, the flow works like this. Your customer checks out, Amazon evaluates whether SCA is required based on the transaction amount, the customer's bank, and the risk score they compute. If SCA triggers, Amazon redirects the customer to their bank's authentication page or sends a push notification depending on the issuer. The customer completes the verification, Amazon confirms the result, and your order proceeds. If authentication fails or times out, you get a specific error code back and need to handle it gracefully. The key detail most guides skip is that SCA doesn't apply uniformly. Transactions under thirty euros sometimes qualify for the low-value exemption, but only if your customer's bank hasn't opted out of it. Several major German banks have opted out. So a twenty-five euro purchase might still trigger authentication for a customer with Deutsche Bank but not for someone with a smaller cooperative bank. This means you can't build logic around a simple amount threshold. You have to accept that some transactions will challenge regardless of what you expect. Amazon Payments exposes the authentication result through their API responses and through webhook events. The response includes a status field that tells you whether the challenge completed successfully, was cancelled by the customer, or timed out. You should be listening for the webhook version of these events because the synchronous API call might return before the customer finishes the banking app verification. I learned this the hard way when a batch of orders showed as pending for hours because my system was polling the wrong endpoint.
Here's the practical setup process. First, make sure your Amazon Payments account is configured for the European marketplace and that your seller profile covers the countries you're selling to. Then, when you call the payment API, include the return URL that Amazon will redirect to after authentication completes. Make sure that URL is HTTPS and that it can handle both successful and failed authentication results. After that, set up webhook listeners for payment events. You'll need at least the payment-created, payment-succeeded, and payment-failed notifications to cover the normal flow and the edge cases. One thing that catches people off guard is the recurrent payment scenario. If a customer has saved their payment method with you through Amazon Payments, subsequent transactions might not trigger SCA because the bank already authenticated the original setup. But if there's a significant change in amount or a long gap between transactions, the bank can require re-authentication at any point. Amazon handles this automatically, but your system needs to be ready to accept a new challenge mid-subscription without breaking the customer's existing order history or subscription status. There are real limitations here. Amazon Payments doesn't give you full visibility into why a specific transaction was challenged. You get the result, not the reasoning. That means if a customer complains about being asked to verify repeatedly, you can't diagnose it from your side alone. The best you can do is check whether the transaction amount crossed a threshold or whether enough time had passed since the last authenticated session. Sometimes the issue is on the bank's side and nothing you do will change it.
Get the Full Details
Another bottleneck is the customer experience during the redirect. Some banking apps on older Android devices fail to deep-link back to your return URL after authentication. The customer ends up on a blank page or has to manually navigate back. This isn't an Amazon problem, but it's your problem to handle. I recommend adding a clear message on your return page telling customers what to do if they don't see their order confirmation immediately, and making sure your support team knows the common fixes for the major banking app issues. If you're processing a high volume of European transactions and the Amazon Payments SCA flow is creating too many drop-offs, you might consider maintaining your own 3D Secure integration alongside Amazon as a fallback path. It's more work to manage two payment flows, but it gives you direct control over the challenge UX and the ability to optimize for specific banks that Amazon's generic redirect doesn't handle well. This is something I recommended to a client who was losing roughly eight percent of their Scandinavian sales to auth failures, and after implementing the dual approach, the loss dropped to under two percent within a quarter. The configuration itself is straightforward. In your Amazon Payments dashboard, you'll find the SCA settings under your payment processing options. Make sure the risk-based authentication toggle is enabled so Amazon can minimize unnecessary challenges for low-risk transactions. Check that your webhook URLs are registered and returning 200 status codes. Test the full flow in sandbox mode with test cards that simulate different authentication outcomes before pushing anything to production. Amazon provides specific test card numbers for each scenario, and using them will save you from discovering edge cases in front of real customers.
One final detail that matters more than people think. When a customer cancels an SCA challenge, Amazon returns a different status code than if the authentication fails outright. Cancelled means the customer actively closed the banking app or refused the prompt. Failed means the bank rejected the credentials or the verification step didn't match. Your error handling should treat these differently. A cancelled challenge can sometimes be retried immediately by having the customer restart checkout. A failed authentication usually requires the customer to use a different payment method or contact their bank, so showing a retry button in that case just frustrates them further.